LC Ideas: Views & Insights
CIO Insights | China NPC - Steady Move Forward: Truth of The Tape
Sunil Garg Managing Director, Chief Investment Officer
Table of Contents
China's annual NPC opened with a solid, steady message rather than any dramatic announcements. Measured announcements include renewal of the 5% GDP growth target, admitting to challenges, particularly consumption and not getting carried away on tariff retaliation. Perhaps the most importantly was the expansion in the deficit (from 3% to 4%), highest in multiple decades.
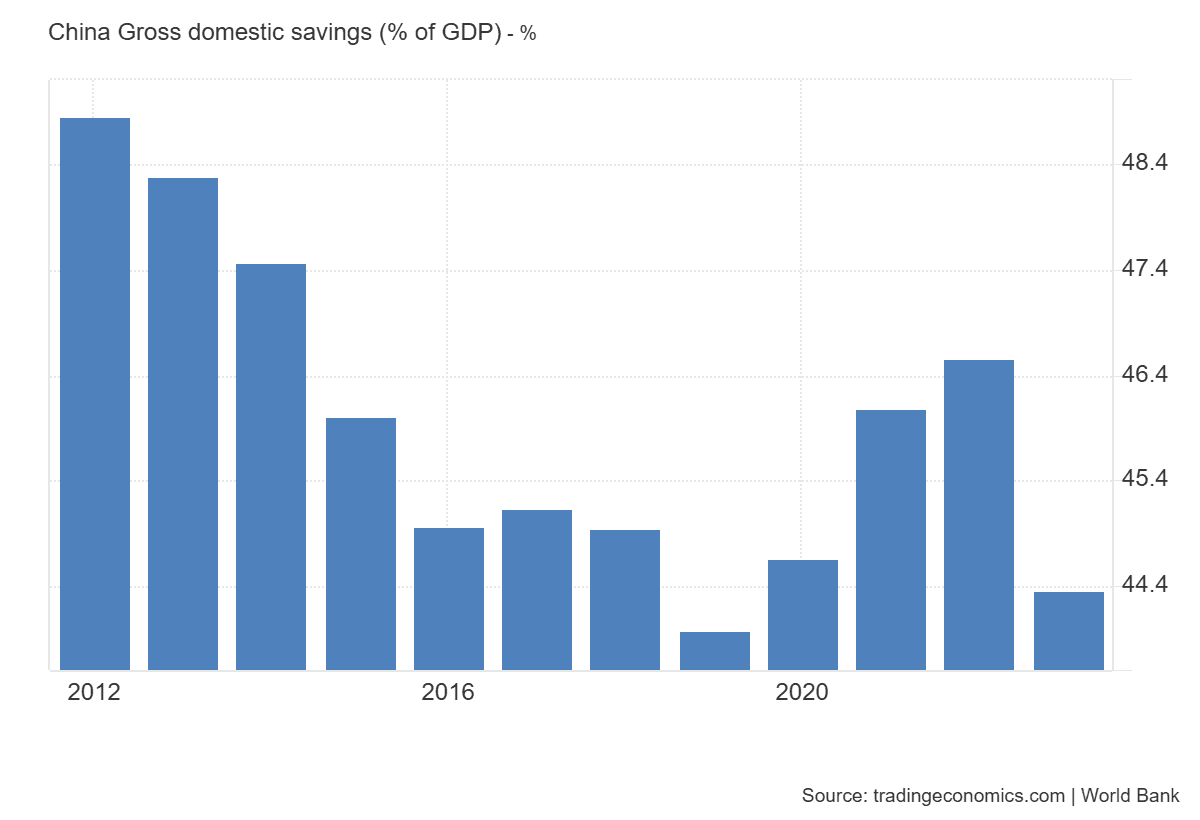
Western watchers have been quick to dismiss these as "modest" and "inadequate" to spur an economic revival. We disagree with the popular view that China needs a "helicopter" money solution to address consumption. We posit that weak consumption, despite an elevated household savings rate, reflects a lack of confidence rather than a lack of spending power. Balance sheet repair, that includes upstreaming state government debt and direct intervention in asset markets, is a slower process, but perhaps more sustainable.
Naysayers default to how bad the property market in China and hankering for a "bazooka" stimulus, will remain disappointed. However, the fact remains, that China is making steady, albeit slow, progress. Tech and Domestic consumption remain our preferred exposures.
Do You Need "Helicopter Money?" - Western economies have long been used to "helicopter money" (a term popularized by former FED Chair Ben Bernanke) - given typically low savings rates, this solution appears to have worked in short bursts although creates eventually creates inflationary problems. While there is persistent disappoint with China not adopting this solution, a bigger question is whether this is even the right solution for China? In our view, it isn't given the elevated savings rate - so a lack of money isn't the problem, rather a lack of confidence.
So How Do You Boost Confidence? - Long used to investment led growth, boosting confidence is a function of jobs and balance sheets, both of which have been damaged through a prolonged shut down. An over-supplied, over-leveraged property sector clearly being a major contributor to the malaise. Added to this were the woes of leveraged local government financing vehicles (LGFVs), essentially clogging the system of additional development spend. An upstreaming of state government debt (2024), direct intervention in asset markets, in our view, is a slower, but steadier approach to boost confidence.
But Isn't The Economy Still In The Doldrums? - Of course it is - but the more important question is, "is it improving at the margin"? Yes, we believe. While it's common to present metrics that aren't working, we provide below metrics that show improvements, volatile as the recovery may be.
GDP growth in 2024 topped the 5% target
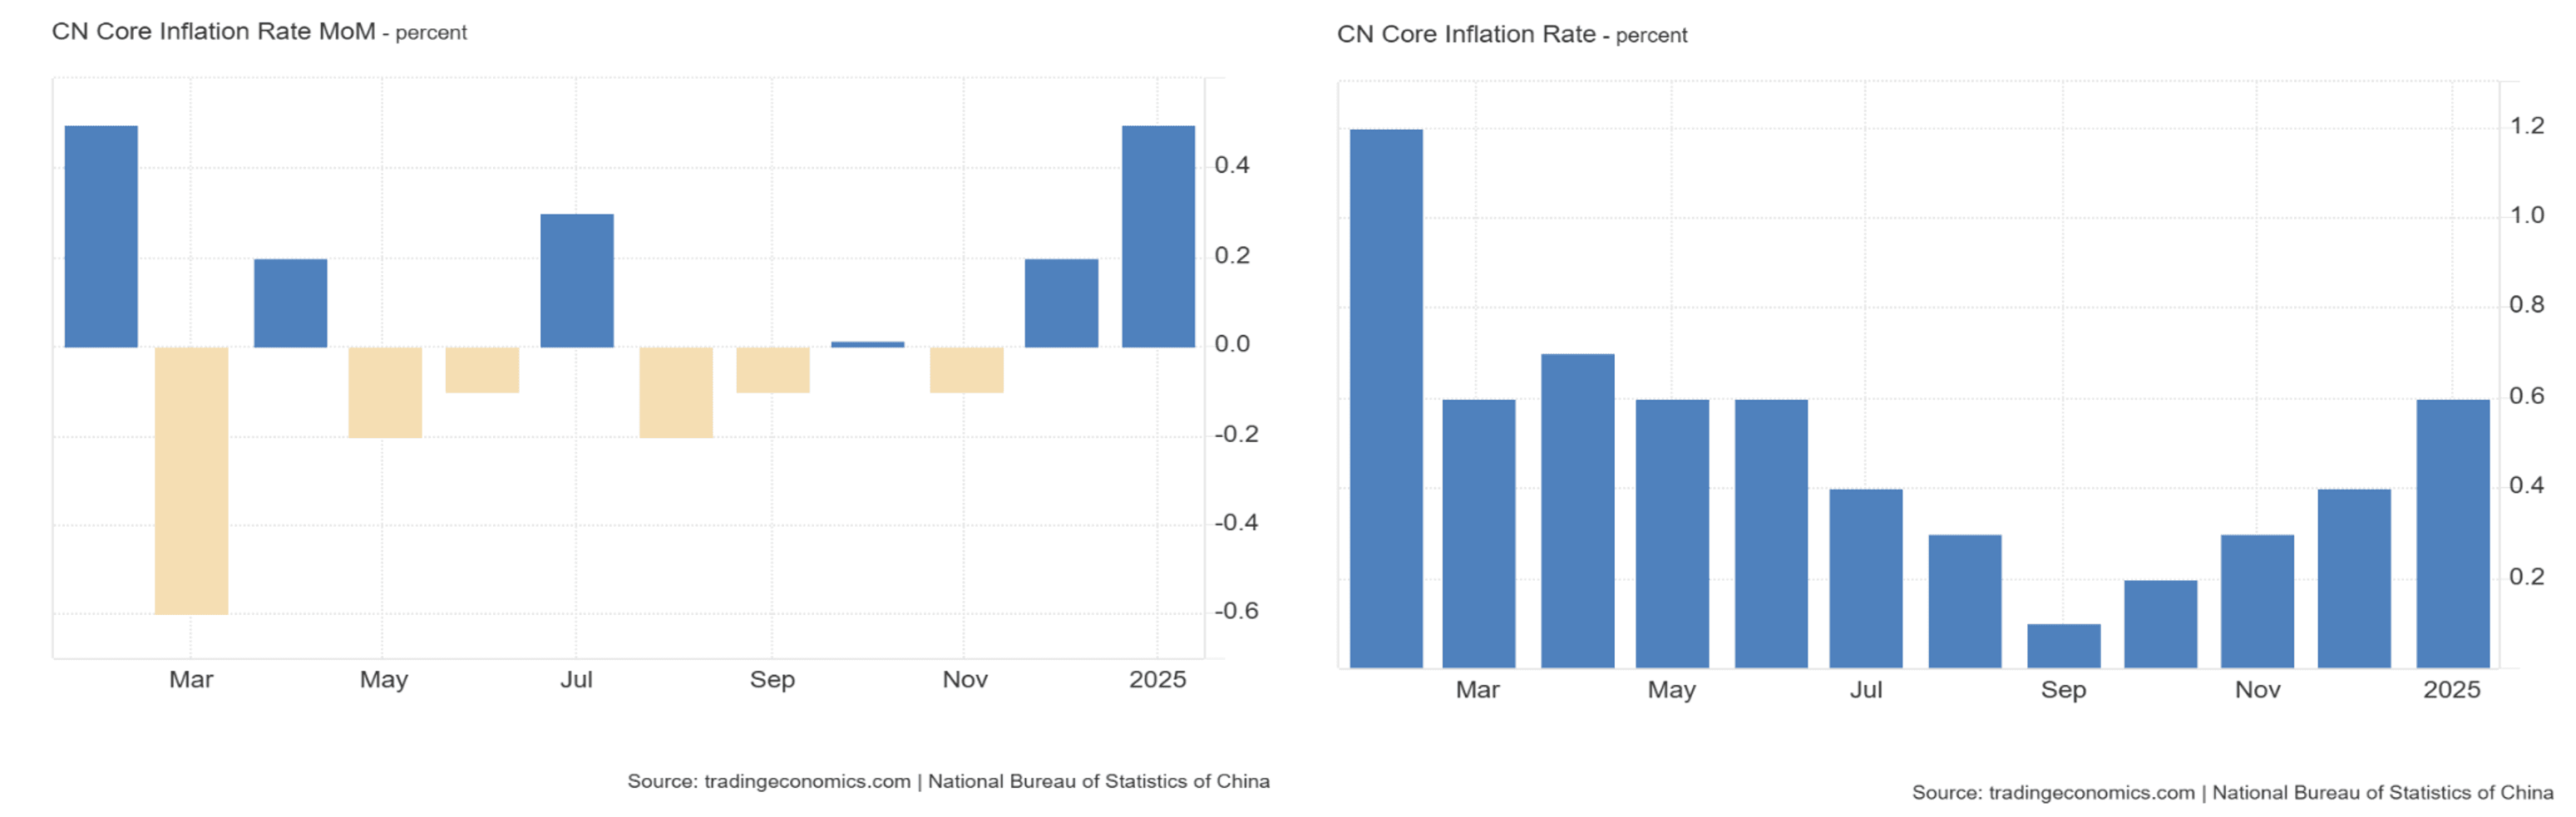
While PPI remains negative, core inflation metrics are no longer deflationary
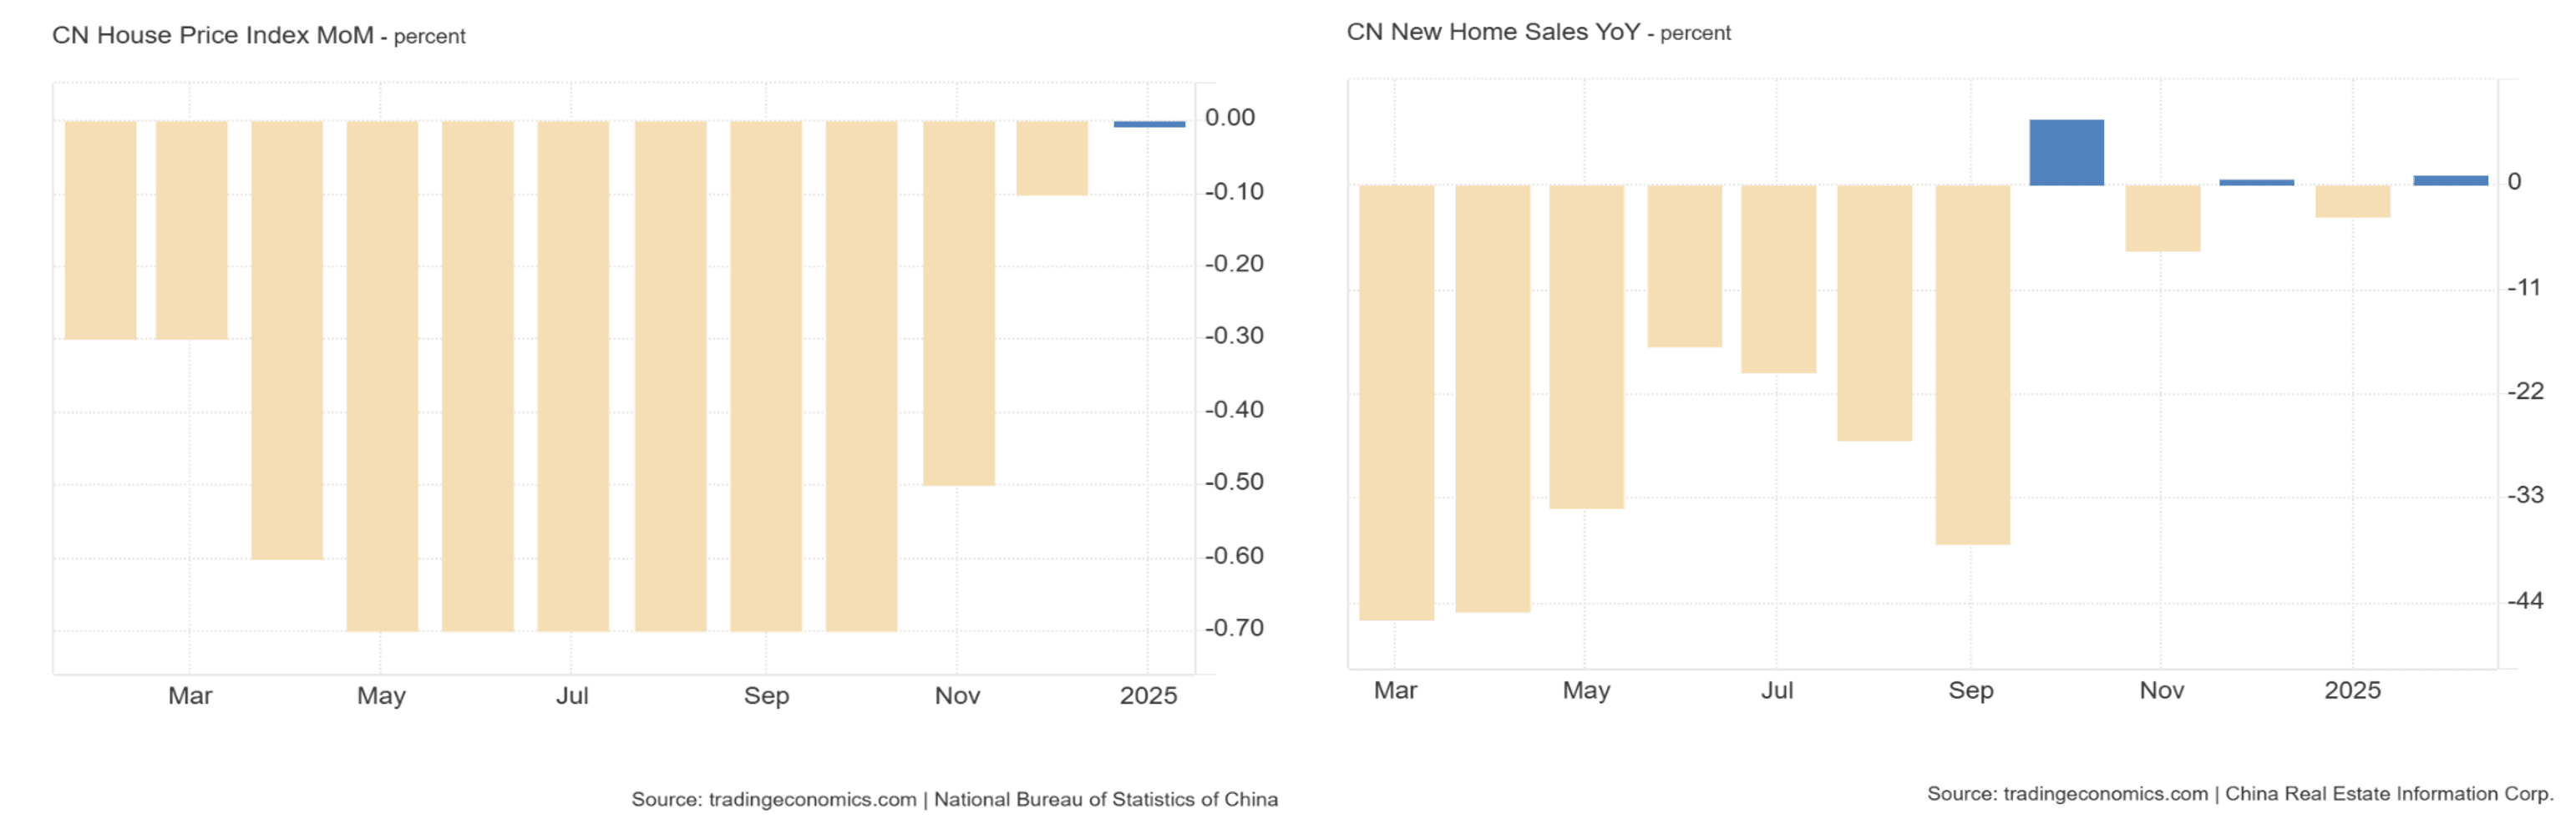
While residential property prices are still declining y/y, sequential (m/m) declines have materially slowed with latest readings very modestly positive
New home sales are no longer declining at the dramatic rates seen last year and are moderately positive
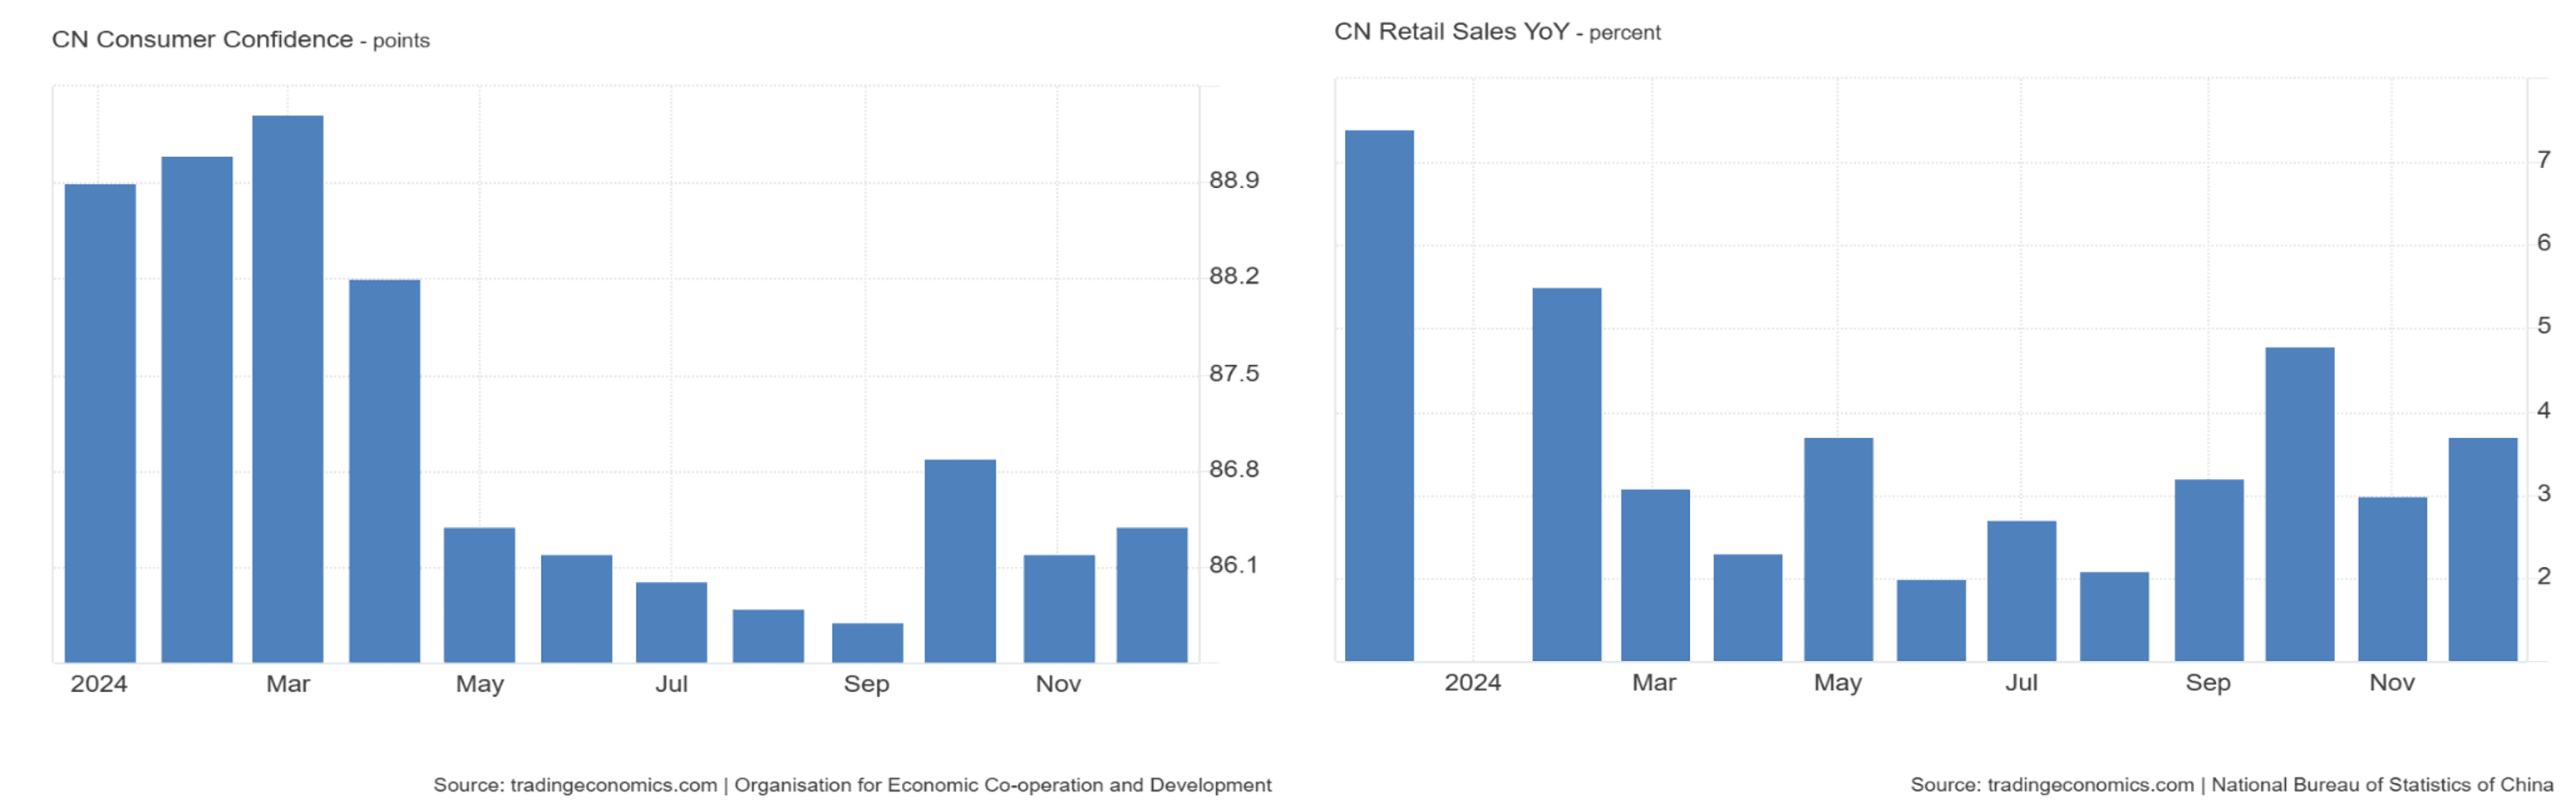
Consumer confidence is off the lows and retail sales have started to show a moderate recovery
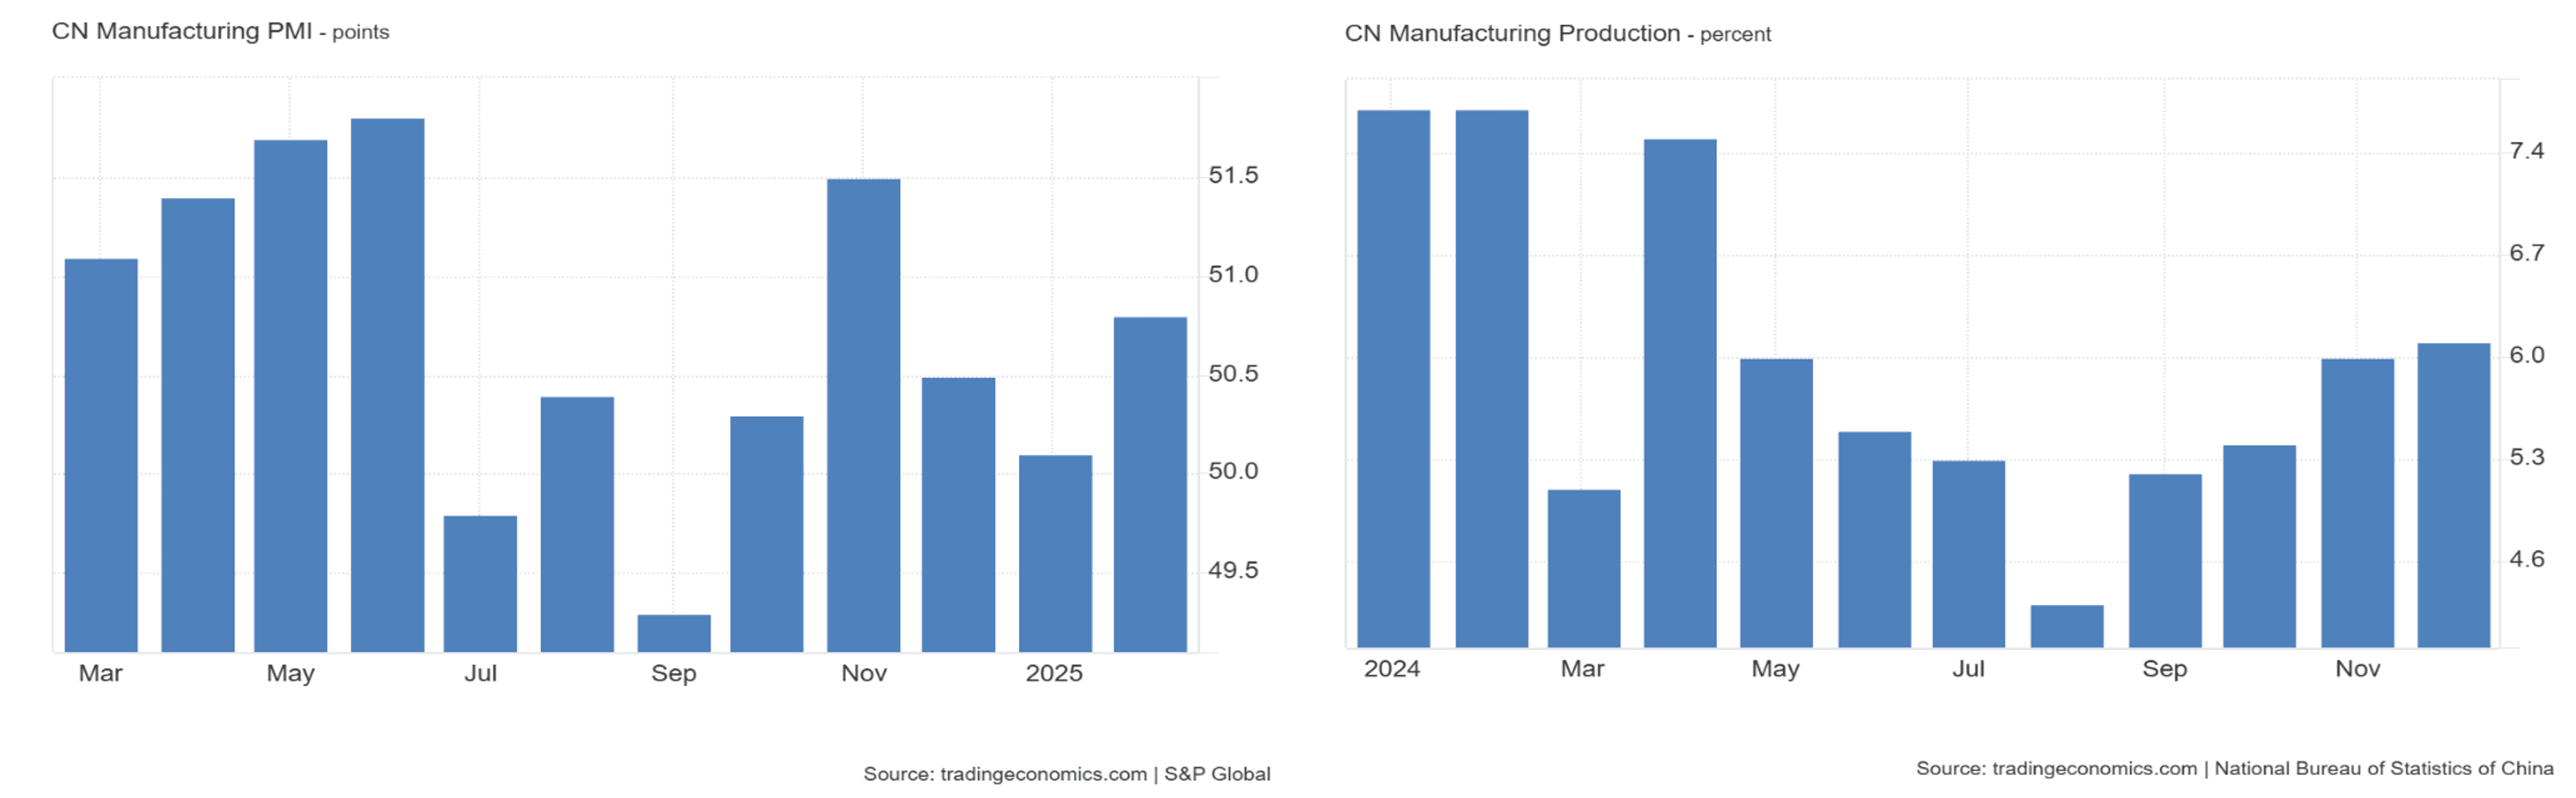
For businesses, PMI and confidence is better and capacity utilization is showing improvements
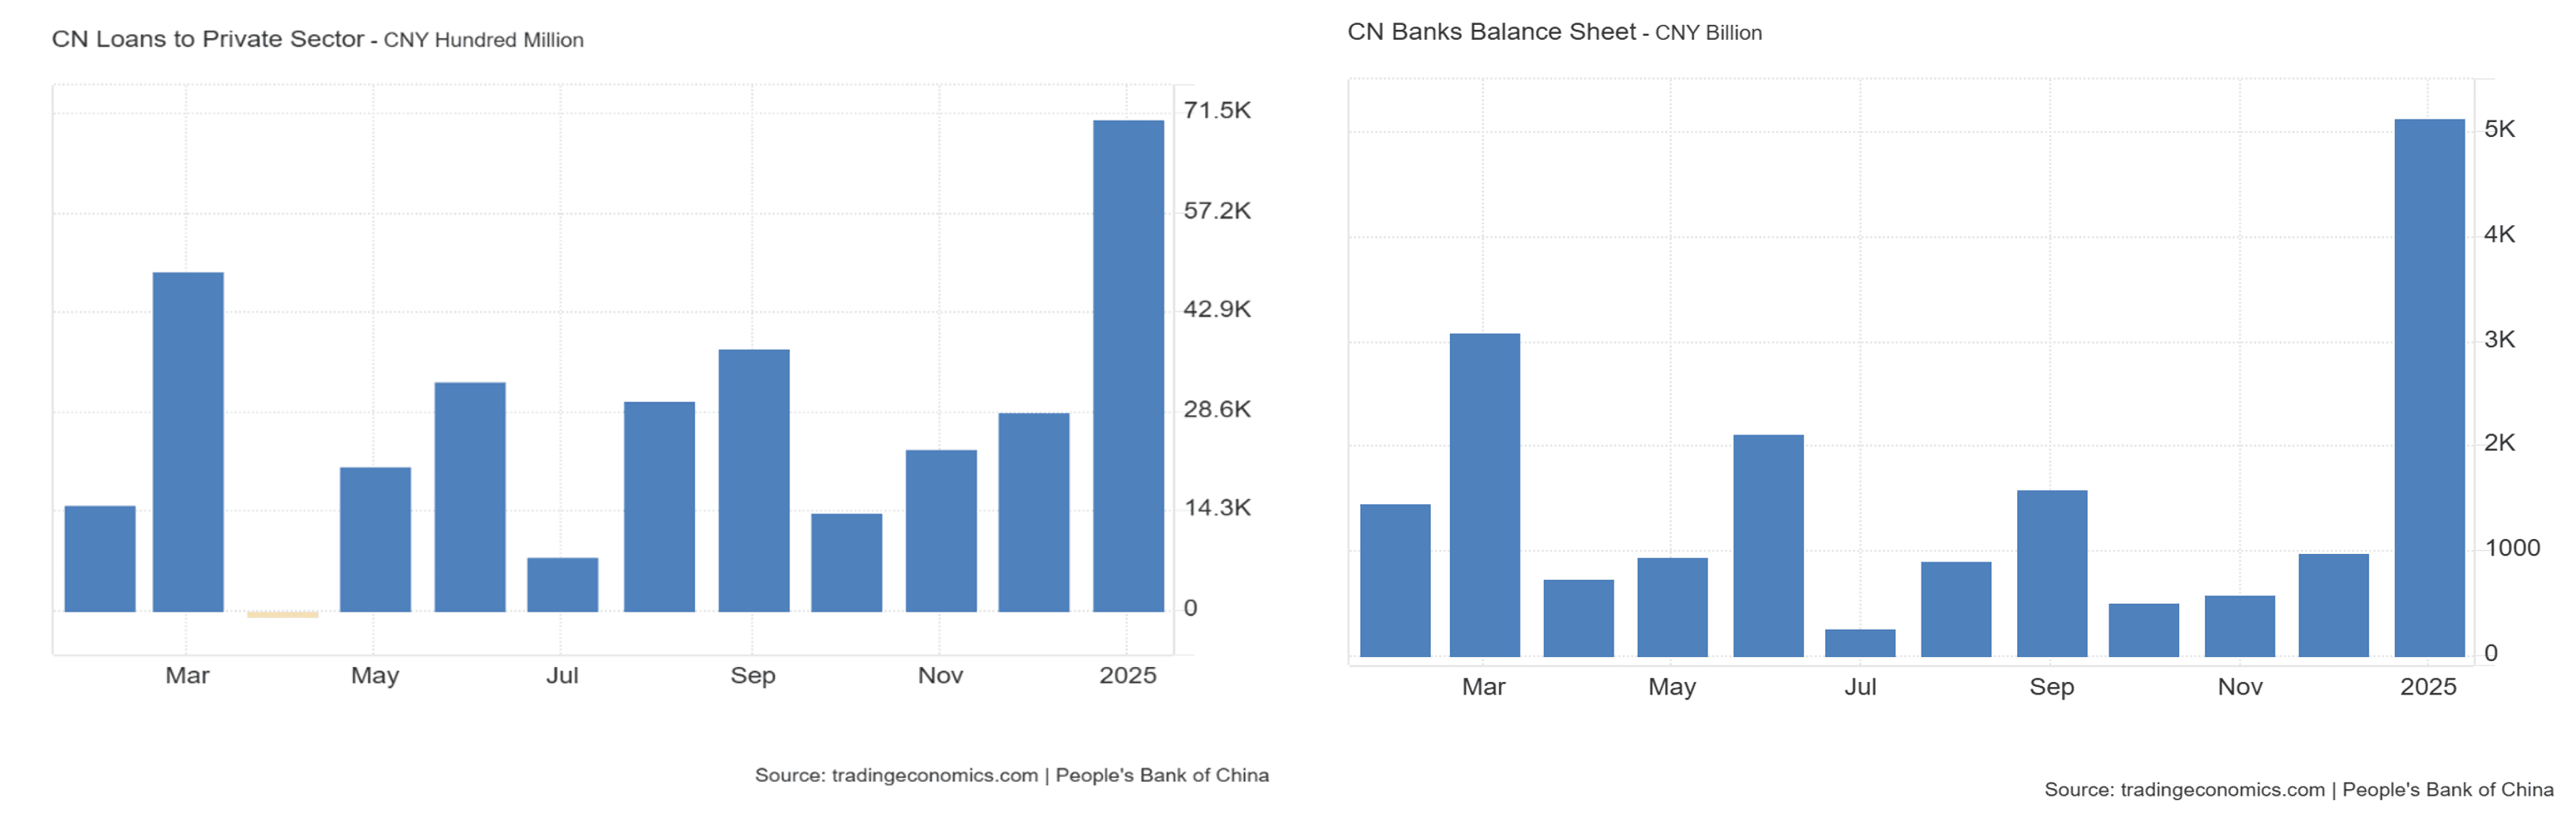
Bank loan growth and total social financing are showing improvements.
China - Savings Rates Remains Elevated
China - Inflation Metrics Improving
China - Housing Metrics Improving
China - Consumer Confidence and Retail Sales Improving
China - Business Outlook Improving
China - Loan Growth Improving
All investments carry risk, for more important information please read this disclaimer.