
Investment Insights
Equity Insights: All is not well with the Blackwell
Drishtant Chakraberty Senior Associate, Investment Consulting, Lighthouse Canton
Table of Contents
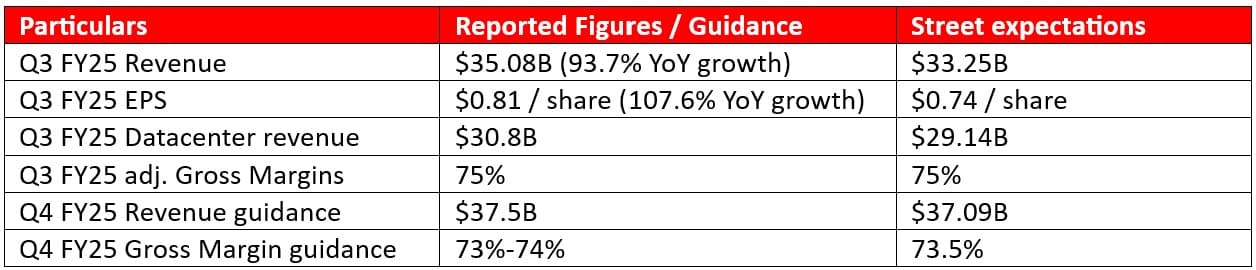
Nvidia's 93.6% YoY revenue growth and 107.6% YoY earnings growth for Q3 FY25 (accompanied with a stronger than expected guide for Q4 FY25) unfortunately could not "meet" the sky high expectations that Wall Street was working with. The company's guidance on Blackwell revenue ramp up stuck out as the pain point, with revenue recognition being pushed out by yet another quarter, what was originally supposed to start ramping up in Q2 FY25.
There were some positives as well, the biggest of which is that the company seems to have enough and more demand for its older generation - Hopper chips. While much of this demand continues to come from the hyperscalers, we believe enterprise customers are also eager to get their hands on these GPUs, which they were not able to do a couple of quarters back. As we move into Q4 FY25, the company has guided for a simultaneous ramp up of Blackwell revenue, while demand for Hopper continues to be robust and this should help increase revenues further and therefore meet Wall Street's incremental revenue growth expectations. The company also believes that based on current supply commitments it has managed to secure, Blackwell chips are likely to have excess demand for many quarters to come and going well into FY26.
Earnings Summary
Other notable insights from the release :-
Supply constraints suppressing shipments of both Hopper & Blackwell chips - The company spoke about certain supply constraints affecting their ability to potentially ship additional product to customers, especially given that the demand is definitely there. A crucial point to be noted is that Nvidia operates as a fabless chip designer and therefore depends on TSMC for manufacturing its chips and the fact that TSMC itself is fully booked out for the coming 18 months, does make it difficult for Nvidia to ramp up supply rapidly. Another aspect to consider here is that GPUs are not used in isolation and are actually used alongside memory chips which have been acting as an additional source of supply constraints due to Samsung (one of 3 major memory chip manufacturers globally) having its own set of issues with its high bandwidth memory (HBM) chip facing multiple design related issues. While the leader in the HBM space, SK Hynix has ramped up supply, it has not been enough to make up for the slower than expected launch by Samsung.
Blackwell gross margins likely to be in the mid 70s once ramped up - There were some concerns surrounding whether the company would be able to maintain the kind of margins it has been posting for the past year and a half, especially as they move to a newer and more complex chip platform. While the initial ramp up of Blackwell sales would undoubtedly have an impact on the blended margins of the company, what is a good sign is the management's expectations of being able to generate mid 70% gross margins on Blackwell sales once it has ramped up to a sufficiently high level.
Valuations and implications for the stock
Nvidia shares first touched $140 levels back in mid July and therefore they have been more or less flat for the past 4 months now. However, what has definitely not stayed stagnant are the company's earnings during that time period. Since then we have had a couple of quarterly earnings reports where earnings grew 165% YoY (Q2) and 108% YoY (Q3).
Given that a company's stock price is nothing but the P/E of the stock multiplied by its EPS, what the above has caused is a significant decline in the company's P/E ratio, making it a lot less expensive from a valuation multiple standpoint. Based on our calculations, the stock now trades at a TTM P/E of 56.3x and a 1-year fwd. P/E of 37.8x which is in no way cheap, but also not exorbitant in our opinion. As a point of reference, we would like to point out that Microsoft trades with a 1-year fwd. P/E ratio of 31x, while having a significantly lower growth rate.
All in all, we believe that the stock had probably run well ahead of its fundamentals back in June & July and since then the sideways movement in the share, accompanied with the company's EPS increasing significantly makes the stock much more reasonably valued.
Conclusion :-
We believe that the slightly negative stock price reaction seen post market, is justified, given that it was once again not a perfect quarter and when you're valued for perfection, you have to deliver just that.
Having said that, we maintain our long term bull thesis on the stock, given that it continues to enjoy insatiable demand for its products, curtailed only by how much it can produce and that is an enviable position to be in for any business. Datacenter related build outs continue to be very strong, with the hyperscalers continuing to spend at a rapid clip and we expect this to play out very favorably for Nvidia.
While there will be short term uncertainties surrounding the stock, what is for certain is that earnings will dictate future stock prices and as long as the company continues to grow its earnings, the stock is quite likely to continue to move higher, assuming there is no downward re-rating in the company's P/E ratio and we do not expect too big of an incremental downward re-rating (given how much it has corrected already), as the quality of the business is sublime and future growth prospects also seem to be robust.
All investments carry risk, for more important information please read this disclaimer.








