
Investment Insights
Equity Insights: Don’t fight the trend - Maintain equity exposure and overweight growth stocks
Drishtant Chakraberty Senior Associate, Investment Consulting, Lighthouse Canton
Table of Contents
Notwithstanding economic, geopolitical and labor market risks, for now, we need to respect the uptrend in equities, especially with the added optimism surrounding a revival in China. While volatility spikes are likely, we focus on growth stocks that bore the brunt of drawdowns in August and September – these names, now at more reasonable valuations, are likely to play catch up and outperform if the uptrend were to sustain. Do also note that we have progressively lowered hedges in our model portfolio to better align with the uptrend with a view to dynamically managing portfolio risk.
Specifically, tech hardware, industrials and utilities supporting data center build outs and luxury stand out as areas that offer attractive opportunities.
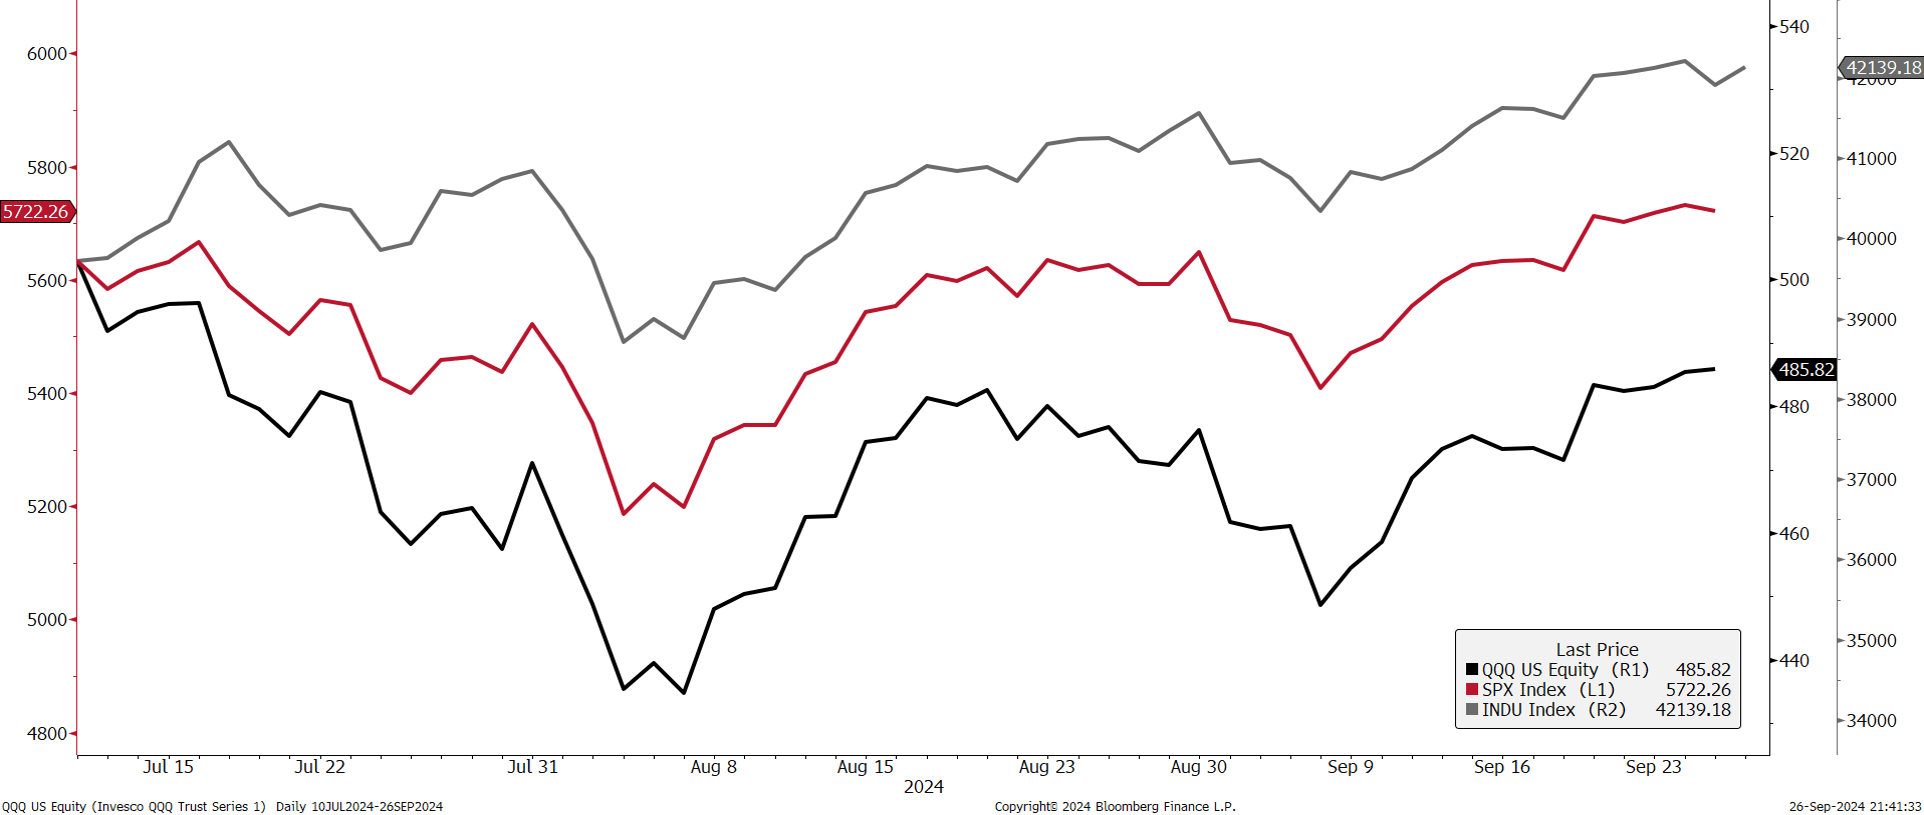
The Nasdaq 100 (QQQ US) has significantly underperformed the S&P 500 (SPX) and Dow Jones Industrial Average (INDU) over the past couple of months. We believe that there is scope for growth stocks to catch up and reduce this relative underperformance over the coming few months, especially if the current risk on rally sparked by the Fed's rate cut continues.
How to position
We are particularly bullish on the following themes, where we see value based on their future growth potential and current valuations :-
Tech hardware names, particularly those that are playing a crucial role in facilitating the use of AI and other high performance computing operations. Logic chip designers; memory chip designers; semiconductor manufacturers; wafer fab equipment manufacturers; AI server manufacturers and networking equipment providers are all part of this particular theme and we expect them to report strong earnings in the coming couple of quarters, especially as we see insatiable demand for AI related computing capacity, which drives the need for datacenter buildouts and associated hardware equipment. This week we saw Micron post a strong set of numbers, on the back of strong demand for their data center DRAM products which are used alongside the GPUs to build AI applications. Orders for high bandwidth memory chips has added a new stream of revenue for memory chipmakers.
Industrial companies and utility companies supporting data center buildouts have seen a significant increase in their order books over the past 12-18 months, providing 2–3-year revenue visibility. The significant number of data center buildouts and those specifically being built for accelerated computing has sparked a need for advanced cooling technology (liquid cooling) and upgradation of the power grid to support higher energy consumption that is bound come about in the near future. The pace of buildouts and demand for such services has increased the pricing power of these companies and this increase in pricing is flowing directly into the operating profits of these companies, which inherently tend to extract the advantage of operating leverage. While many such companies have seen a re-rating in their valuation multiples we believe there continue to be select bottom up opportunities where an investor stands to benefit from both P/E re-rating and EPS growth.
Luxury stocks have taken a massive beating over the past six months on the back of two of its largest markets (US & China) facing a slowdown in economic activity. Multiple high-quality names are now trading at valuation multiples that were last seen during the GFC in 2008. We would recommend sticking with companies that cater to the highest strata of luxury consumers, while staying away from affordable luxury players who tend to have a higher sensitivity to the prevailing economic environment. China is one of the largest luxury goods markets, which is currently experiencing the impact of what economists like to call ‘paradox of thrift’. The paradox states that an increase in autonomous saving leads to a decrease in aggregate demand and thus a decrease in gross output which will in turn lower total saving. PBoC’s monetary stimulus, along with the Government’s fiscal stimulus announced this week is targeted to induce people to start spending once again and we believe that this bodes well for all luxury stocks, which trade at depressed levels even after the bounce seen in these stocks, so far this week.
All investments carry risk, for more important information please read this disclaimer.








