Investment Insights
India’s Unloved Upside
Sunil Garg, CMT, Chief Investment Officer
India is beginning to look interesting for a reason that rarely makes headlines: the market has become out of favour.
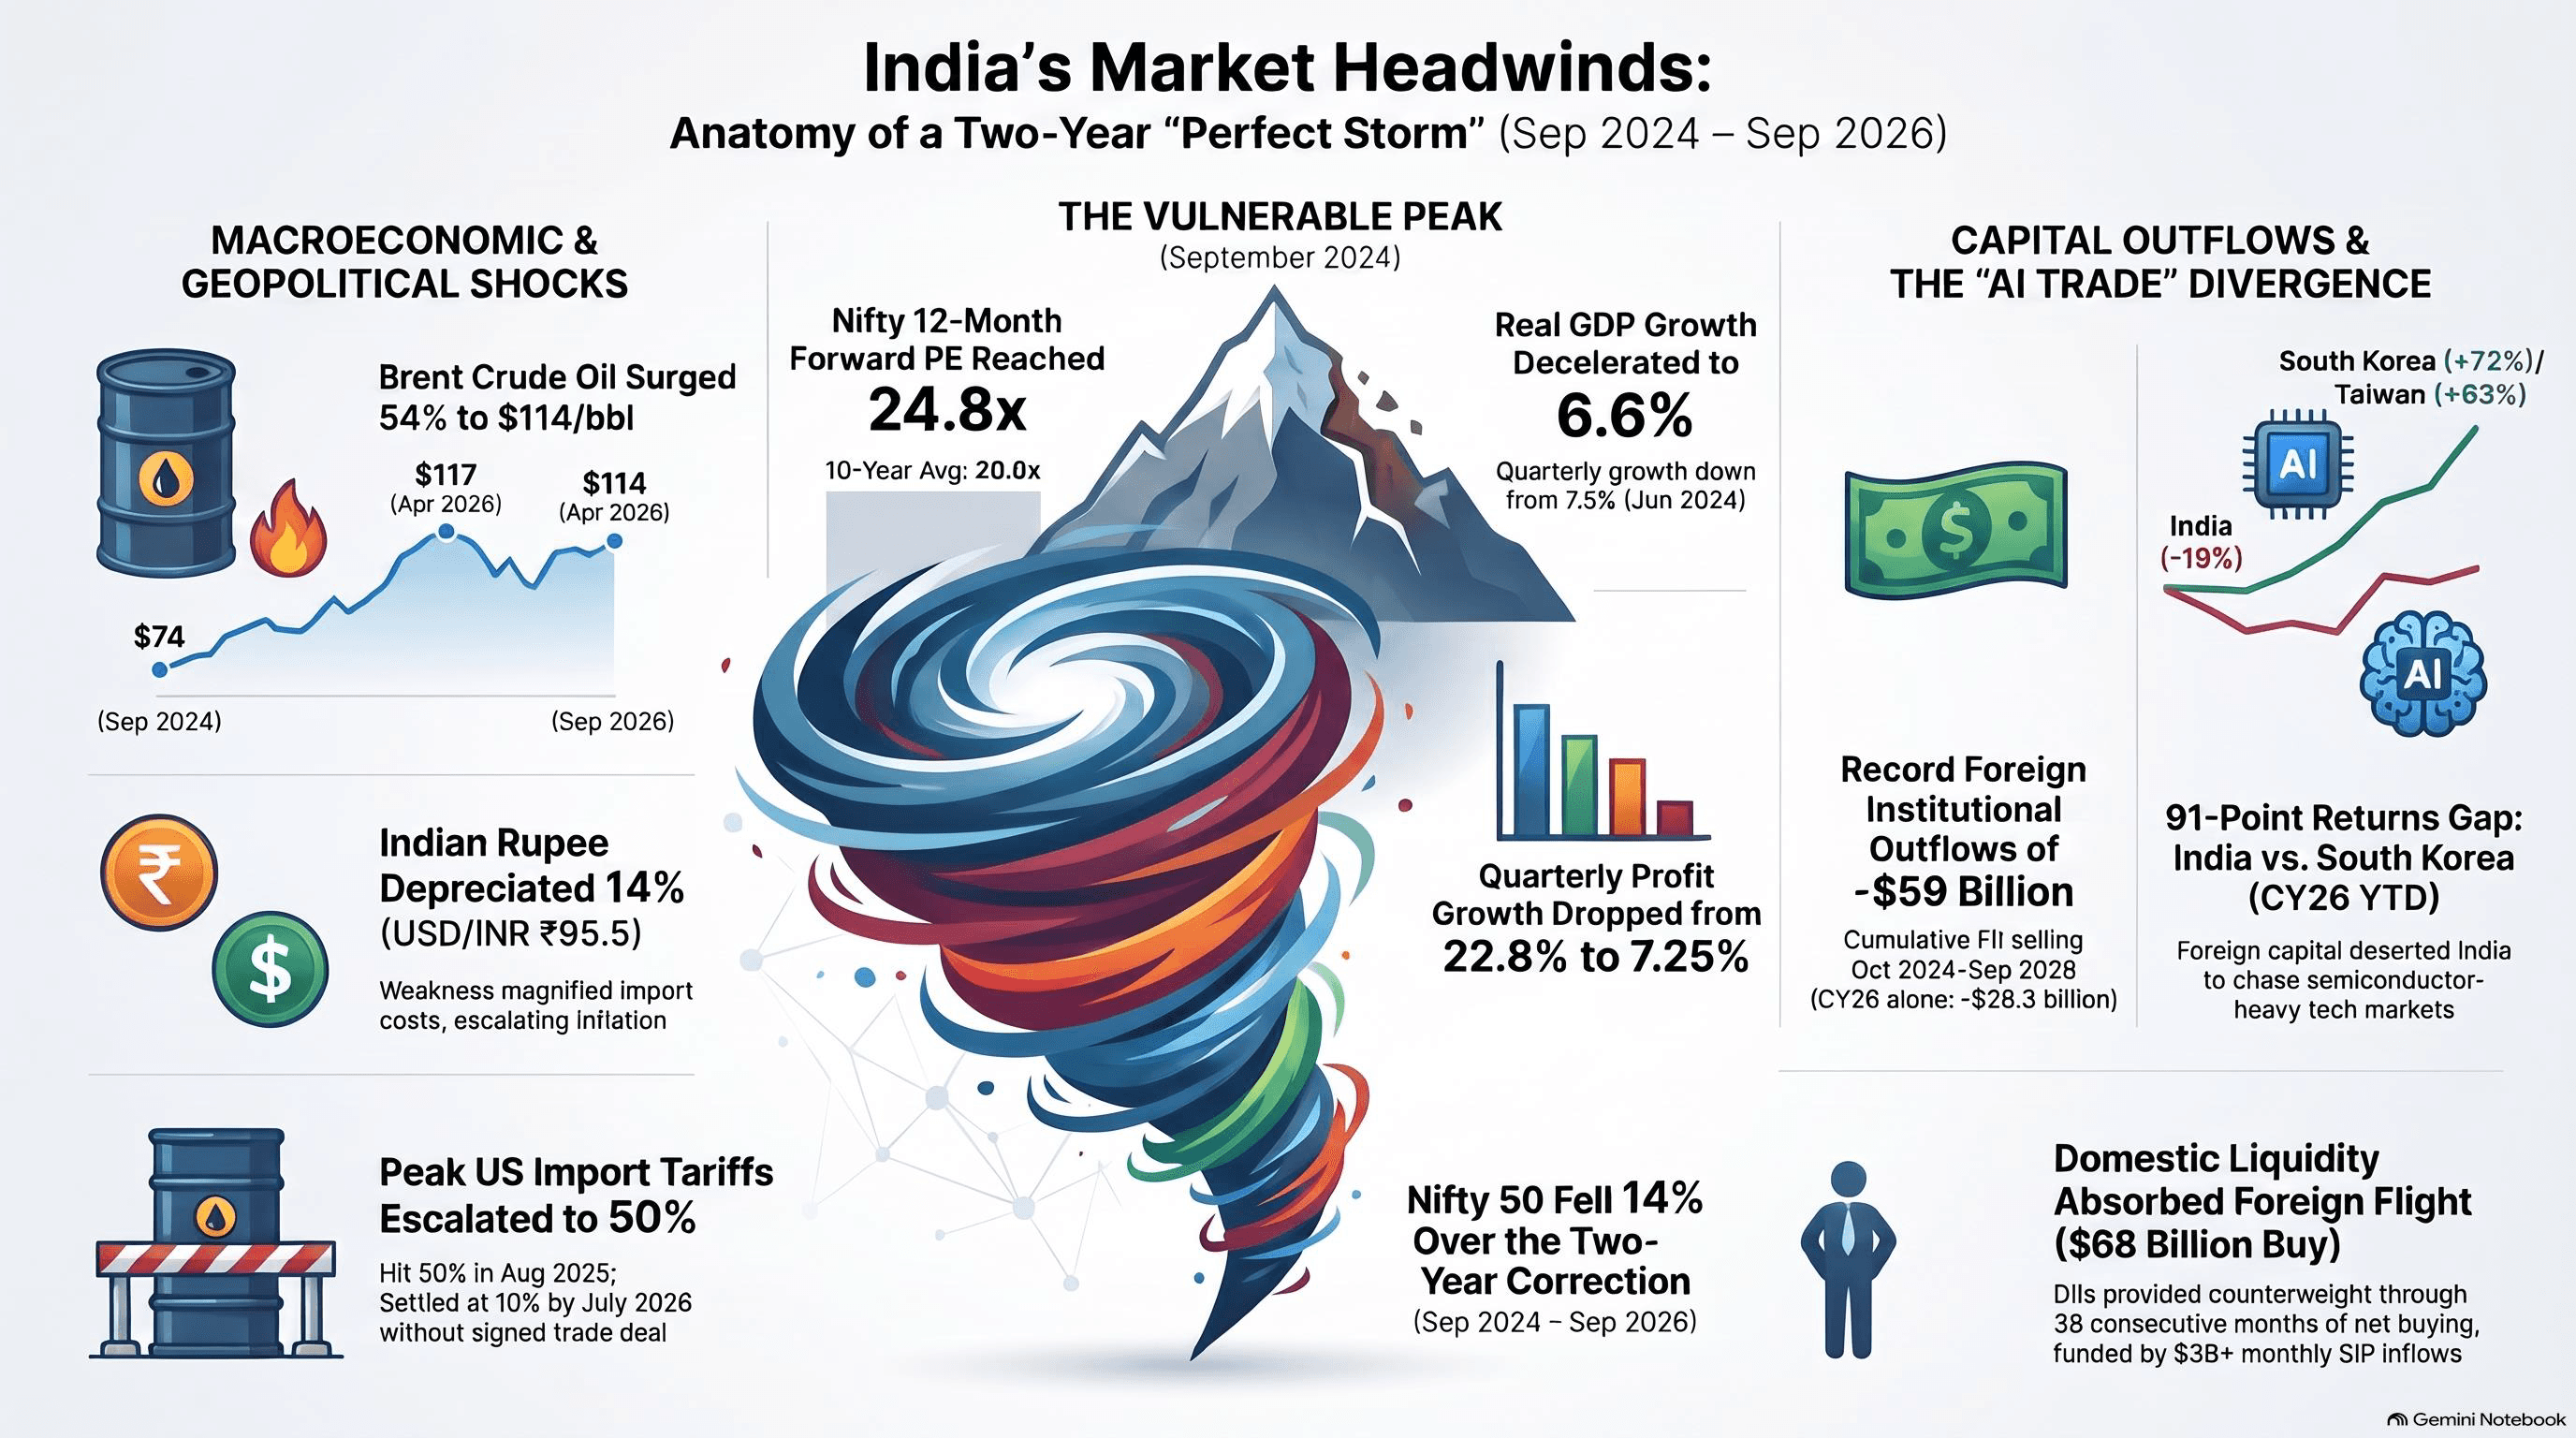
Foreign investors have been persistent sellers (net $59bn FII outflow, FY25-27), while India’s formerly expensive c25x earnings multiple has compressed toward 17x. That derating reflects a period of lacklustre earnings and revenue growth: Nifty 50 EPS growth was approximately 7% over FY25-FY26, with revenue growth around 8.5%. Investors have received little index appreciation and plenty of volatility over the last two years.
At the same time, global capital has had more obvious growth choices, particularly AI-led opportunities in the US and Asia. Attempts to create tangential AI linkages to India have done little to change that dynamic. India has delivered at the economic level but has so far struggled to convert that performance into corporate earnings.
That degree of pessimism may ultimately become a source of upside. This is changing at the margin.
India - A Perfect Storm
What is Changing - Earnings Optimism, Reasonable Valuations, Resilience & Policy Optimism
FY27 earnings expectations are now beginning to improve. Revenue growth is expected to move back into the low double digits, while EPS growth estimates are broadly in the mid-teens (Jun’26 and Sep’26 EPS growth at 18% and 27% respectively). At approximately 17x forward earnings, valuations are more reasonable, though not universally cheap, and the market’s earnings burden is becoming more manageable.
India also offers an unusual degree of resilience in a market increasingly dominated by AI enthusiasm. As global investors reassess crowded AI trades in the United States and parts of Asia, India can act as a liquid “AI hedge” - a large, investable market driven more by domestic consumption, financialization, infrastructure, manufacturing and services than by the immediate AI hardware cycle.
Policy Change - India has already moved to make its market more accessible to foreign capital, including exemptions from income tax on interest and capital gains earned by foreign portfolio investors in government securities from April 2026. The finance minister has also indicated that the government is open to stakeholder views on reducing capital-gains taxes on stock-market investments (no specific measures announced yet).
Without doubt, risks remain - oil price volatility remains a threat to inflation, deficits and the currency. Additionally, AI proliferation poses severe business model challenges to one of the largest organized sector employers, IT Services. Structural challenges remain, but cyclical opportunities have emerged - India does not need a new story. It needs existing investors to recognise that the story has become cheaper, earnings are recovering and the market is no longer as crowded as it once was. The opportunity lies not in chasing India at peak enthusiasm, but in buying while the narrative is still under-owned, and before foreign flows, policy reform and earnings momentum begin to reinforce one another.
What Ailed Indian Equities | What’s Changing |
|---|---|
Expensive PE Multiples (24-25x) | Currently 17x |
Anaemic Earnings and Revenue Growth Nifty - Revenue cagr of 8.5%; EPS cagr of 7% BSE 500 - Revenue cagr of 8.4%; EPS cagr of 8.2% | FY 2027 (Apr ‘26 - Mar’27) expected revenue growth of 12-13% and EPS growth of 16-17% (Jun’26 18% and Sep’26 27%) |
AI led growth opportunities in the US, Korea, Taiwan, Japan | Markets questioning AI monetization as free cash flows turn negative |
Currency Depreciation | Record FCNR (B) flows help stabilize the Rupee (risks remain from oil volatility) |
High Capital Gains Tax | Potential easing of capital-gains tax for foreign investors |
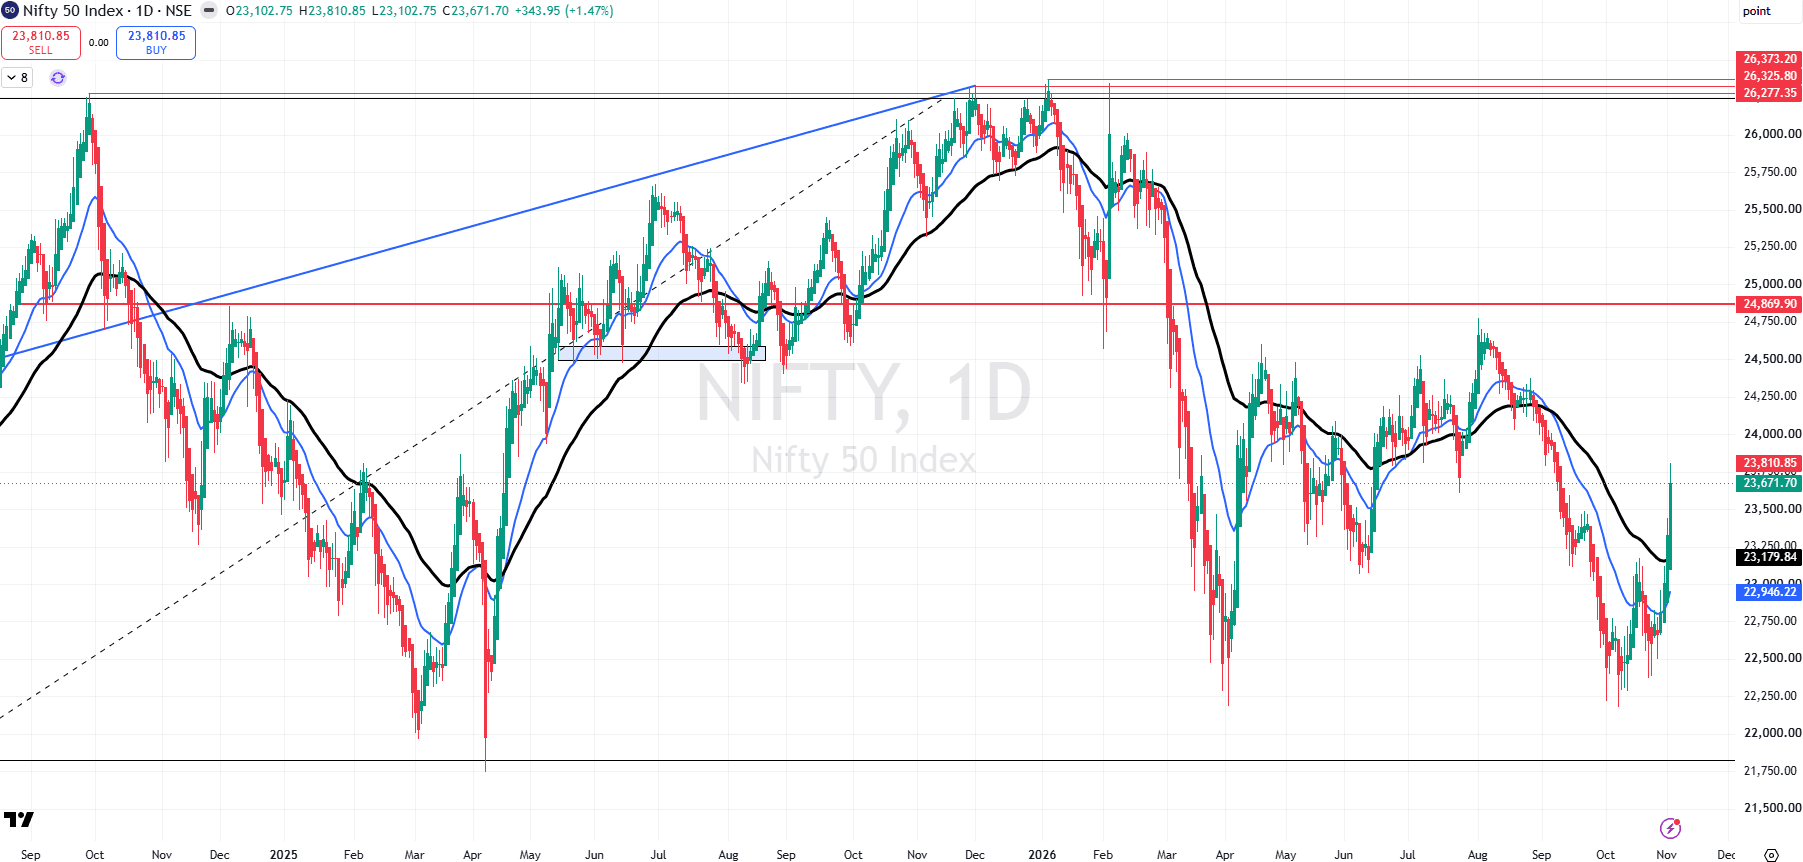
Nifty - Reversing a Downtrend?
Nifty’s gone nowhere for last two years. Policy promise and risks to the AI trade and a bounce off key 22,000 support levels offer optimism
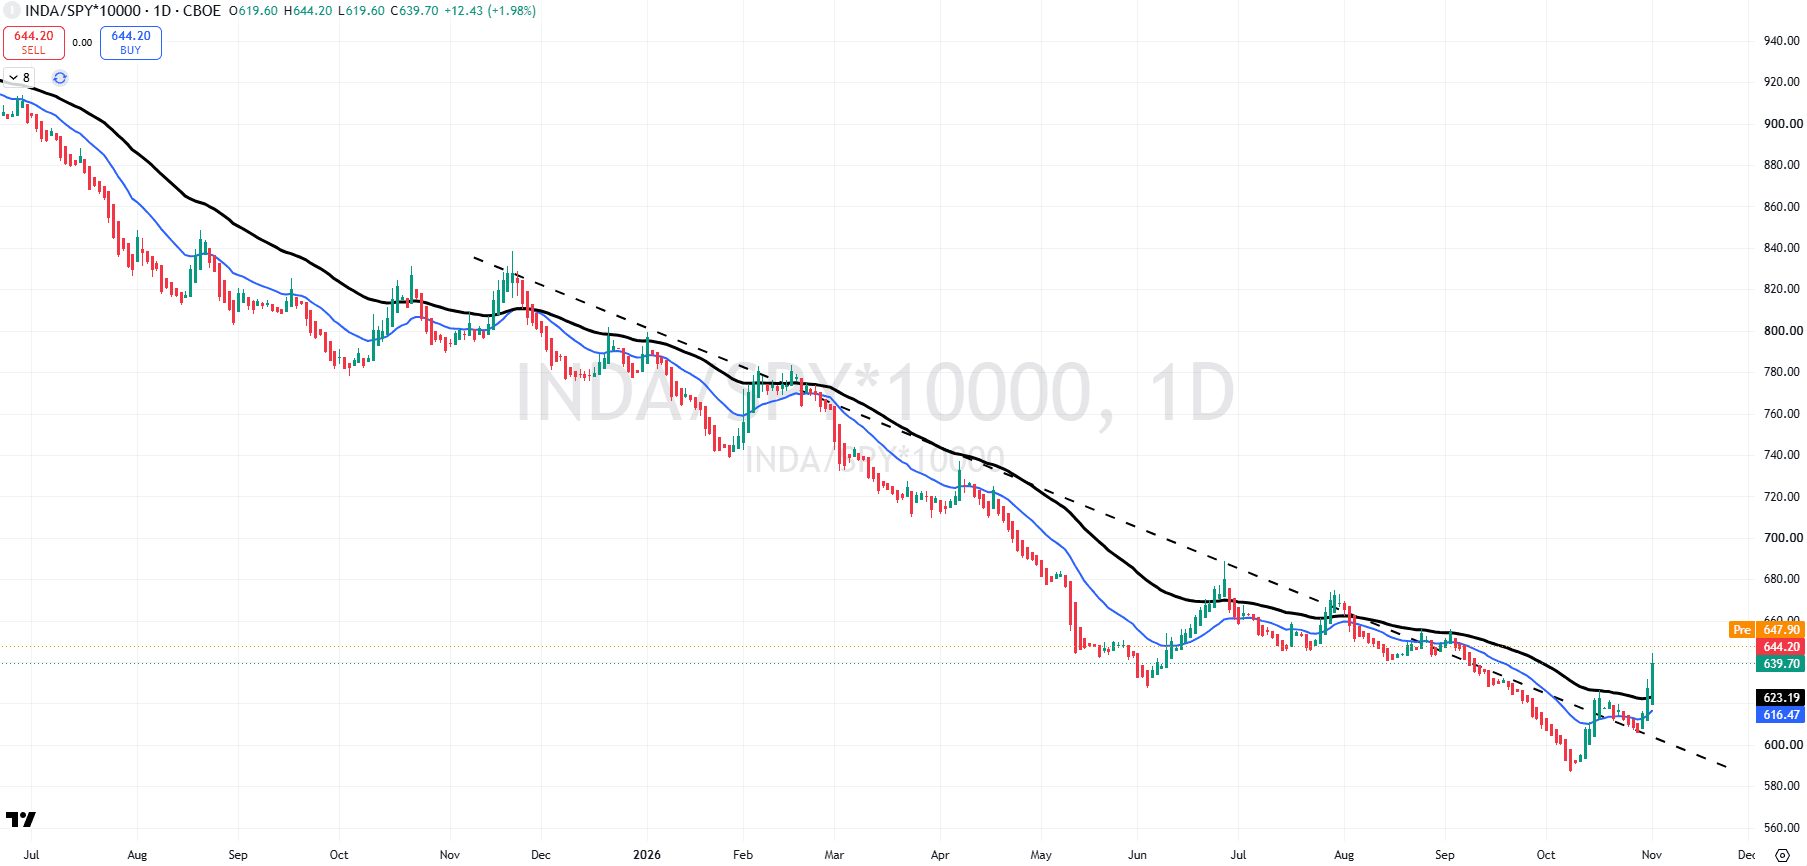
INDA vs. SPY - Will This Breakout Hold?
A steady under-performer over the last two years, INDA appears to be reversing up, relative to SPY. Momentum and trend indicators support a positive move
Where to Invest
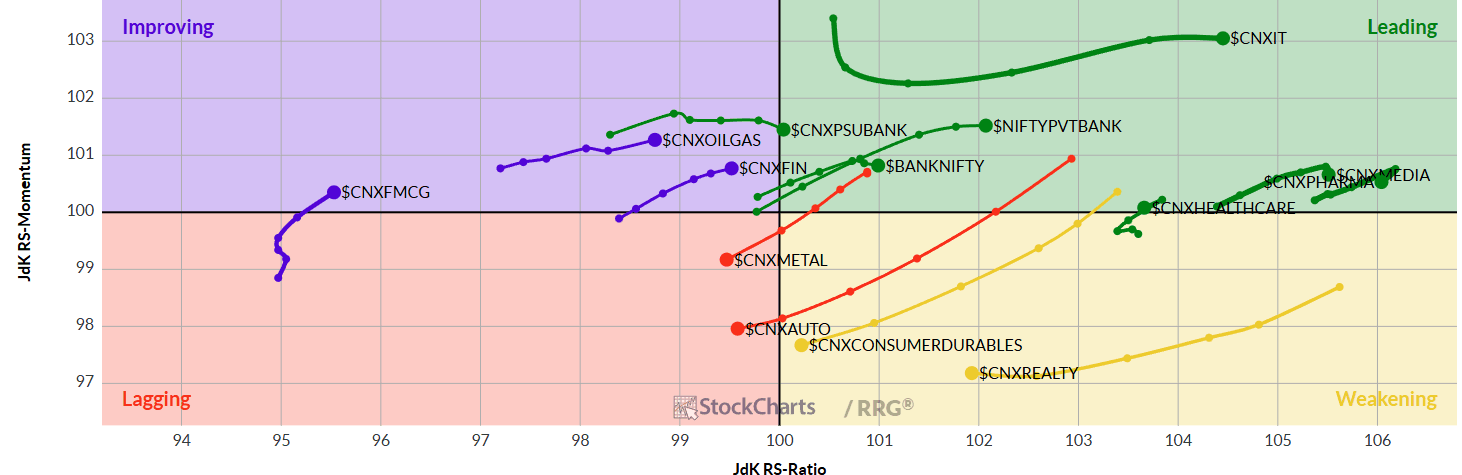
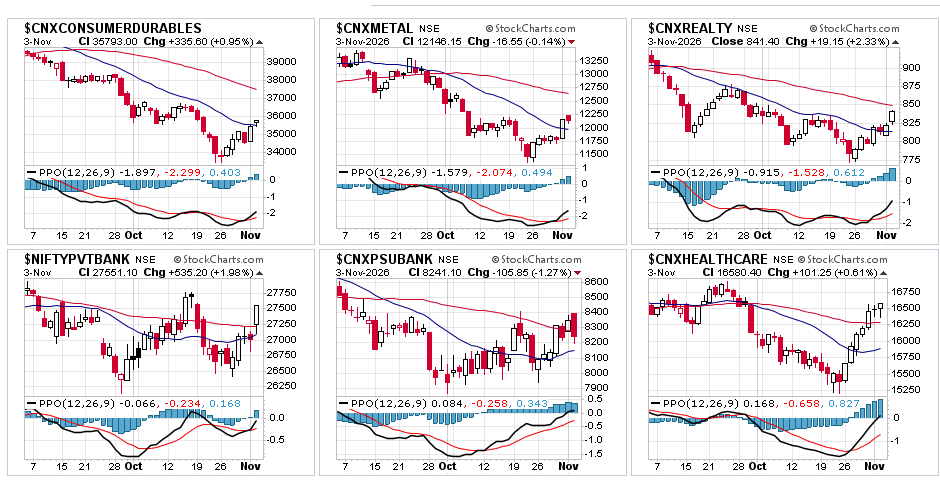
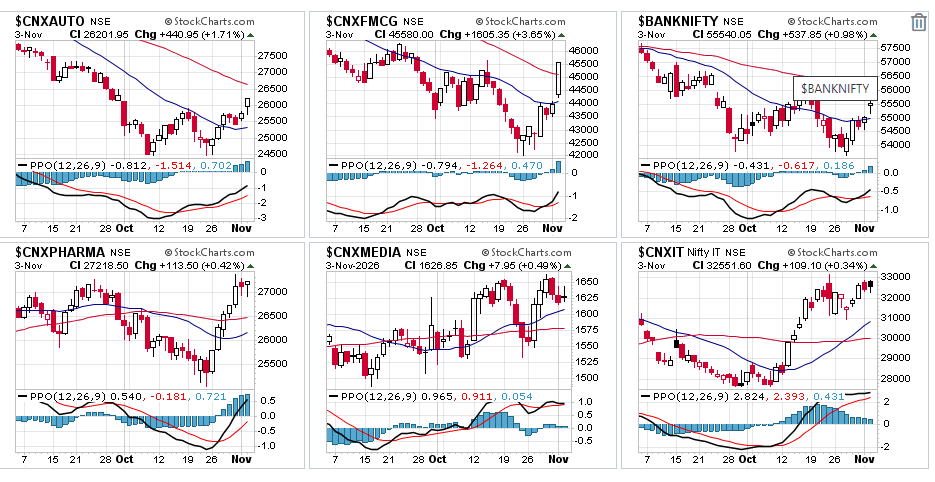
Most sectors reflect early days in a breakout (see below sectors at a glance).
Rotational trends favor banks and financials with emerging optimism on the beaten down FMCG sector
Sectors At a Glance
Disclaimer: Lighthouse Canton Pte Ltd. (“LCPL”) is incorporated in the Republic of Singapore (Registration No: 201422117K) and regulated by the Monetary Authority of Singapore (Capital Markets Services Licence No. CMS100443). Lighthouse Canton Capital (DIFC) Pte Ltd (“LCC”) is incorporated in Dubai International Financial Centre (Licence No. CL 2614) and regulated by Dubai Financial Services Authority (Category 3C Licence No. F004068). The financial products offered by LCPL and LCC are only available to Accredited Investors and Institutional Investors as defined by MAS and Professional Investors as defined by DFSA. The information in this electronic transmission does not constitute an offer, or intention by, or on behalf of LCPL and/or LCC, to subscribe, purchase or sell any financial products and/or services. LCPL and LCC accept no liability for any loss arising from the use of any information contained herein. The contents of this email are confidential and meant for the intended recipient only.


