Investment Insights
Leveraged Covered Calls
Sunil Garg, CMT, Chief Investment Officer
In the money covered calls (ITM CC) offer a combination of returns with downside protection - not dissimilar to single name FCNs. There is however a trade-off - greater protection comes with lower coupons. What if we could target higher coupons and yet have deep protection? Issuers often structure this through leveraged FCNs - the challenge with such structures is secondary liquidity, as well as substantial issuer fees. Enter, Leveraged Covered Calls.
Structure (with example)
Long Stock - Micron (MU) @1074.89
Short Deep in the Money Calls (400 Strike/ 17 Sep 2027)
Moderate leverage (c35% of current stock price)
Equity Needed = Share Price less Call Premium less Leverage
Leverage Cost - assumed at 5%
Highlights:
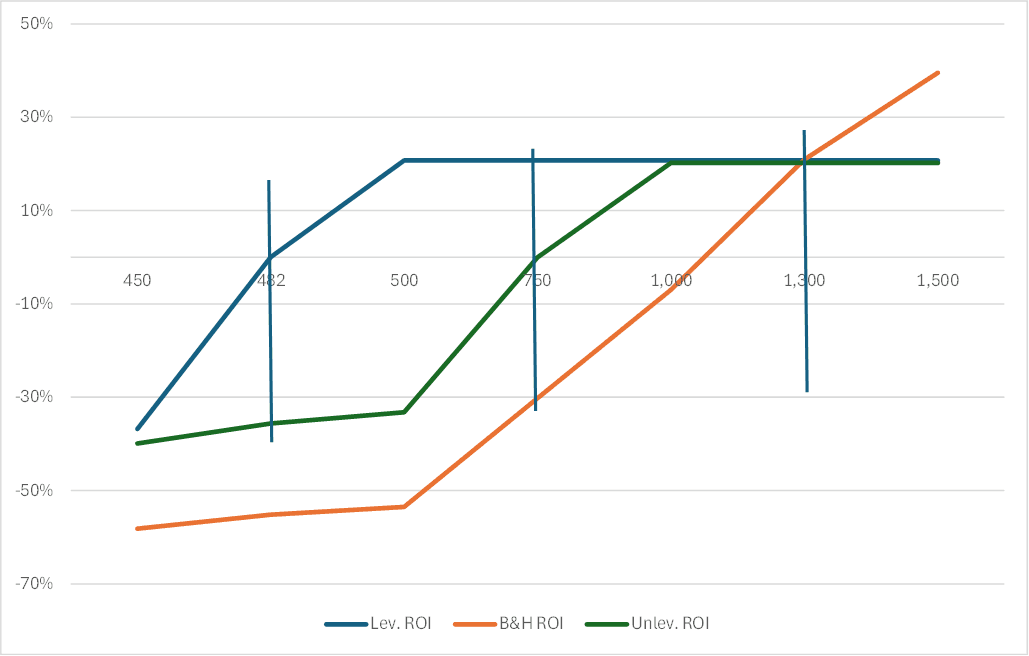
Unleveraged returns for the same strike are 8% (vs. 20.7% for the leveraged version)
Similar returns in an leveraged structure have a 30% downside protection vs. 55% in the leveraged structure
Losses amplify below breakeven
Ability to early close (if vols compress/ underlying rallies or both) - unlike an FCN.
Suitability & Risks
Investors comfortable with MTM volatility
Investors willing to assume larger leverage for returns but entail higher losses on drop below breakeven
Investors willing to forego upside in case of a sharp rally
Allows small ticket participation (upfront equity needed is 1/5th)
RISKS - A sharp drop (c65% of spot) can wipeout the equity
RISKS - Rate Sensitivity - Every 100bp in higher interest costs knocks off c400bp of returns.
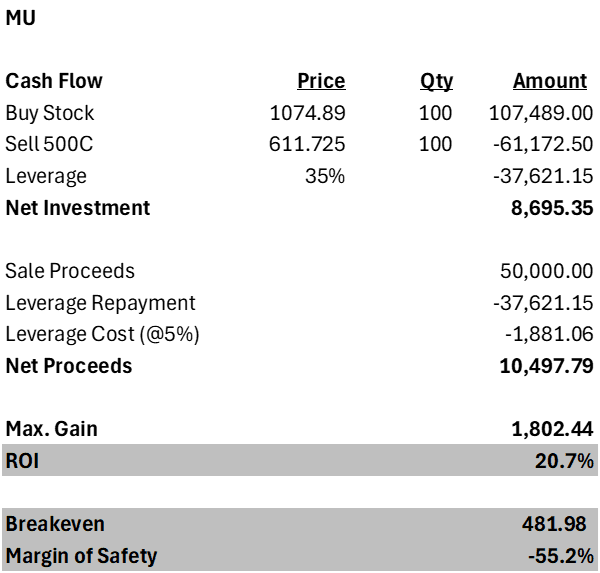
Pay-off Structure - B&H vs. Leveraged vs. Unleveraged ITM Covered Call