
Investment Insights
Oil, The Forgotten Commodity… | CIO Insights
Sunil Garg Managing Director, Chief Investment Officer
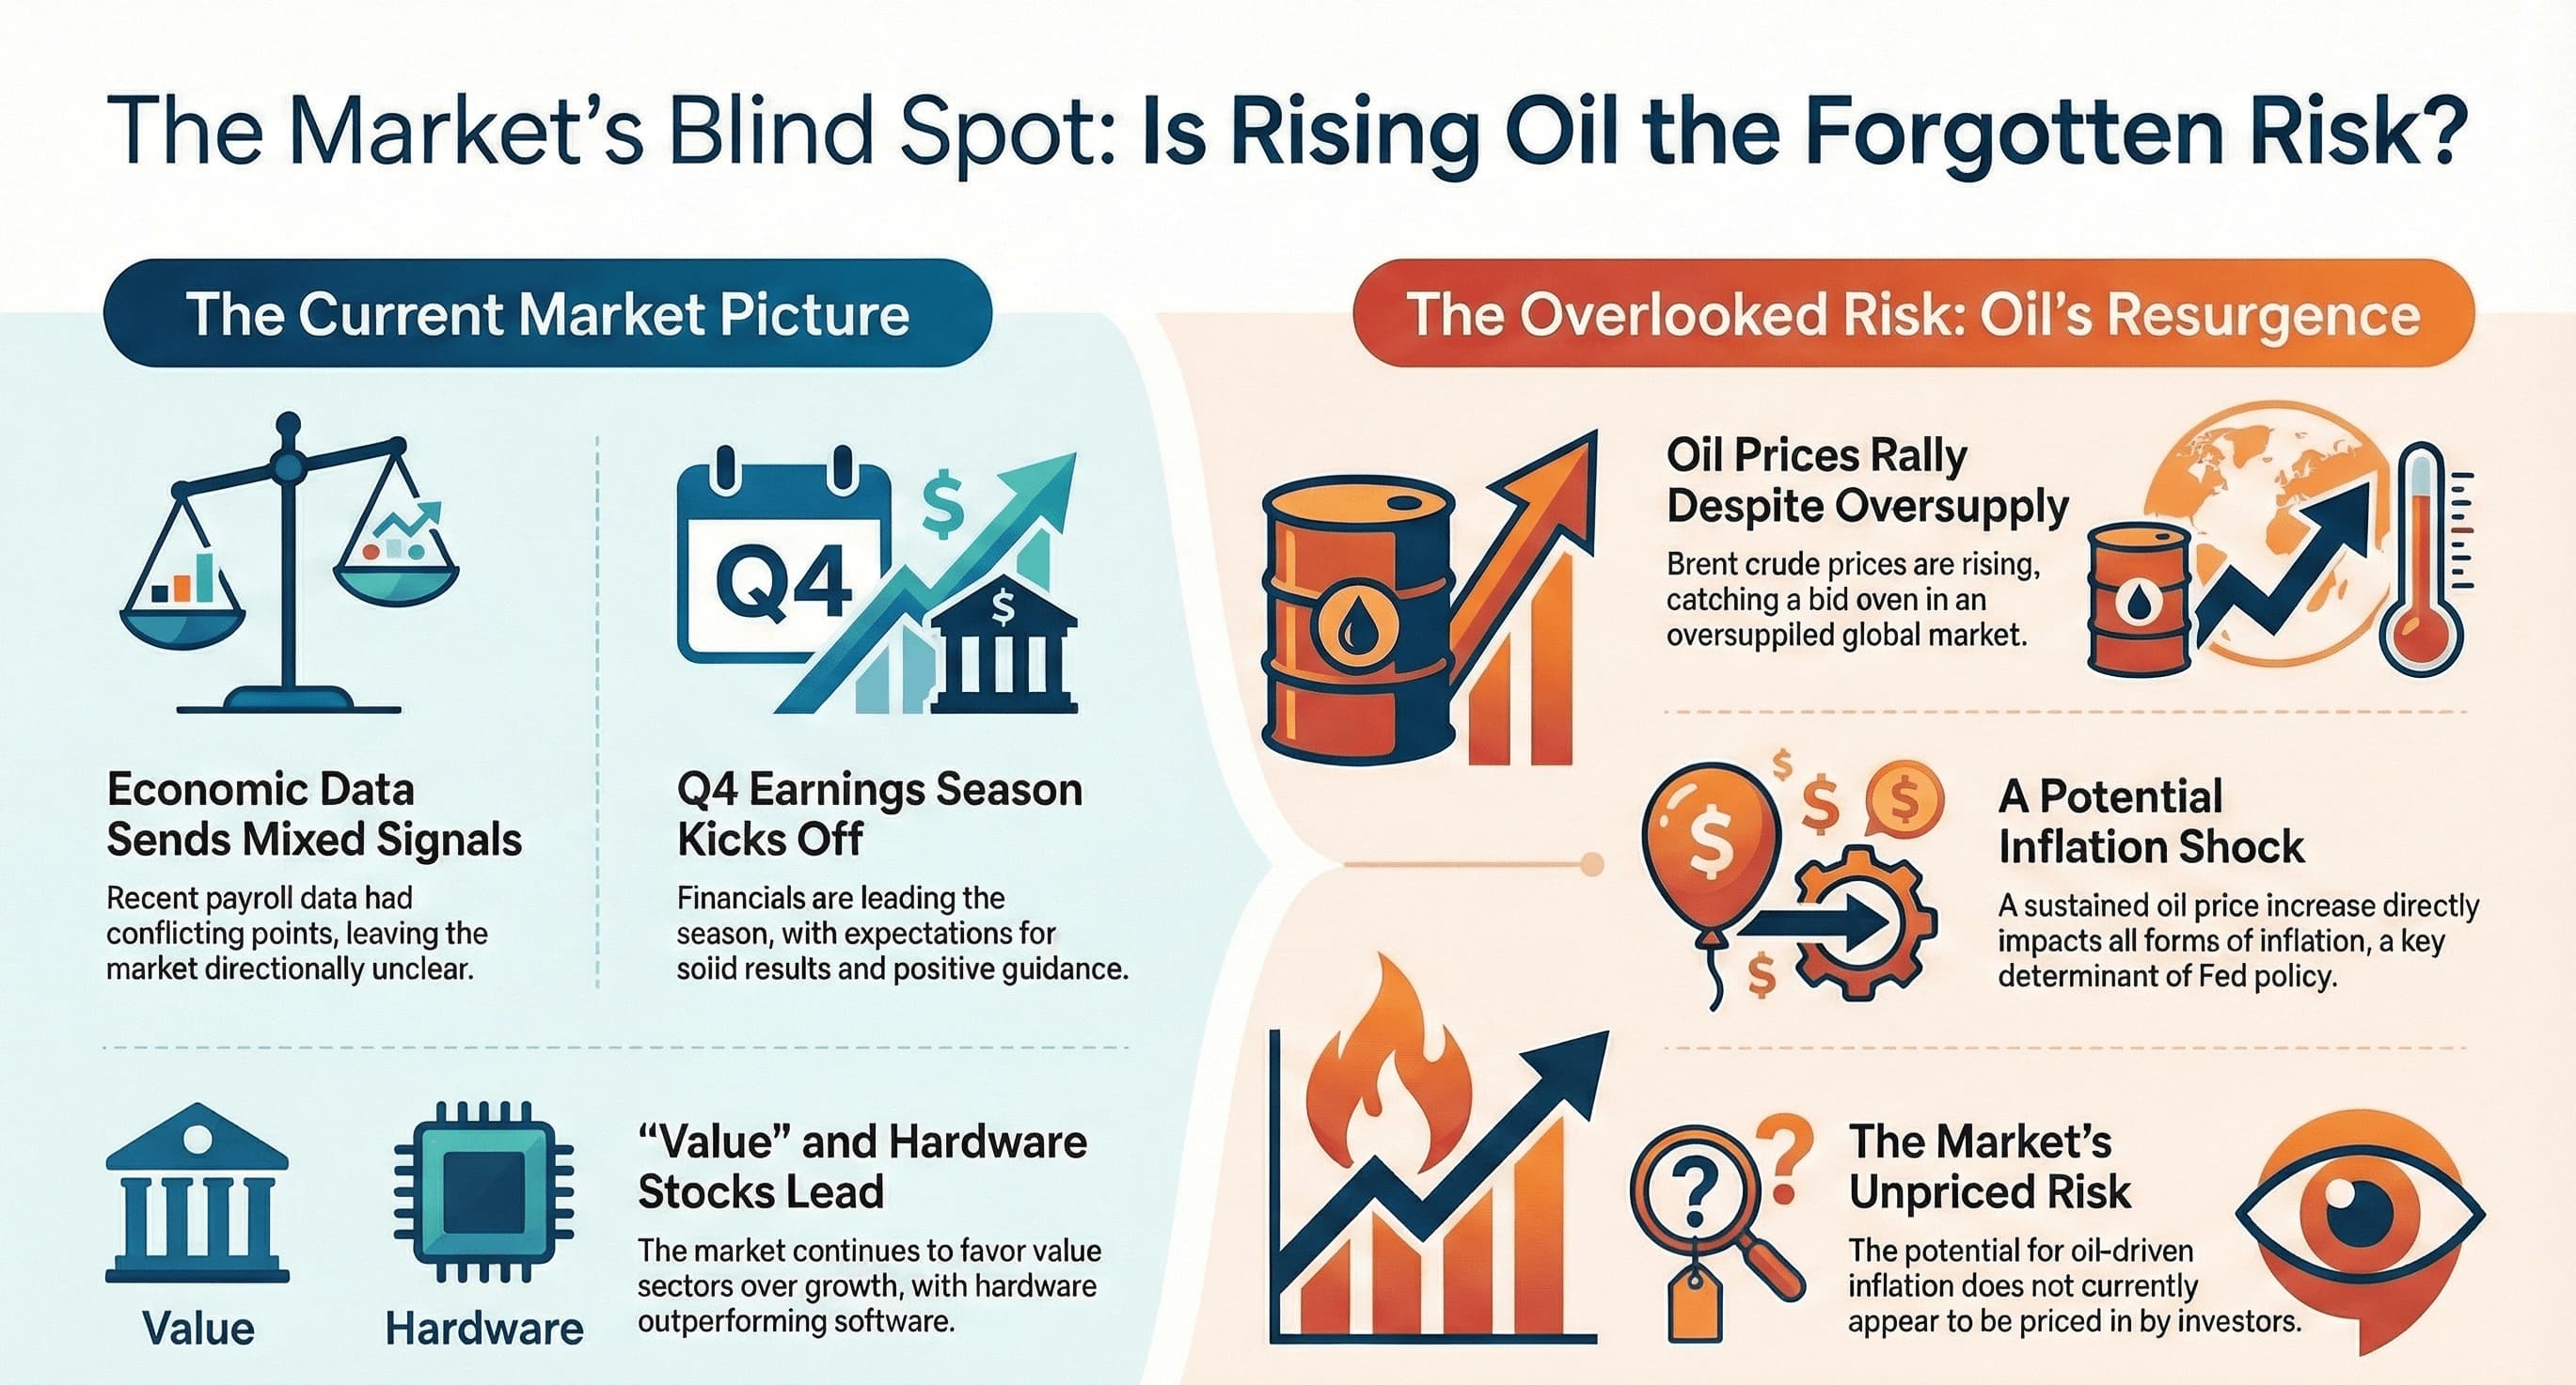
Macro data remains a mess, both in terms of data quality and importantly directionally. The much-watched payrolls last week had everything for everyone – weaker payrolls for the rate cut aficionados and lower unemployment rate for the inflation hawks. Dec inflation data (13 Jan, Tue) should be distortion free with consensus expecting a steady print (2.7% core CPI, unchanged). Futures suggest a FED on hold end-Jan.
Even as most commodities, ranging from metals to gold/silver, have strengthened, the one moribund space is oil. Venezuela does not alter the picture for now, but the world is already oversupplied with oil – YET, brent appears to be catching a bid, and in tandem, so does XLE. While this may be another false dawn, do note that sustained increase in oil prices has a directional impact on all forms of inflation, a key determinant of FED policy, and probably the one risk that does not appear priced in.
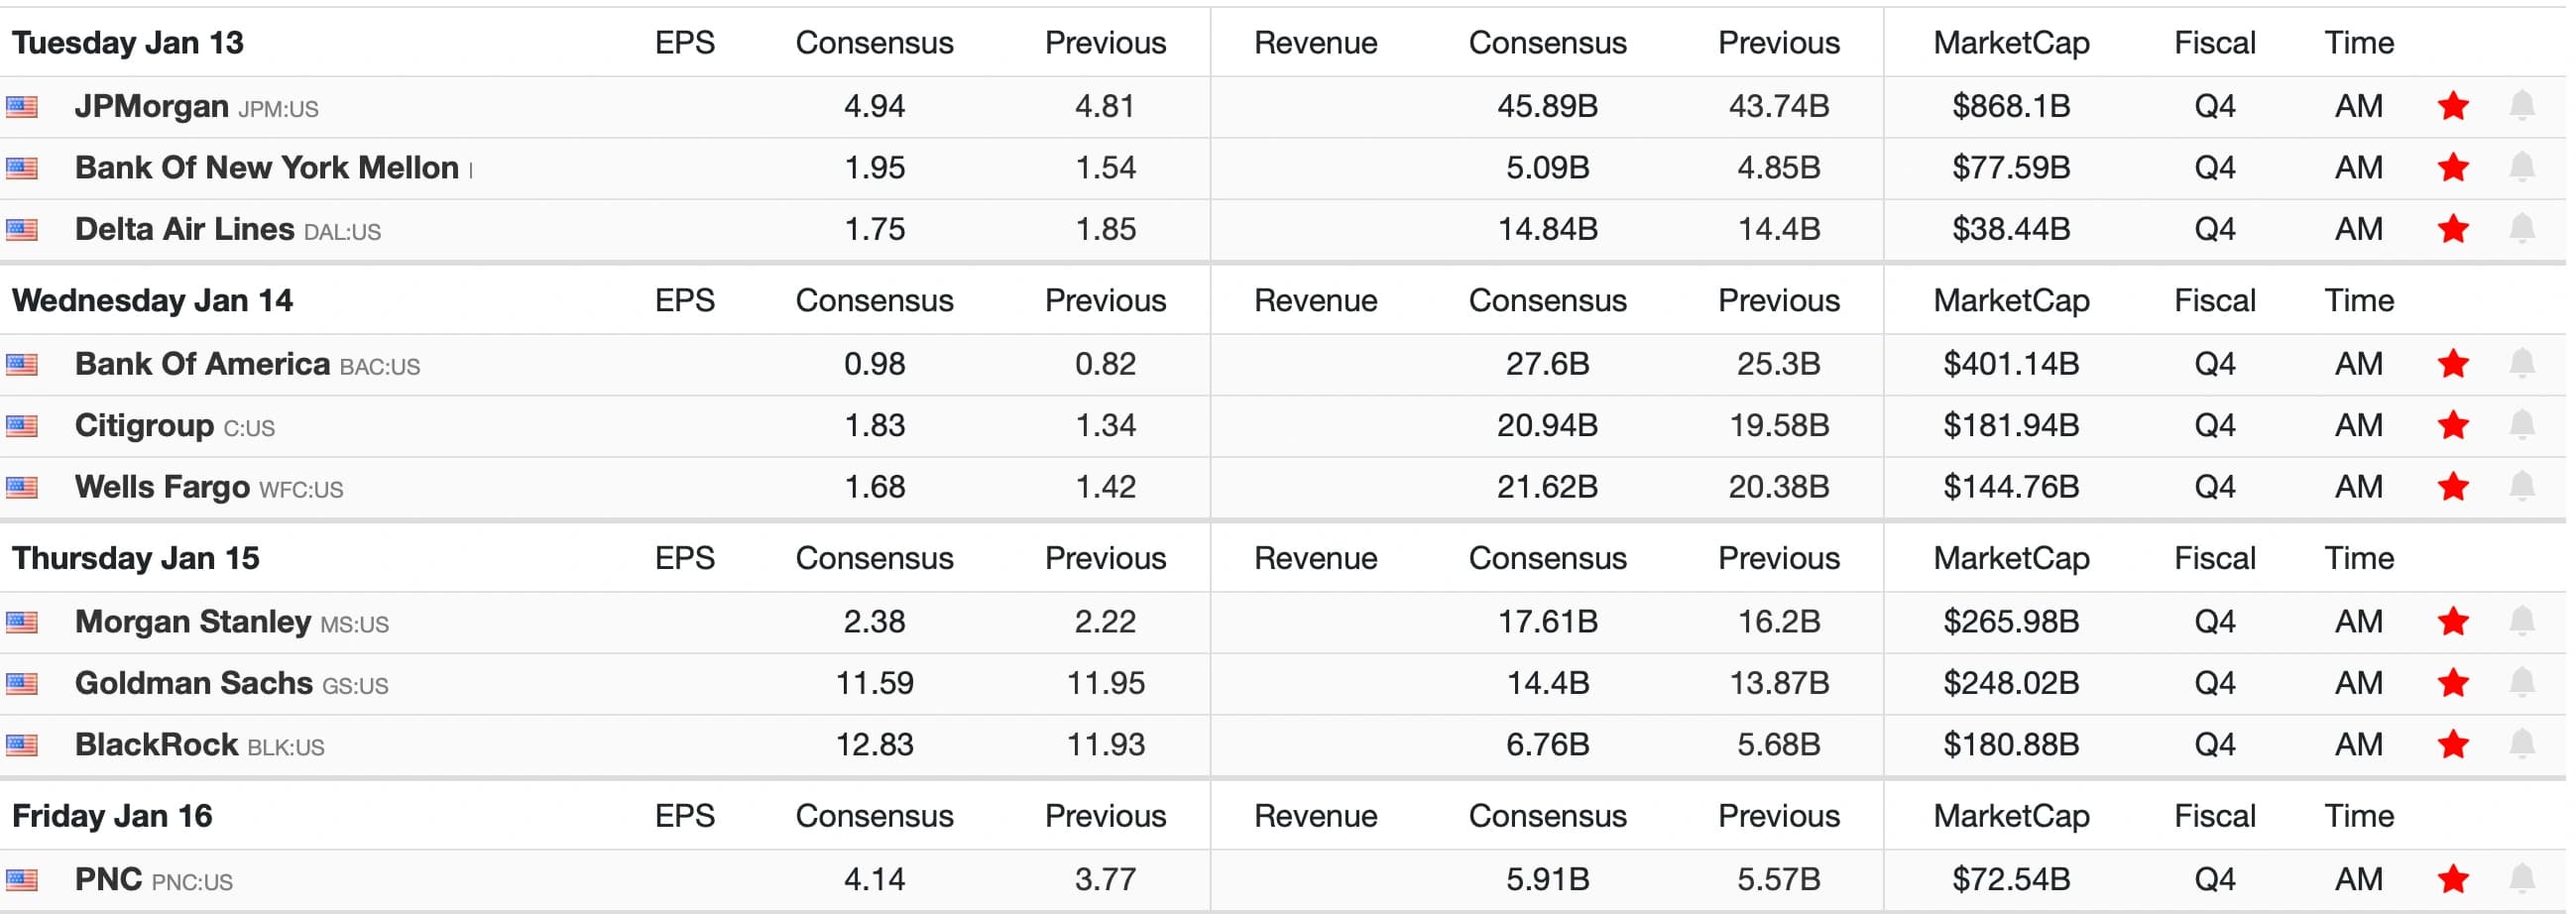
Aside from inflation data, 4Q’25 earnings season kicks off this week led by financials, in general expected to be solid with positive guidance. A possible supreme court ruling on tariffs is another variable that can shake up volatility. Meantime, “value” continues to outperform “growth” and within growth sectors, hardware names lead software laggards.
Focus on Oil
Up c7% from mid-Dec lows and c5% from lows last week, brent appears to be catching a bid despite an over-supplied market.
In tandem, XLE has delivered a 500bp outperformance vs. the broad market since late Dec’25.
While the prognosis on oil remains lukewarm, and the recent rally could well be another false dawn, it bears watching given inflationary implications.
XLE vs. SPY and Brent – Directionally Aligned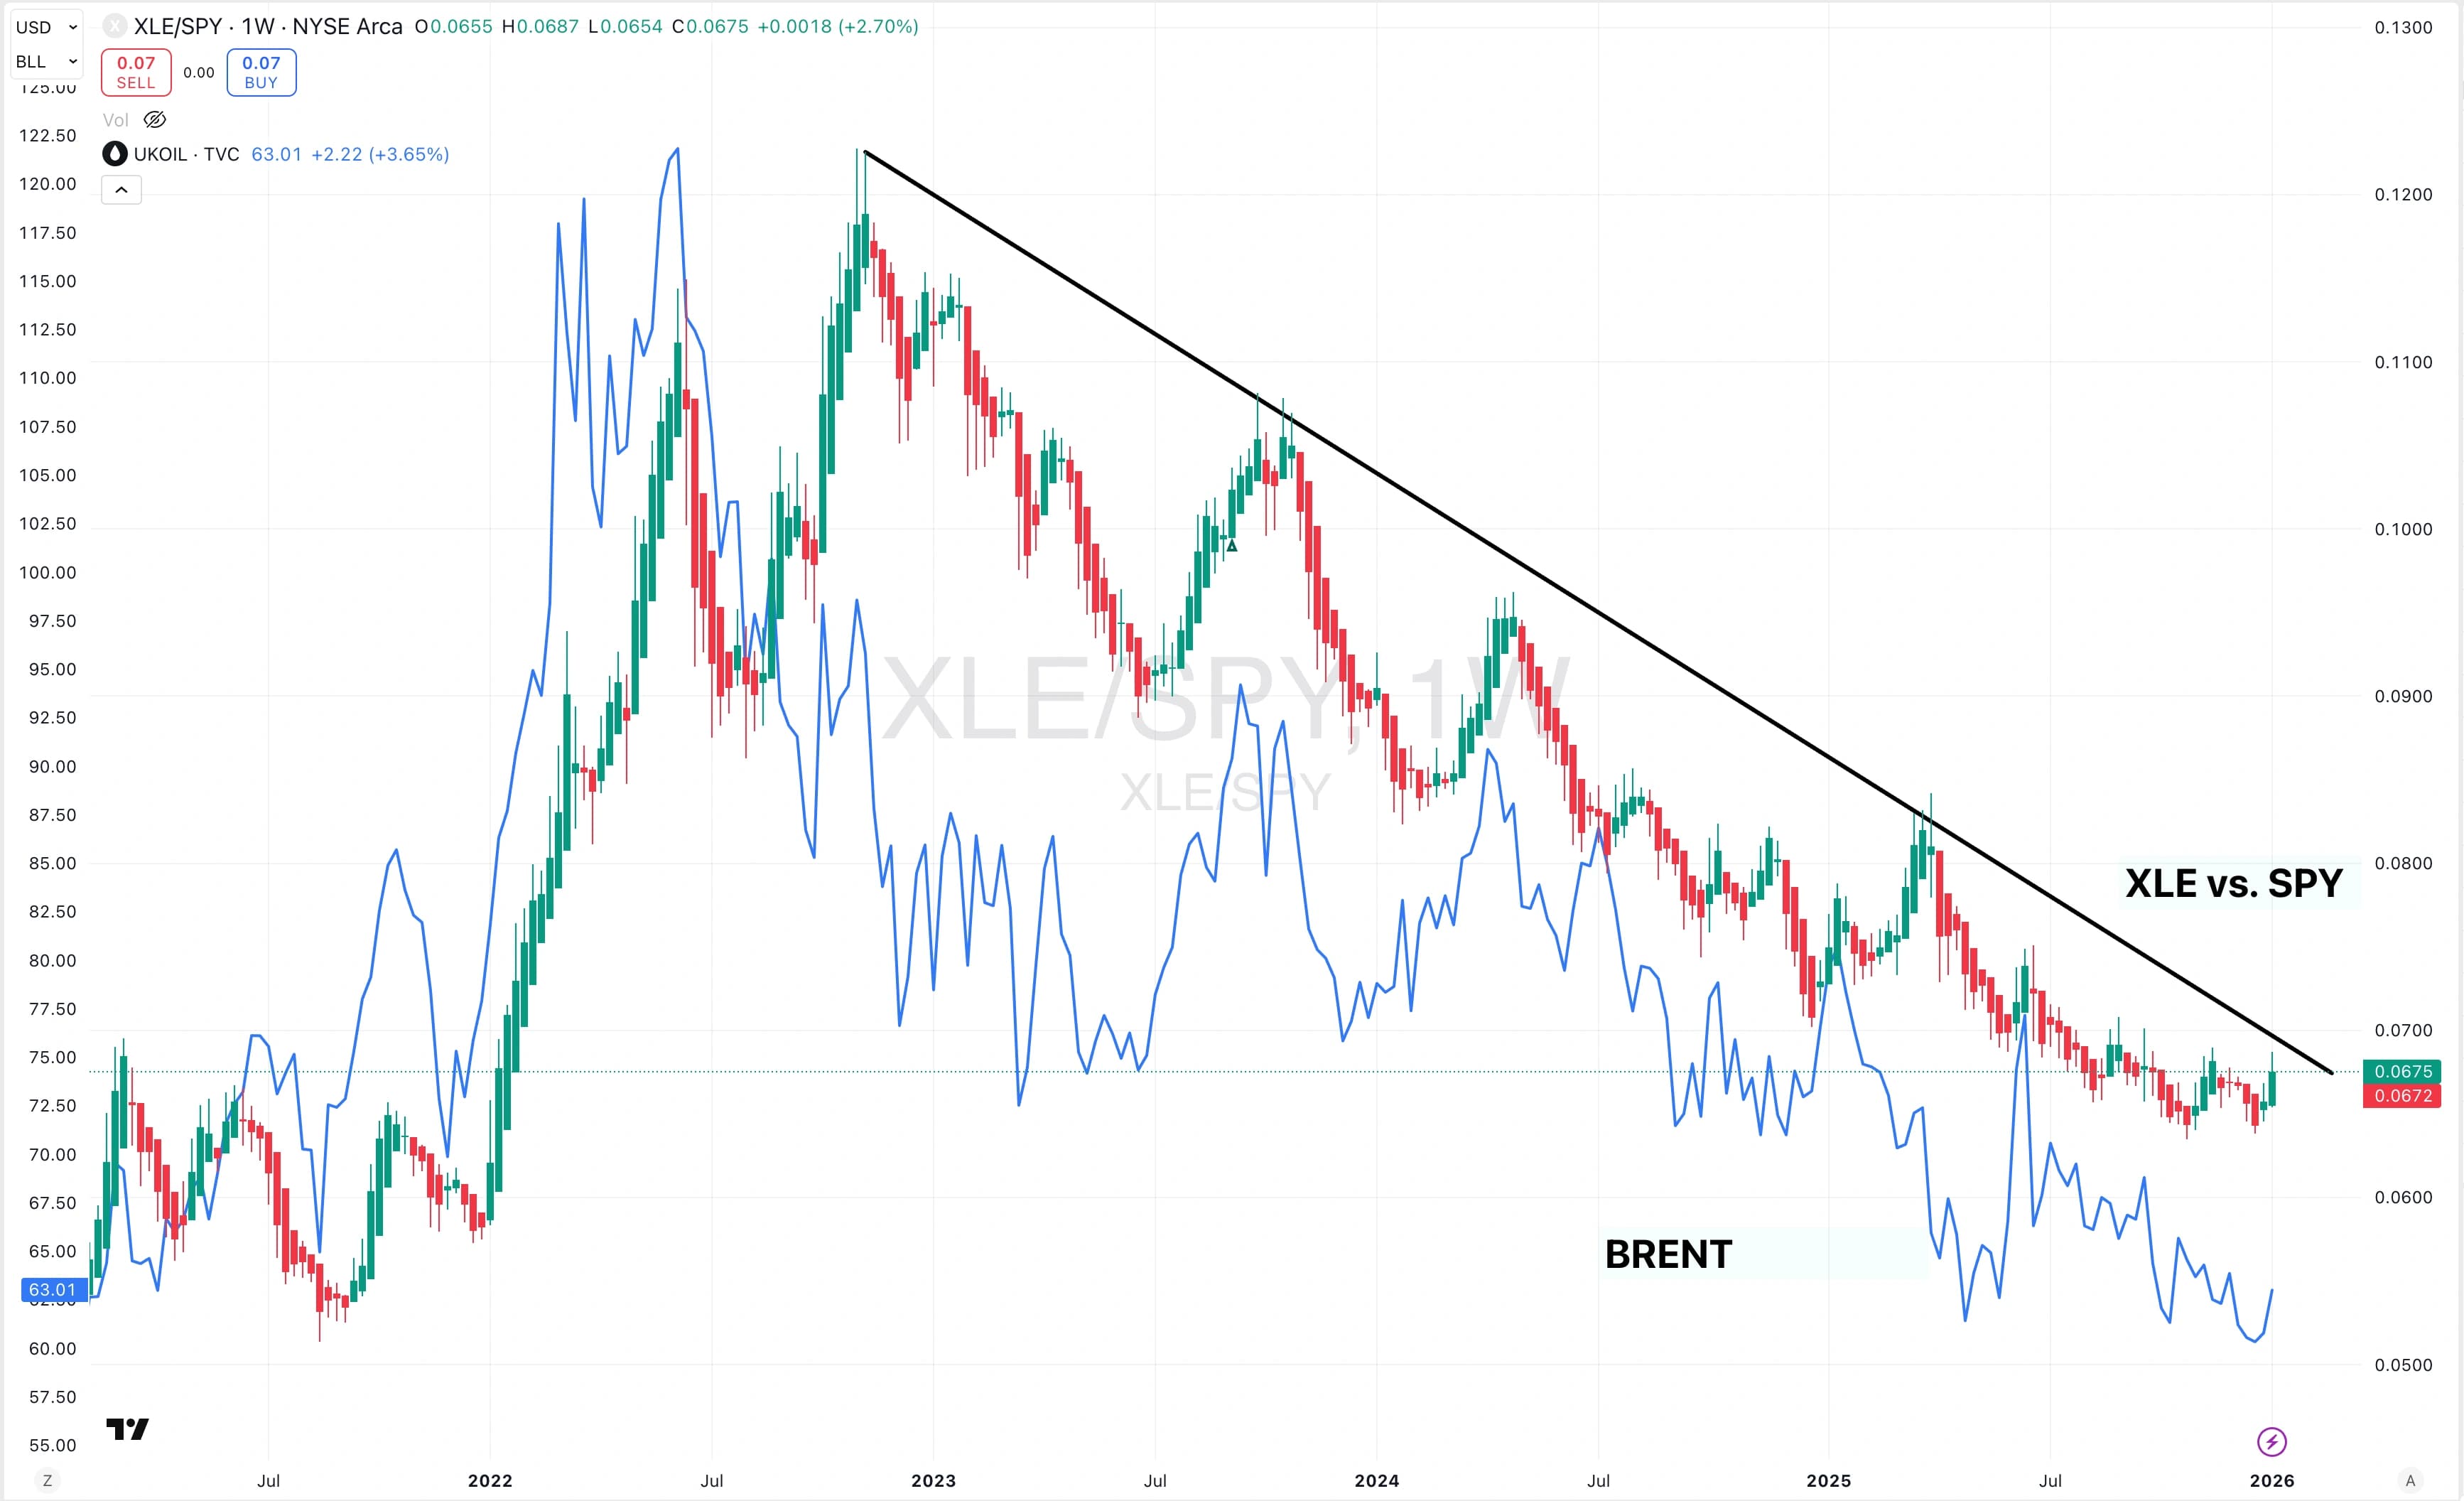
Source: TradingView
Macro Data and the FED
Up c7% from mid-Dec lows and c5% from lows last week, brent appears to be catching a bid despite
Macro focus this week will be on Tuesday’s inflation print. While the Nov’25 data was likely distorted by the government shutdown, Dec’25 data should be distortion free. Consensus expects a steady pace, unchanged from the previous month.
Last week’s jobs data had something for everyone – weaker payrolls were in contrast to lower unemployment, higher quits and faster than expected wage growth.
With continuing strength in the economy, even if softening at the margin, the case for an aggressive monetary easing remains elusive, as also reflected in a 95% probability of a FED on hold end-Jan.
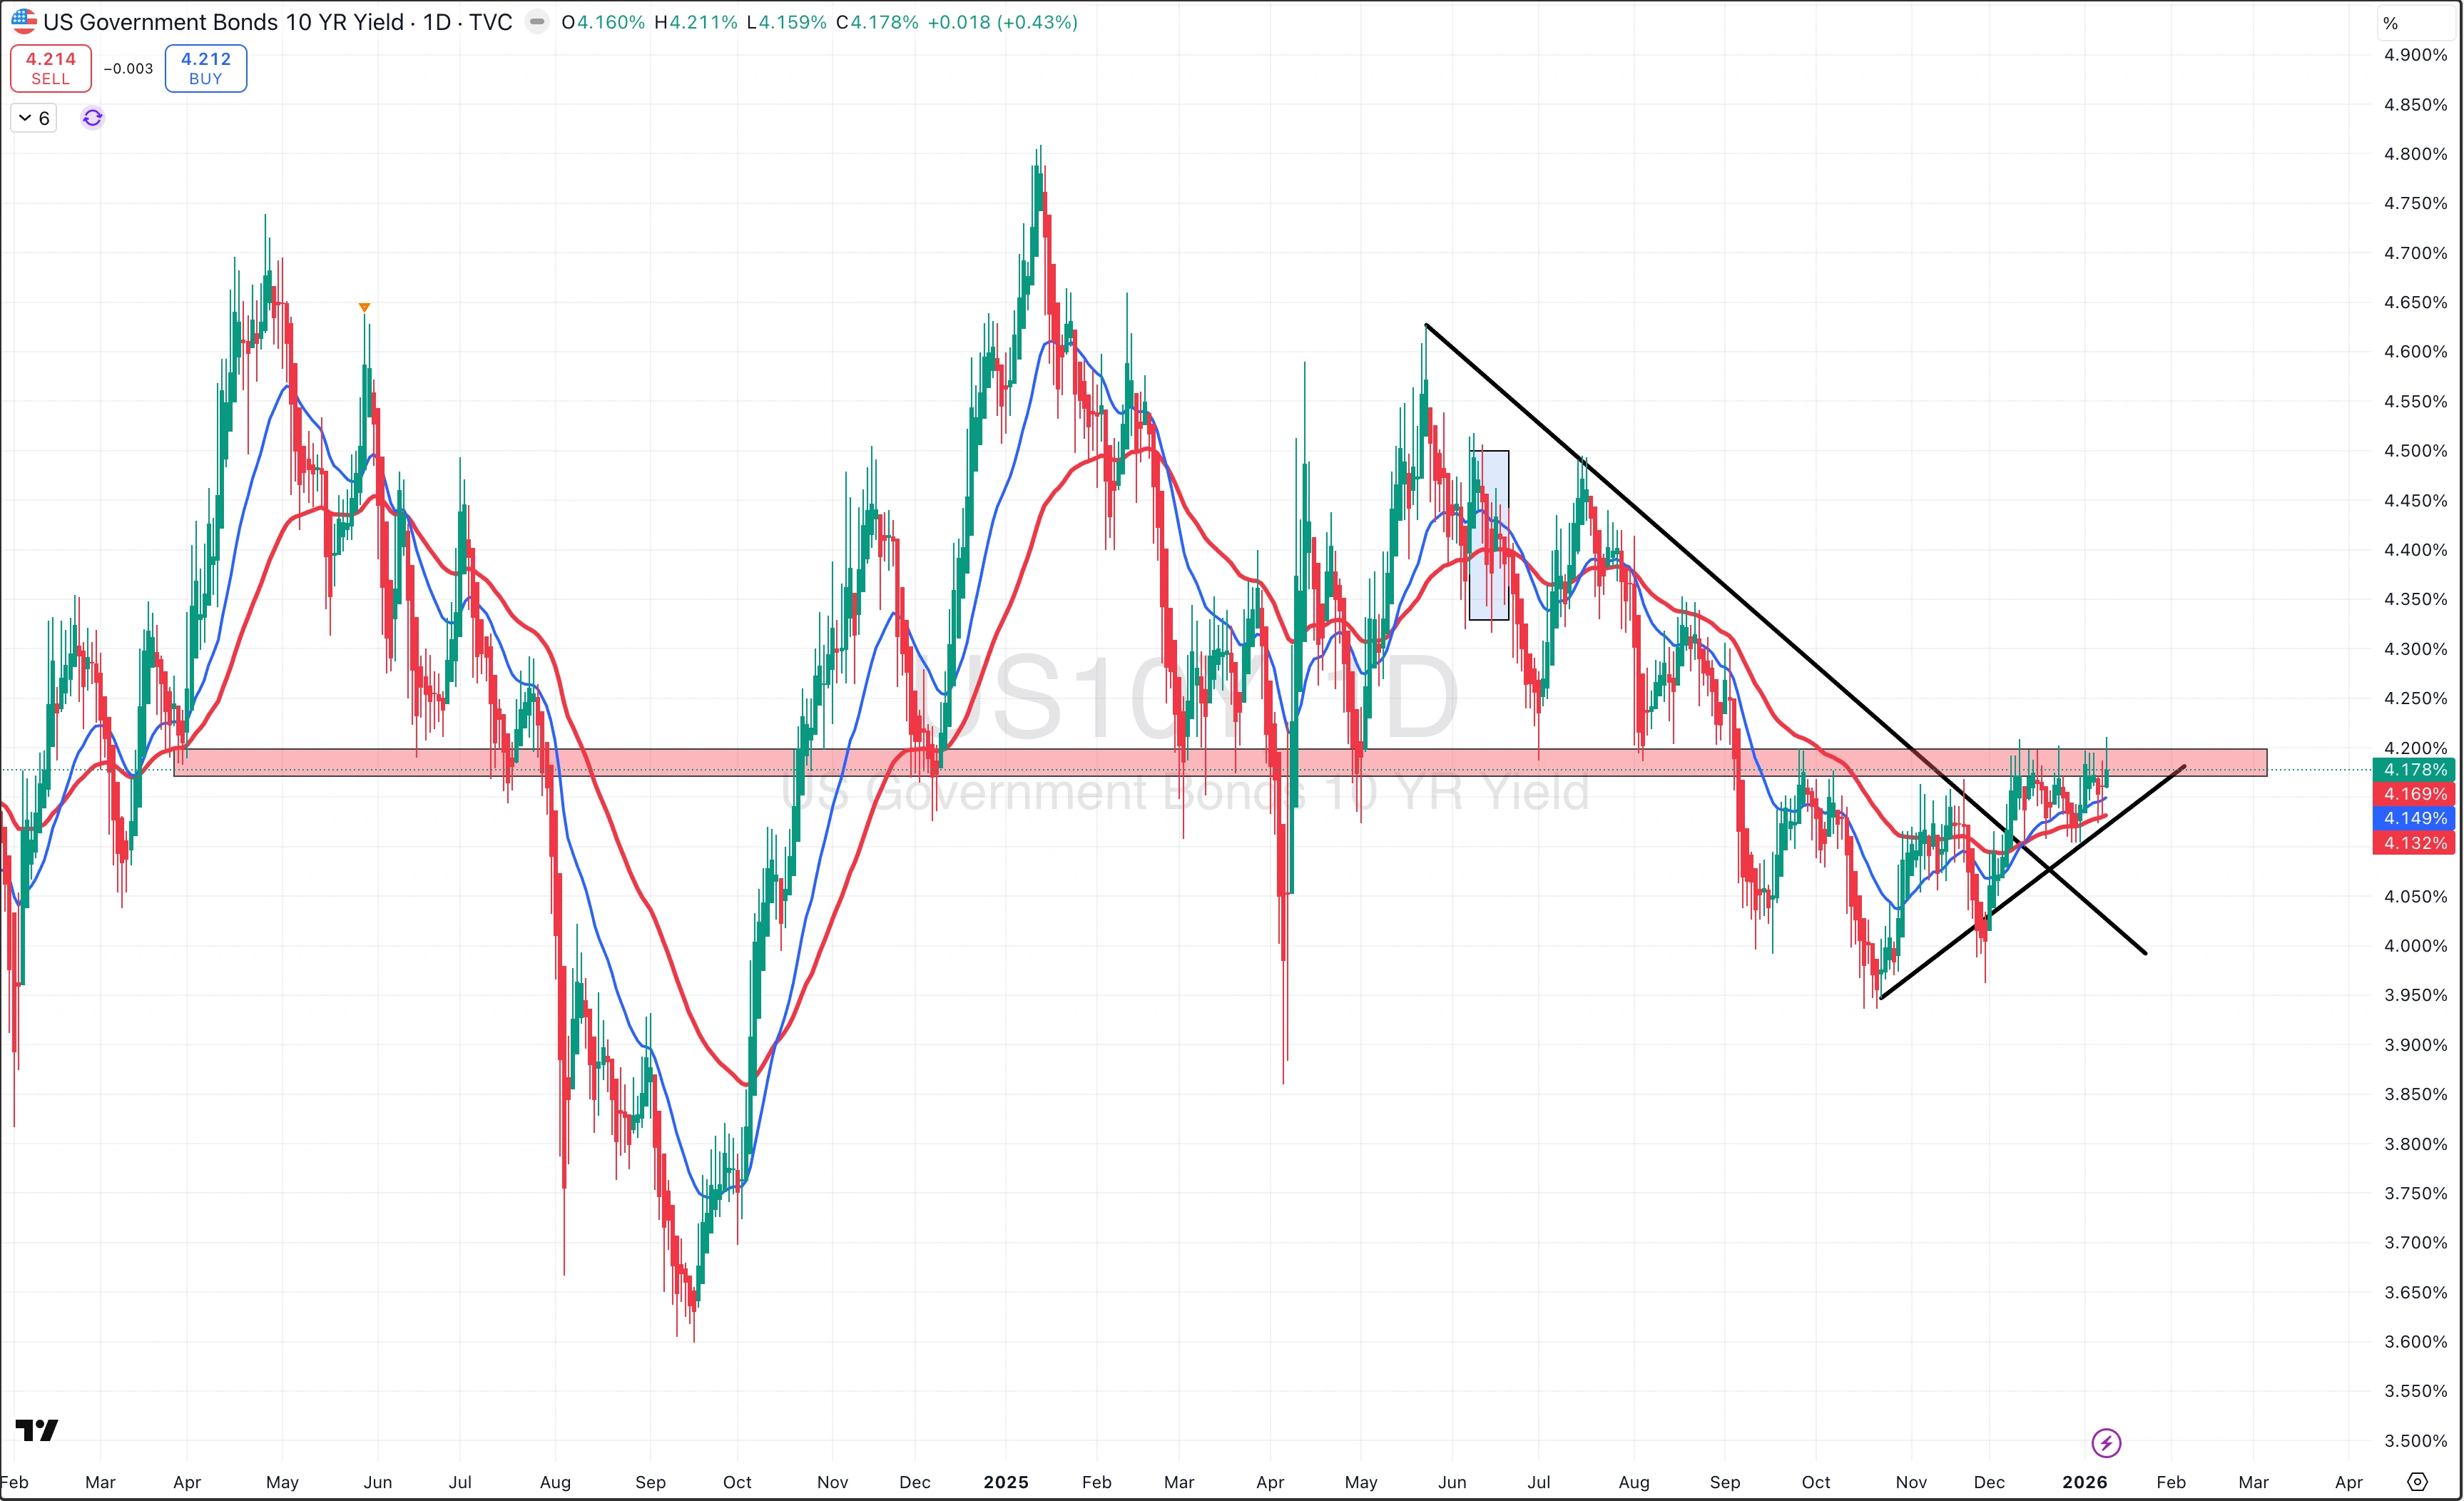
Meantime, treasury yields have remained firm, now testing a key 4.2% area.
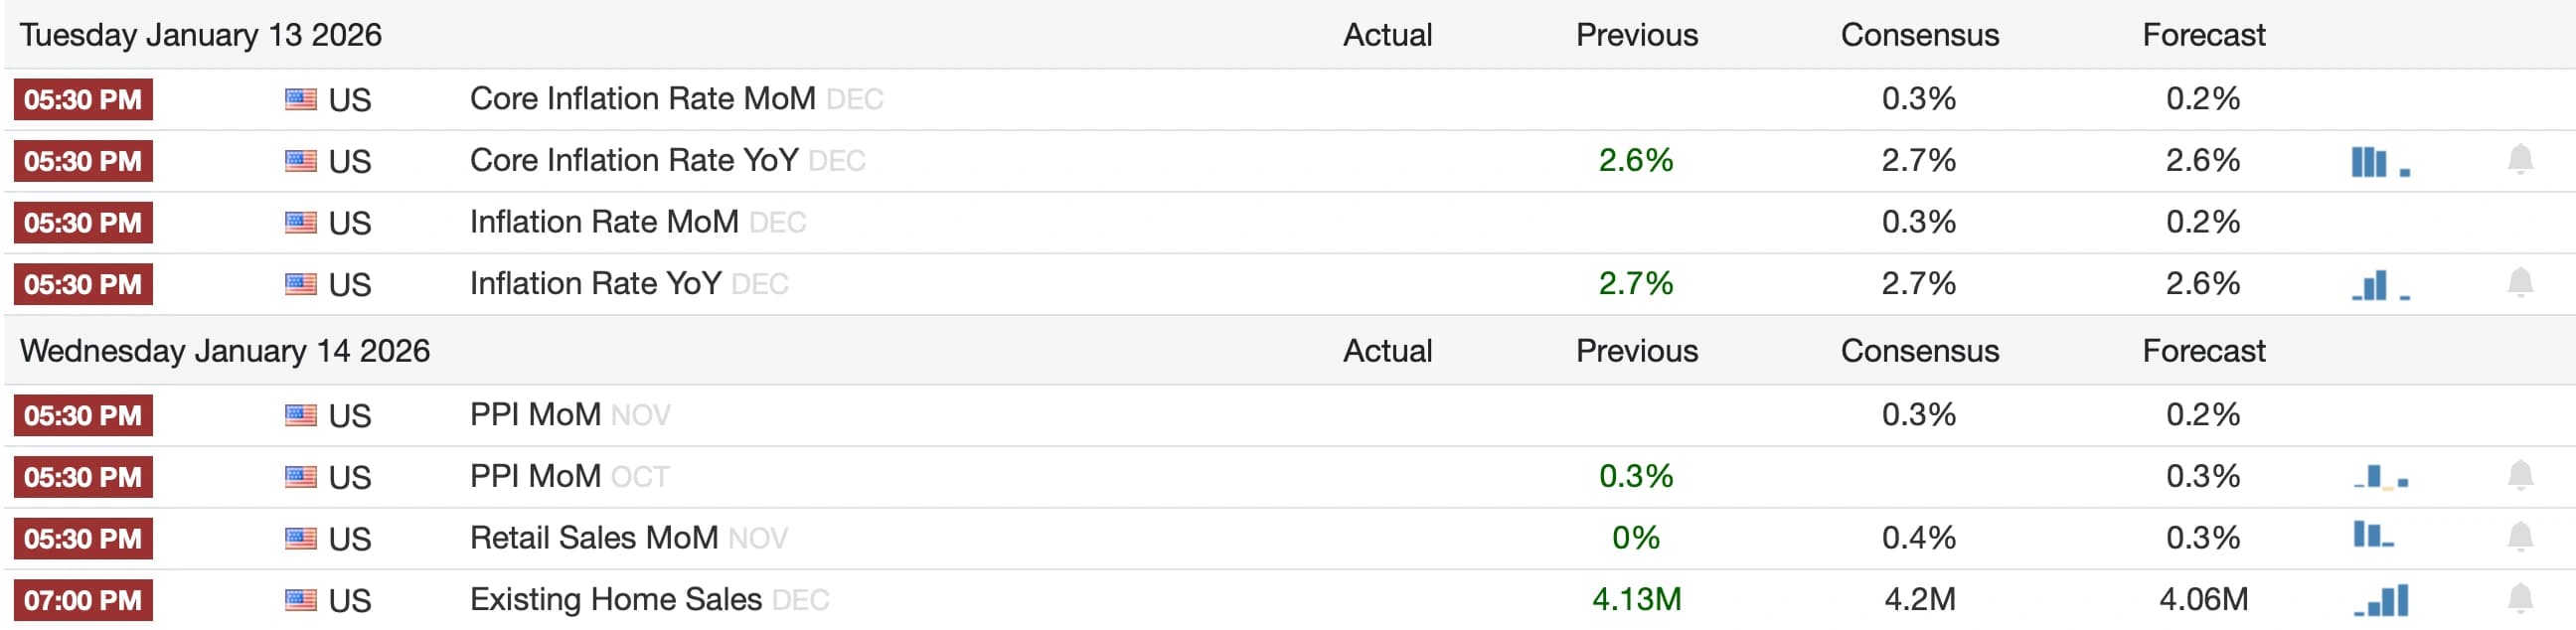
Source: Trading Economics
FED Funds Futures Price in NO Rate Cuts in Jan’26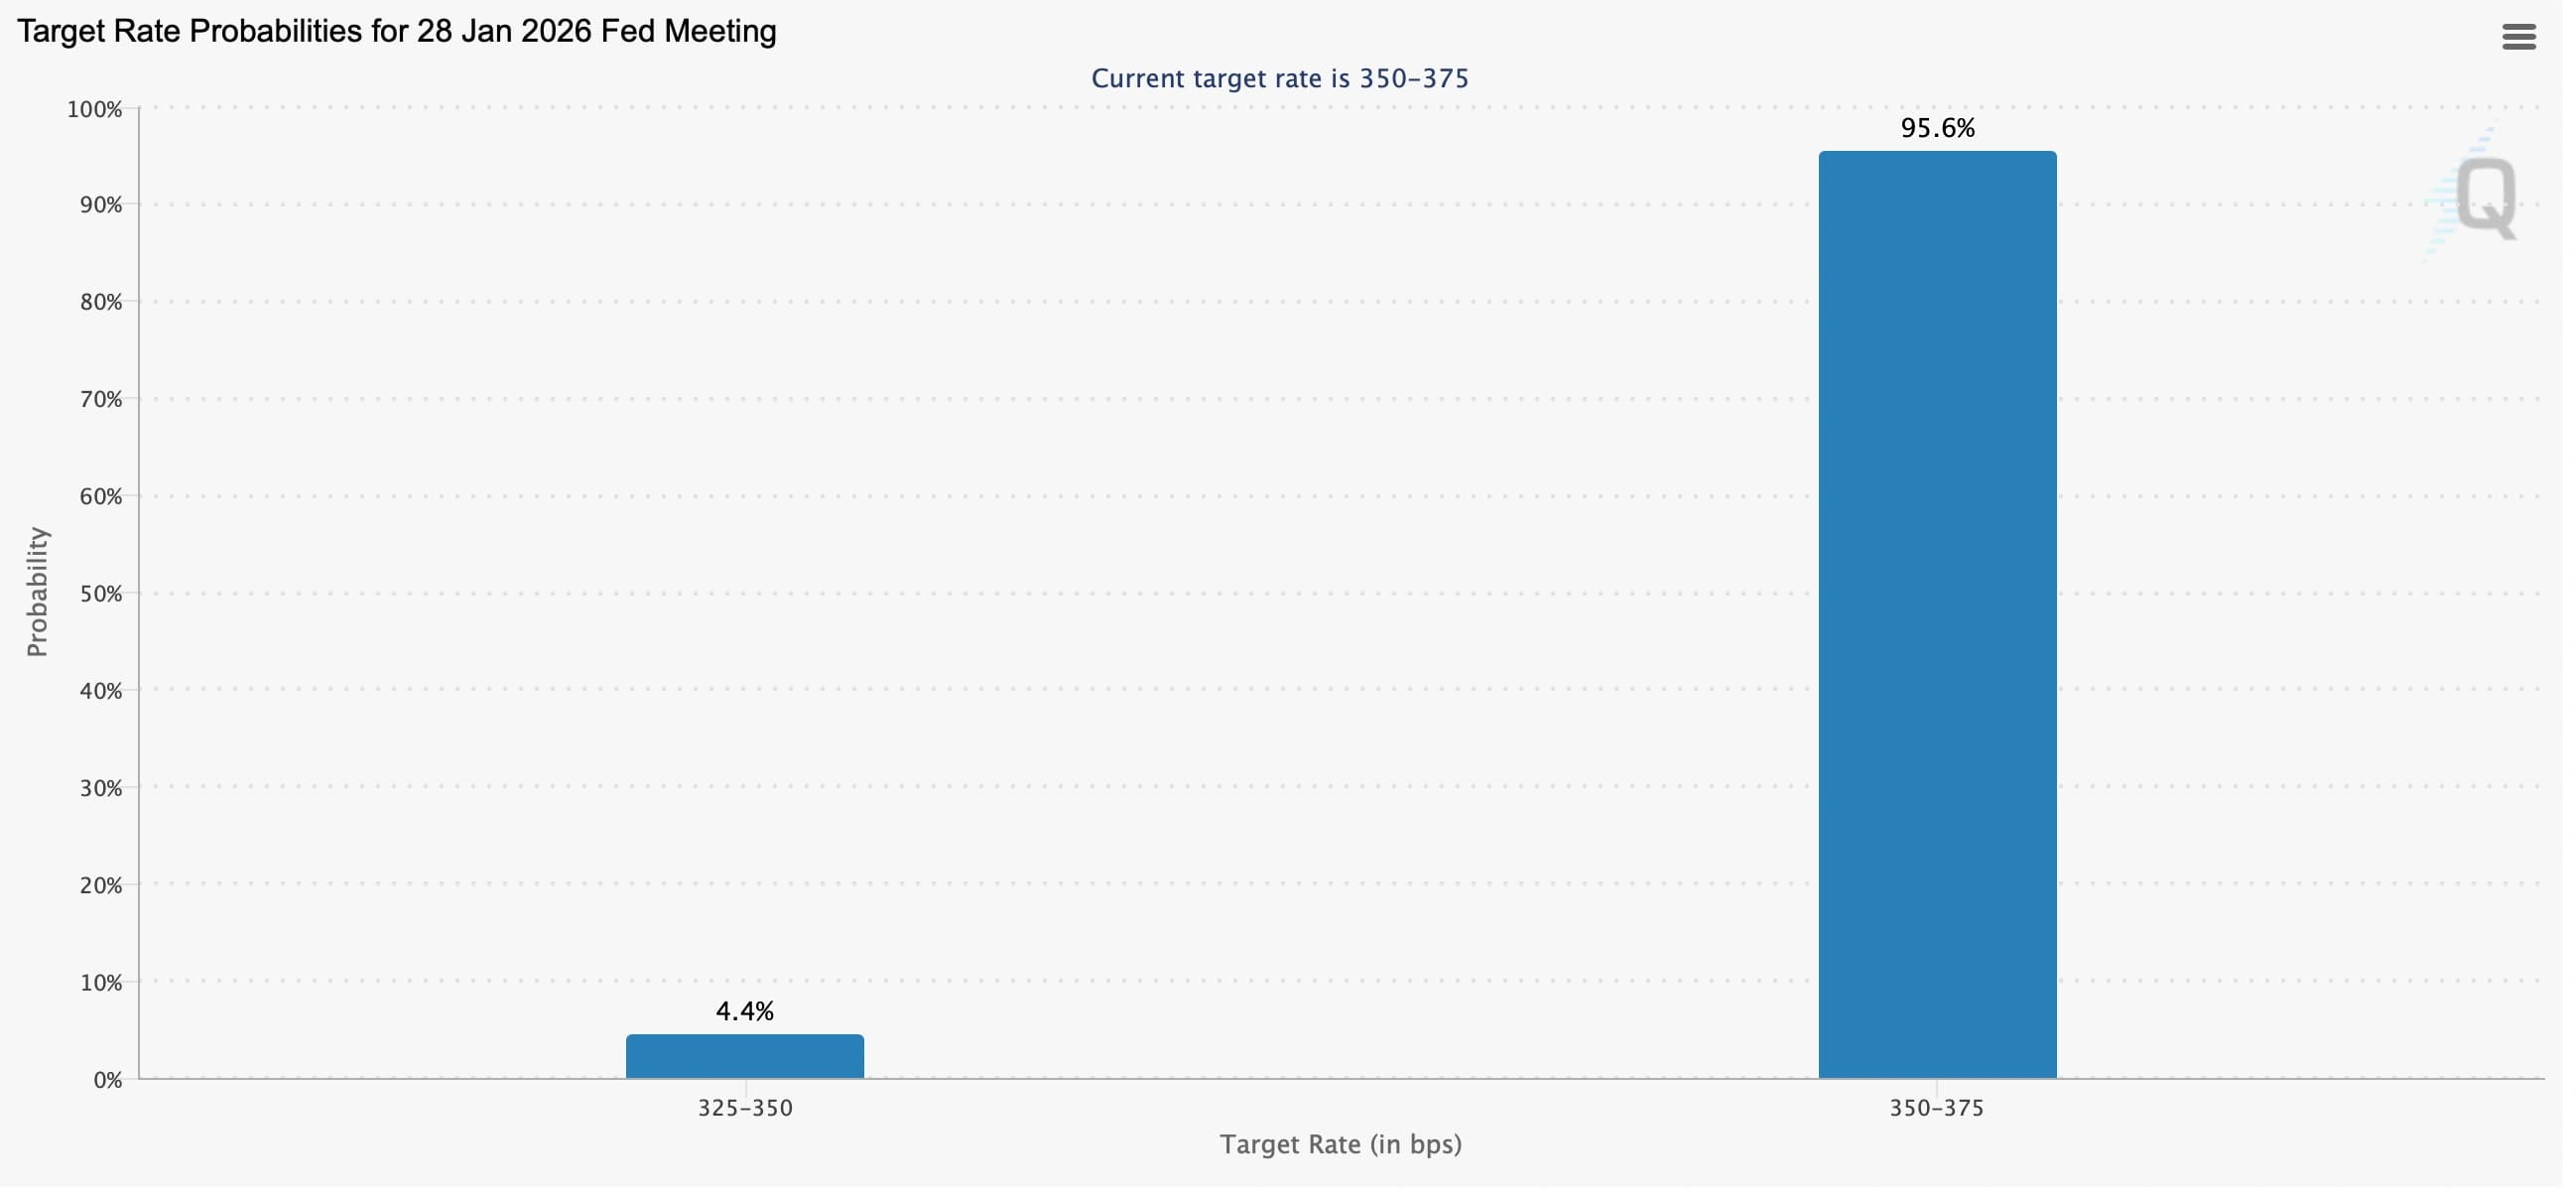
Source: CME
Treasury Yields, Testing 4.2% Area Resistance
Source: TradingView
Market Views, All Eyes on Earnings
4Q’25 earnings season kicks off this week, led by financials. While delivery is expected to remain solid following a pick-up in deal activity, guidance is also expected to be robust – more liberal regulation and a steeper yield curve potentially helping ROEs and revenues respectively.
Sentiment remains mostly neutral, “growth” sectors continue to struggle relative to “value”sectors. A clear pattern of the market favoring hardware names remains in place.
Earnings Season Kicks off Led by Financials
Source: Trading Economics
Sentiment Remains Neutral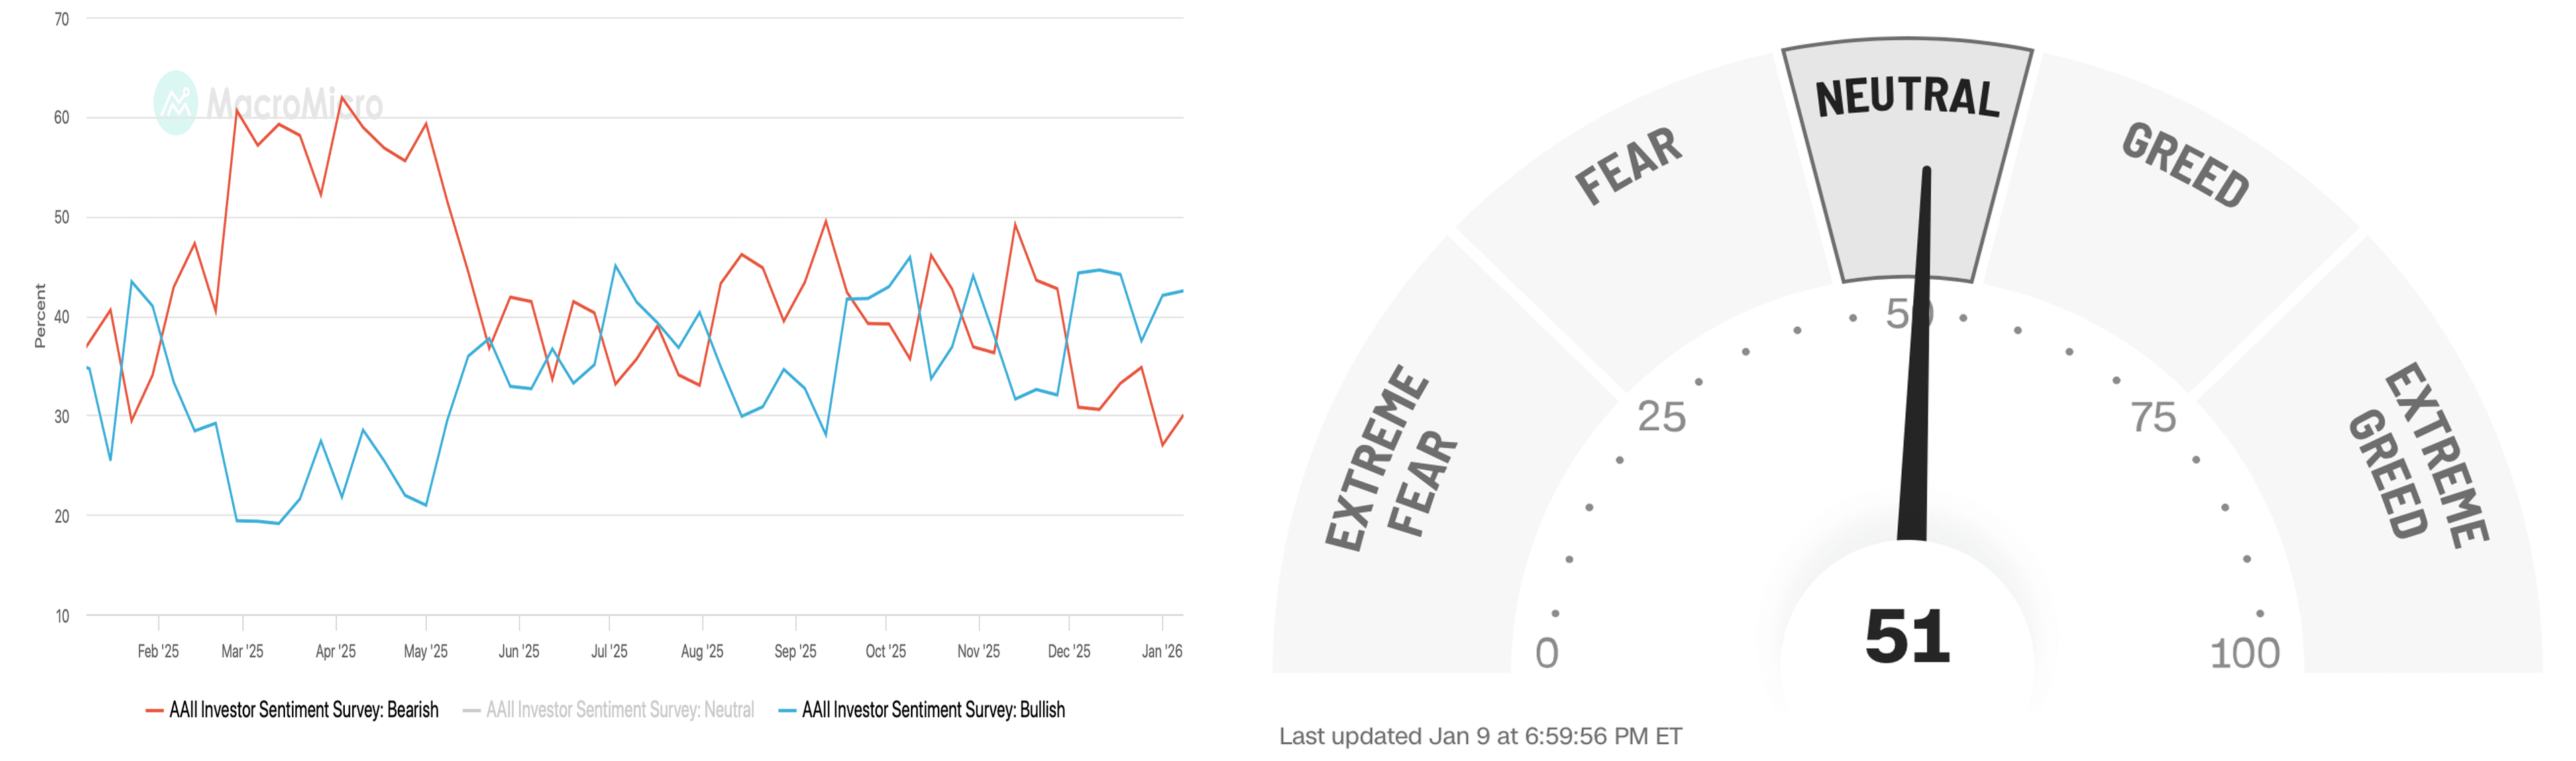
Source: MacroMicro,CNN
Hardware Continues to Lead Software
Source: TradingView








