
Investment Insights
Equity Insights - SMCI - Storm Clouds Increase Uncertainty. Protection Possibilities
Sunil Garg Managing Director, Chief Investment Officer Drishtant Chakraberty Senior Associate, Investment Consulting, Lighthouse Canton
Table of Contents
All investments carry risk, for more important information please read this disclaimer.
SMCI, a key beneficiary of the Gen AI / Datacenter boom, has retrenched substantially following weaker margins in the fourth quarter of FY24. This has now been further compounded by not just an activist investor (Hindenburg) alleging accounting irregularities, but also by the company delaying its 10-K filing with limited information leading to this delay. While the Hindenburg report has its own challenges, we are far more concerned with the 10-K delay as a major red flag. Unfortunately, with limited information, it’s difficult to assess the severity of this event.
While we continue to have conviction on SMCI’s business fundamentals and see it as a key beneficiary of the massive ongoing spend on AI related datacenter build-outs, the dilemma for investors is the tradeoff between expensive hedges (due to elevated uncertainty) to protect downside, or to ride the uncertainty on what remains a strong business which is now trading at reasonably attractive valuations.
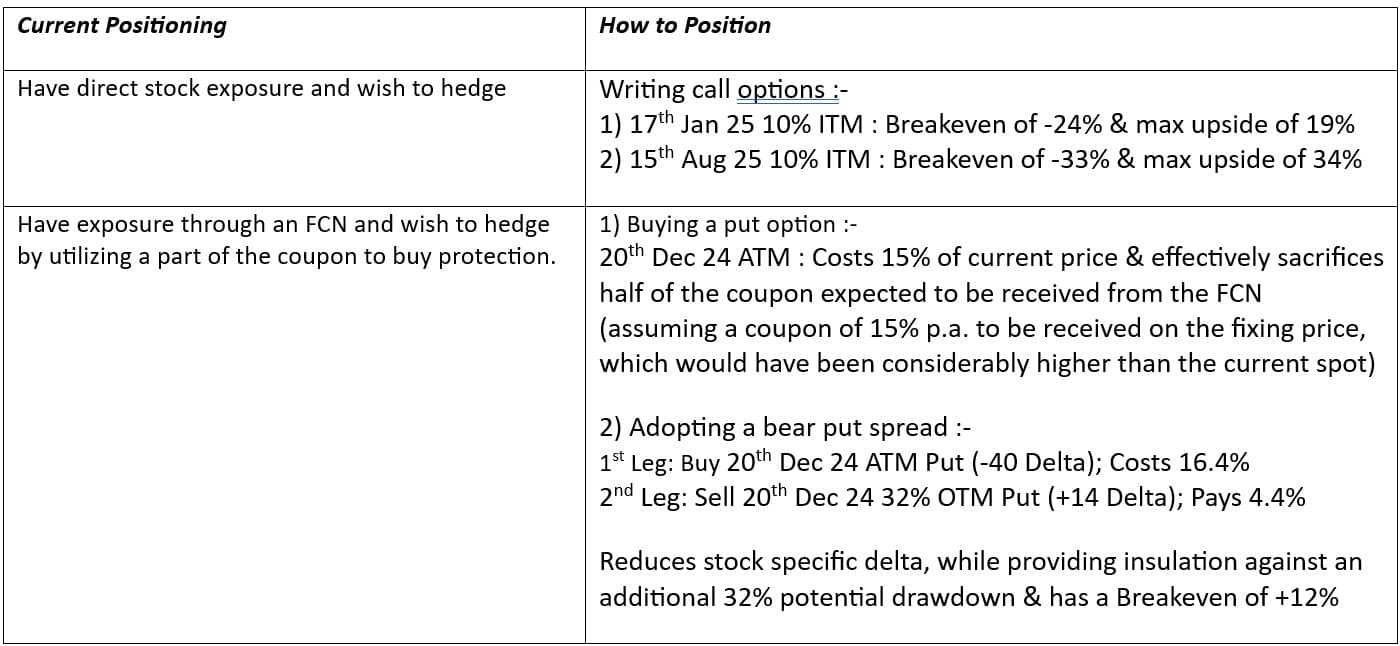
How to Position :-
While we are not overly concerned about the allegations levelled by Hindenburg (refer to our take on the Hindenburg report below), we are definitely uncomfortable with this sudden announcement of a delayed 10-K filing, which tends to be a red flag with respect to the company’s internal controls on financial reporting.
The company has not yet provided the exact reason that has caused this delay and just mentions the management’s need for additional time to complete its assessment of the design and operating effectiveness of its internal controls over financial reporting. They also clarify that up until now they have not made any changes to the fiscal year & quarter ended June 2024 results.
The notification provided by the management is completely blank in terms of providing a clarification on what exactly prompted this review of internal controls over financial reporting. At this stage we are uncertain about whether this is merely part of some additional due diligence taken on as part of the Hindenburg report or has there been some development either internally or based on the guidance of the external auditor to review certain items of the books of account.
Following is our take on the Hindenburg report :-
Historically SMCI has been an easy target for short reports primarily due to its tainted history. In 2017 there were certain accounting deficiencies identified which resulted in aggressive revenue recognition practices and this was primarily due to the culture put in place by the then CFO who pressurized accountants and the finance Team to recognize revenues on the books closer to the quarter end. This lack of internal controls and improper reporting ended up in the company getting delisted from the bourses temporarily till the time that the management managed to sort out these issues. The company was then re-listed on the bourses after adequate internal controls were put in place and the CFO was changed.
The above has been extrapolated to today, without much evidence and a similar report was released in 2022 as well, where a different hedge fund was alleging wrong-doing but nothing came out of that till date. In Hindenburg’s report, they point out how there are certain accounting “red flags” but never go into any detail regarding these so called red-flags and once again allege aggressive revenue recognition practices which seems to be the go-to theme given the past wrong-doing that was identified.
The part of the report where we do see some merit was regarding the related party transactions, where there have been certain purchase of inputs and sale of finished products to companies which seem to be controlled by the brothers of CEO Charles Liang. However, one thing to note is that these are all very small pieces of the total revenue / COGS that the company reports. Therefore, while not being ideal in terms of corporate governance, this is definitely not substantial and does not point towards something that could be really meaningful in terms of the company’s overall financial operations and future potential. Additionally, we would also like to mention that these things are quite common across many family owned / promoter owned businesses and till the time that they are of a small amount, they usually tend to have little impact on the corporate governance profile of the company and the stock price.
Allegations on violation of sanctions and sale of goods to Russia – While we do not have the ability to check / verify this, we would like to say that in case these were really true the US Govt. would have come for them by now, given how strictly these sanctions were being / have been enforced. We have previously seen such allegations levelled against other companies as well such the French firm Technip Energies NV and they turned out be entirely baseless. This is yet another topping that short report writers usually like to throw in. Based on what has been reported it seems that SMCI sold products to certain distributors who were illegally selling goods / smuggling them into Russia and since then have been sanctioned. We do not see how SMCI is to blame for this in that case as they would not have been selling products to these companies once they were sanctioned.
The last bit of the report on performance issues and losing out to competition is completely baseless in our opinion. Talks about xAI not maintaining SMCI as the exclusive provider proves absolutely nothing as it is commonplace to diversify providers. Mentions of Dell getting orders from large customers of SMCI again really does not prove anything especially given that SMCI’s order book and revenue continue to grow at a robust pace. Then there is mention of how it has lower prevalence in the hyperscaler space, which was a deliberate decision on behalf of the management as the margins here are much lower when compared to what the company stands to make when selling to other customers. In fact, one of the main reasons that their gross margins were down during the latest quarter was due to them winning large deals and selling to the hyperscalers who obviously demand better prices due to their scale of purchases. There is a small mention of malfunction rate – Industry wide it is accepted that SMCI servers deliver the best performance with a very low malfunction rate which is what has allowed it to compete with GIANTS like HP & Dell. If their products were really as bad as Hindenburg has portrayed them to be, how and why would the company be guiding to sell 28 Billion $ in revenue this fiscal year.








