
Investment Insights
Stale Tacos | CIO Insights
Sunil Garg Managing Director, Chief Investment Officer
The short-lived and somewhat muted reaction to the latest Trump tariff tirade, following sabre rattling on Greenland, suggests a staleness in this playbook, as also highlighted in a recent Financial Times article. The probability of geopolitical accidents is however rising. TACO, short form for "Trump Always Chickens Out", coined by another FT journalist, seems to be losing efficacy - in fact, a "do nothing and hold on" strategy in markets, specifically equities, would have been optimal with 20/20 hindsight.
The short-lived impact of geopolitical developments supports the view of NOT being perturbed by political shenanigans. Rather, focus on the macro, earnings, valuations, and price action - precisely what our proprietary four pillars model seeks to do.
What is that saying now? The macro looks acceptable aside from lingering and real concerns on inflation. While long-term growth will almost certainly be challenged - both for the economy and equities, the more immediate catalysts can only come from earnings, which for now appear robust, even if concentrated. Price action remains in search of direction but continues grinding higher. In summary: ignore politics, focus on inflation and earnings, and watch price action - secular trends are unlikely, volatility will probably be the norm.
Technical Overview
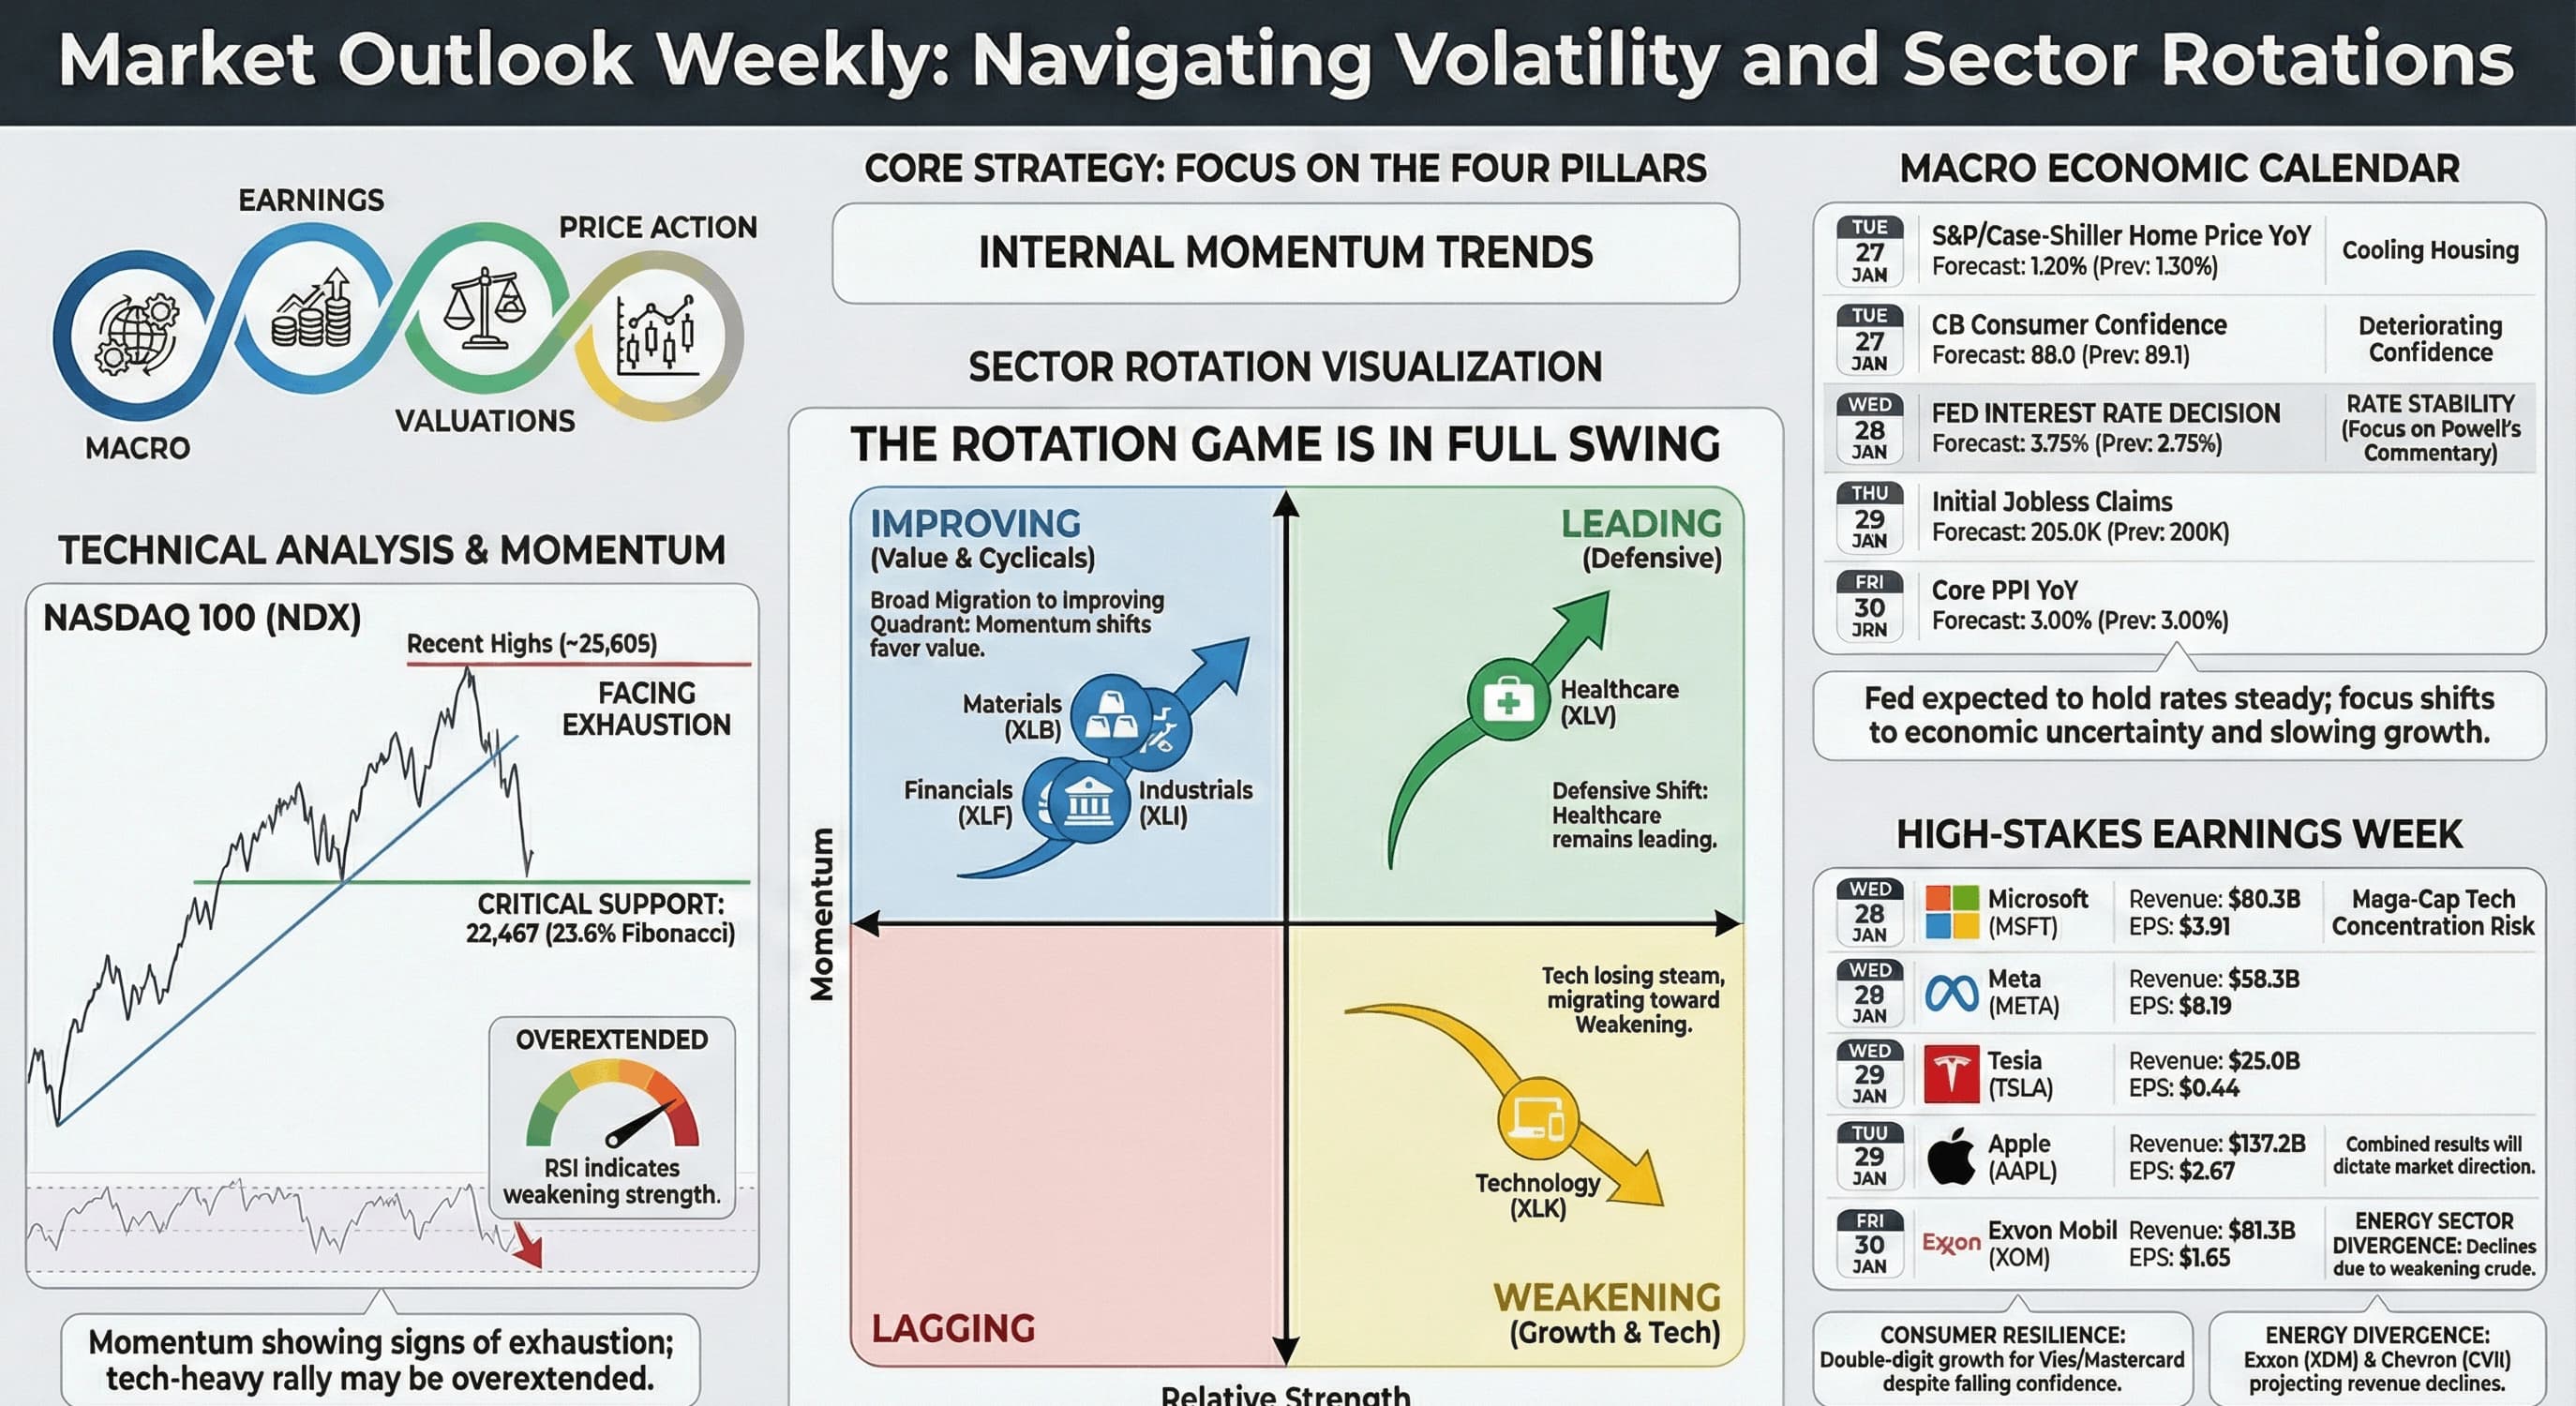
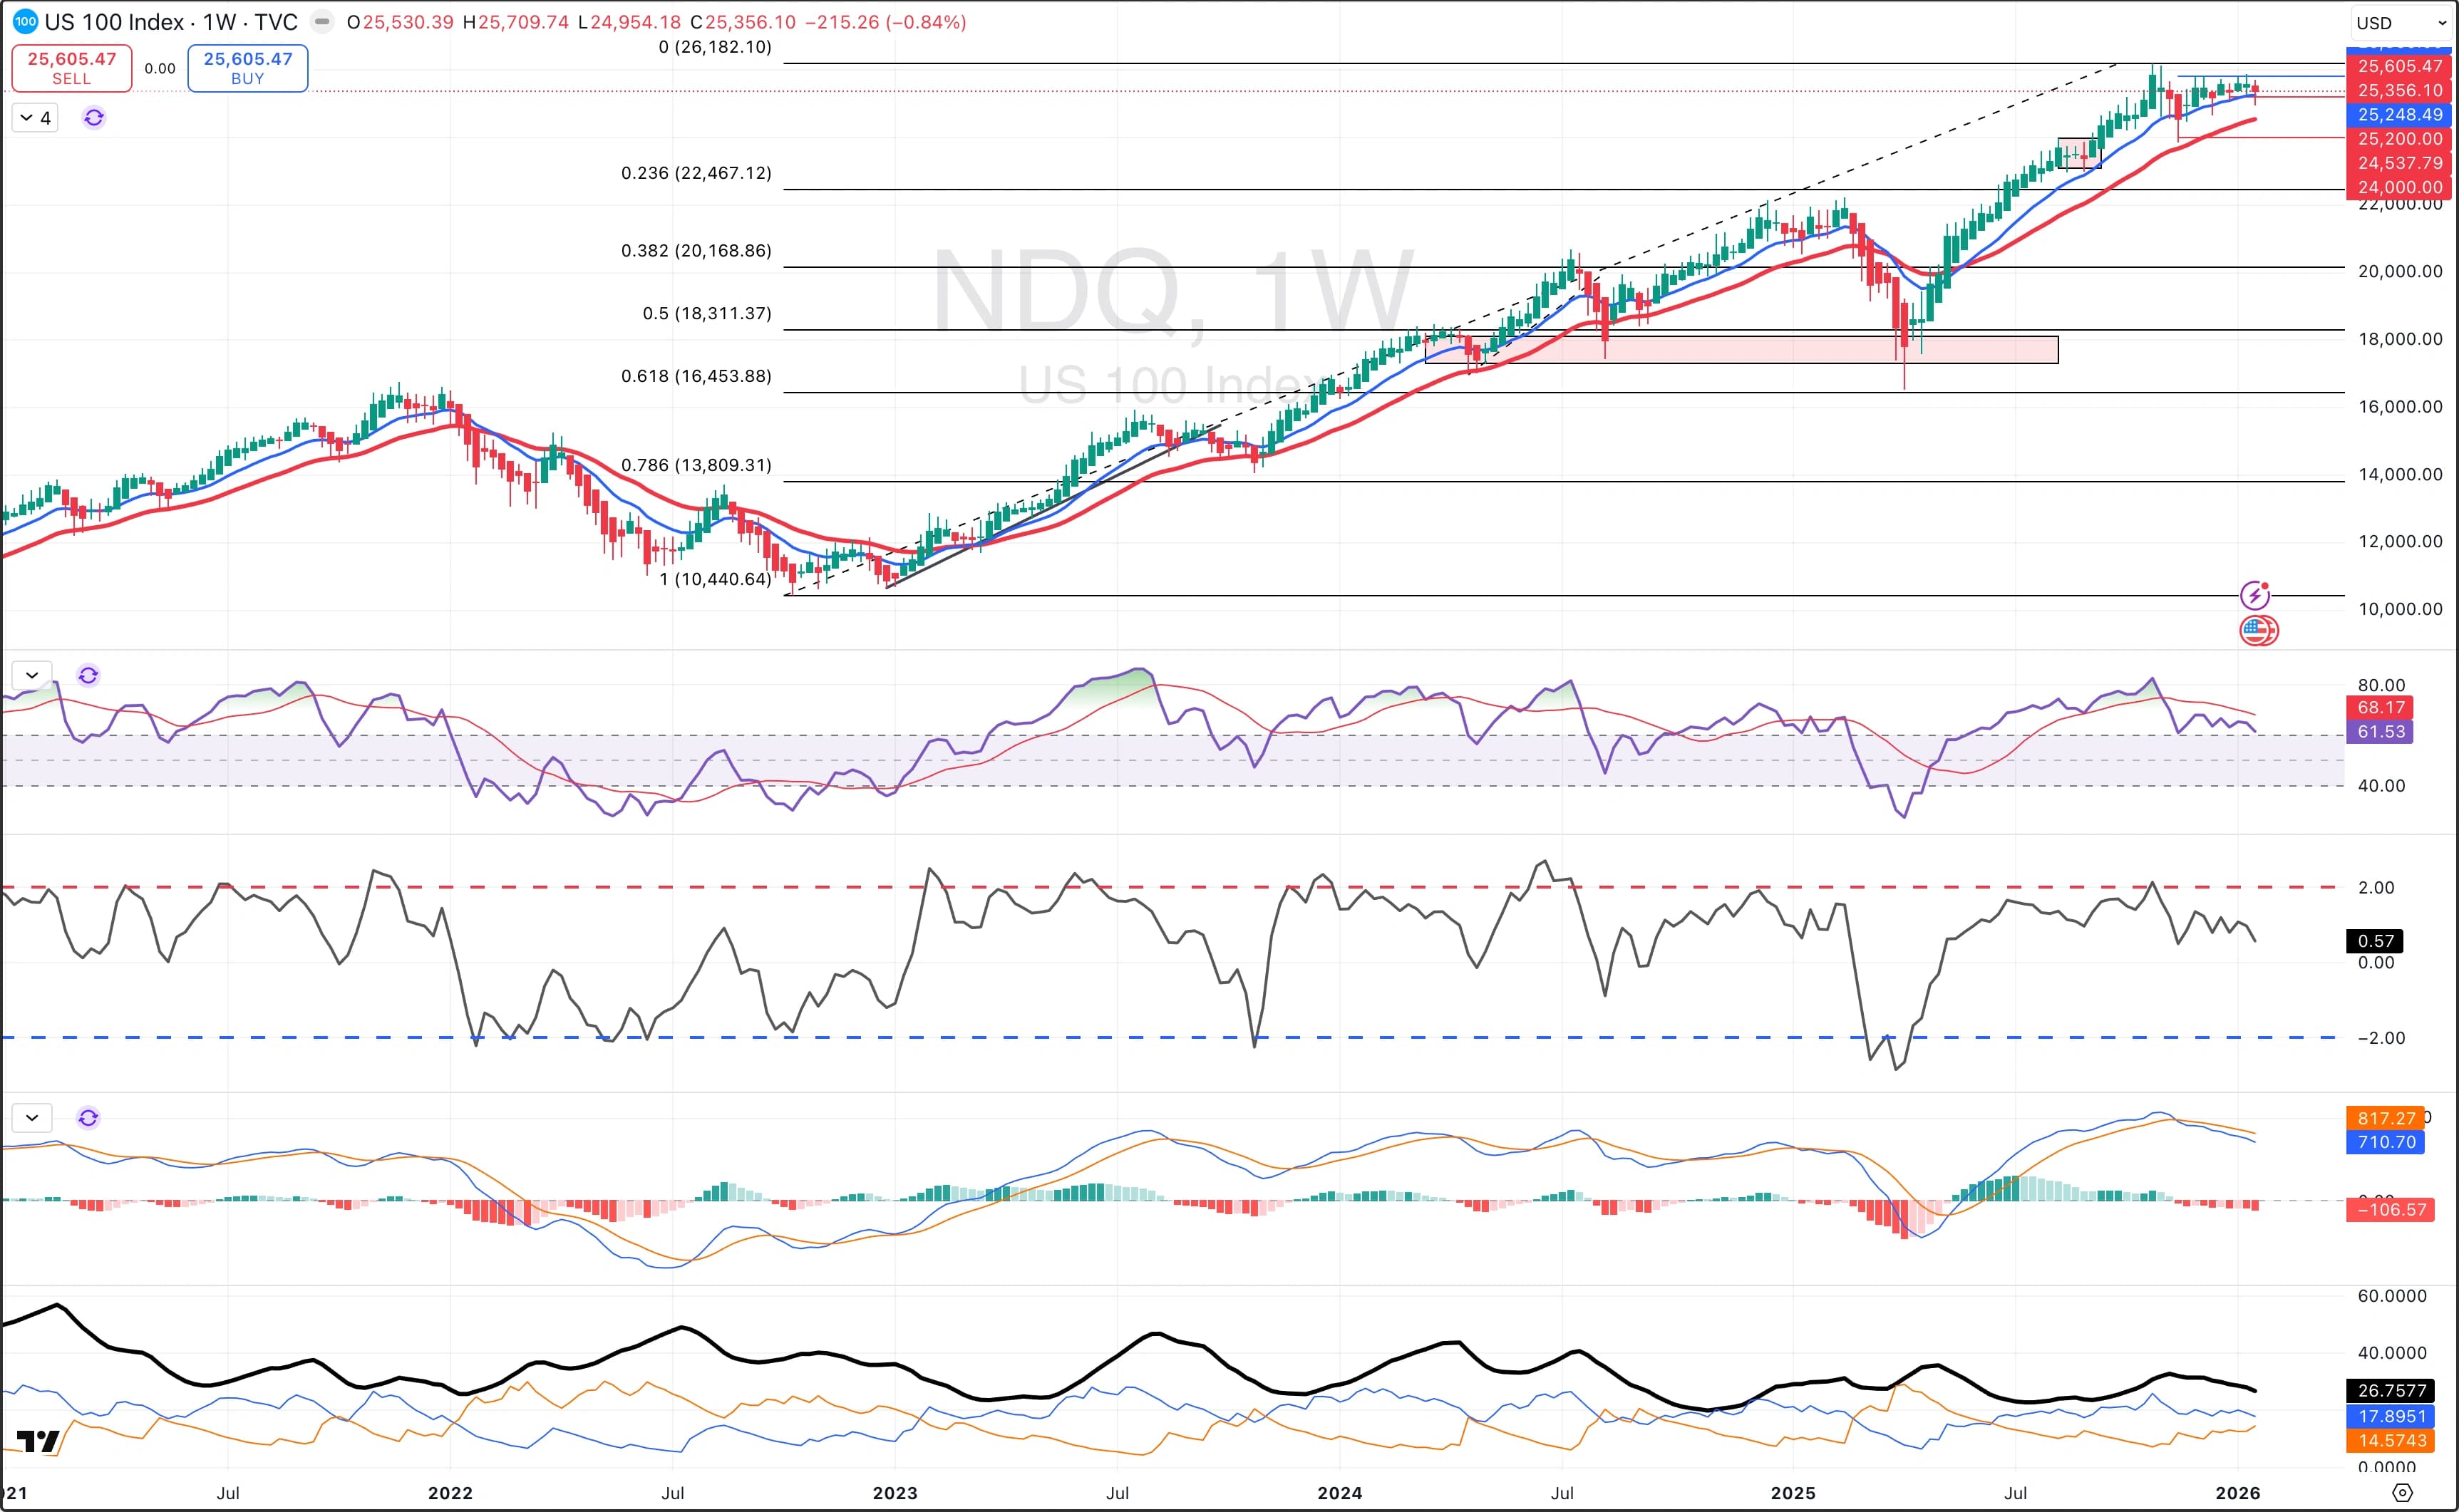
Trend Dynamics - Nasdaq is stuck in a narrow range, lacks clear directionNasdaq 100 shows a market struggling to define clear direction, trading near recent highs around 25,600 but failing to break decisively higher.
Momentum indicators reveal weakening strength despite elevated price levels, suggesting potential exhaustion in the tech-heavy rally.
The index remains above key Fibonacci retracement levels, with critical support at the 23.6% level (22,467) and the 50-day moving average providing dynamic support.
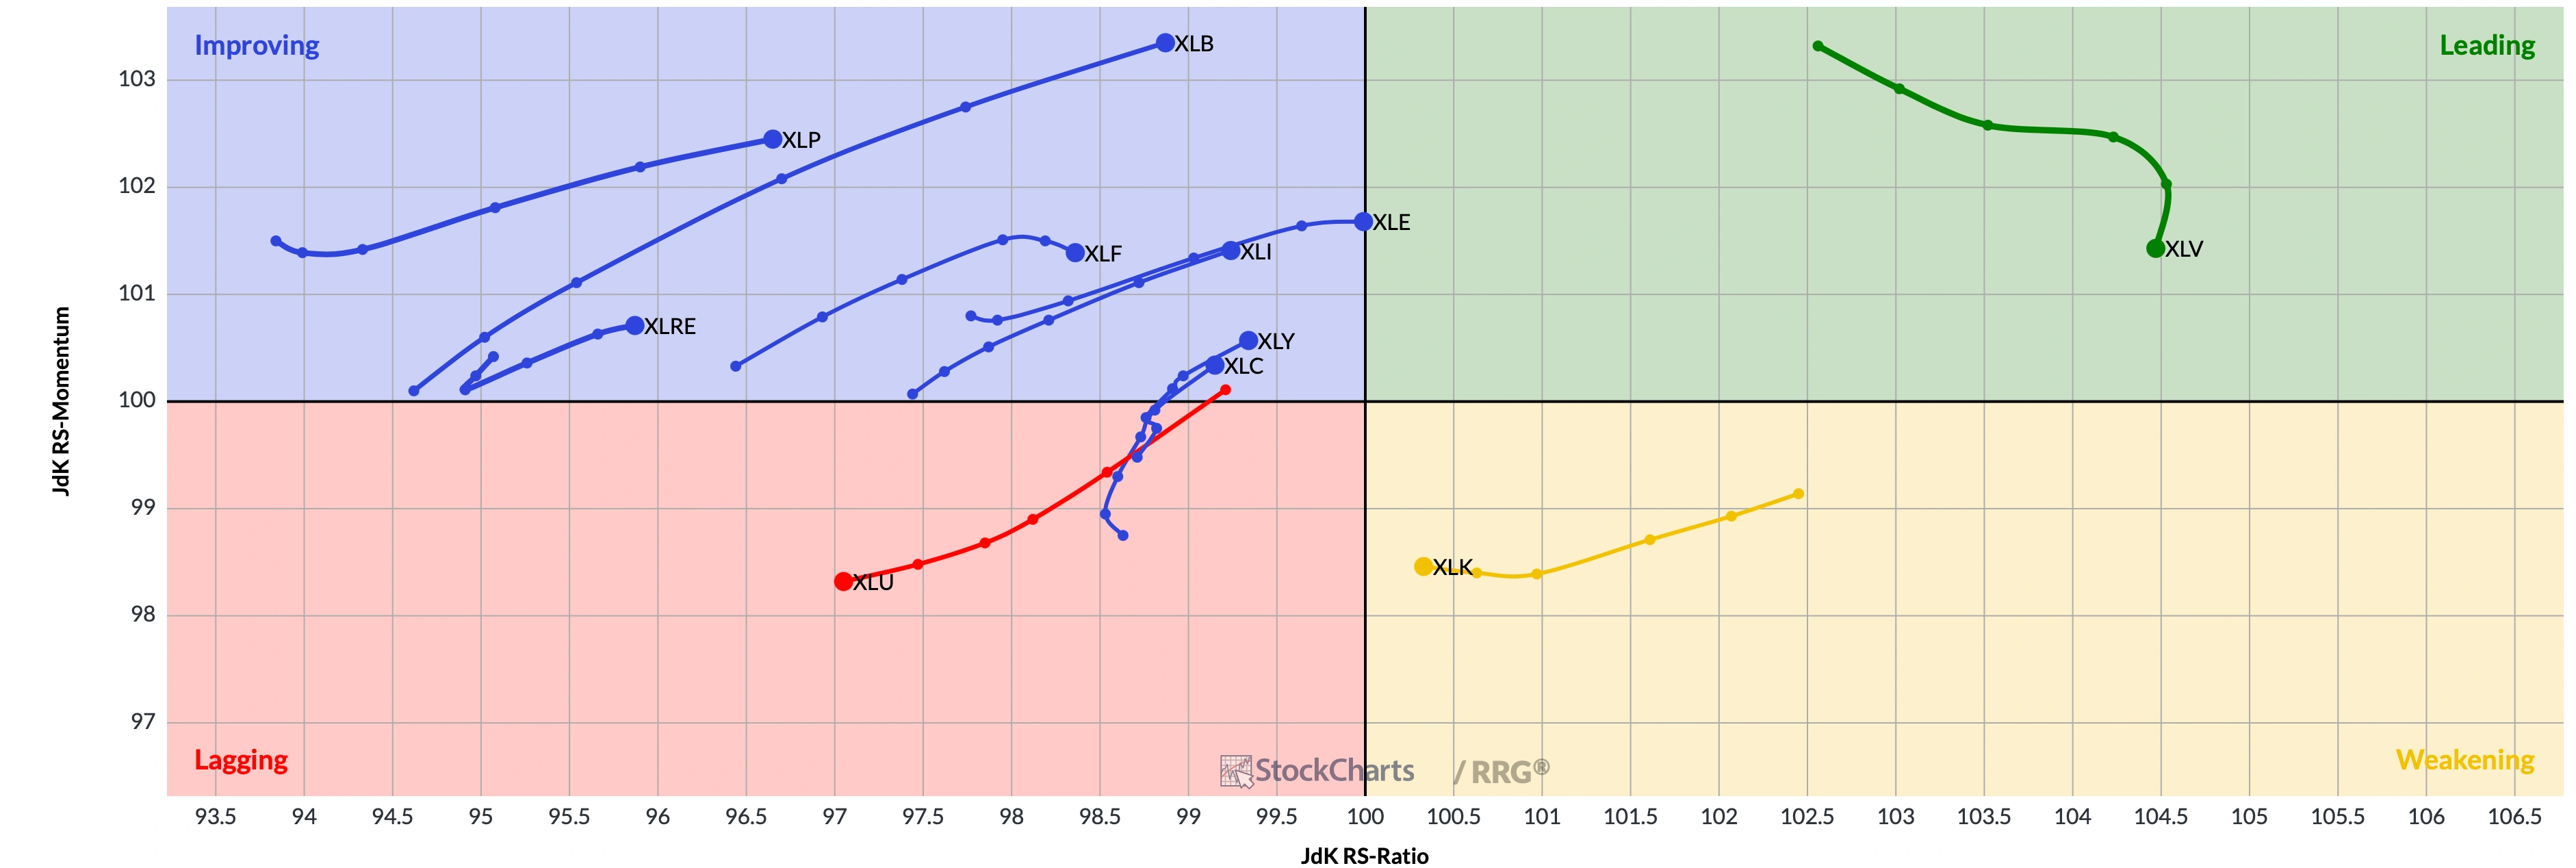
Rotational trends also favor defensive (healthcare in particular) and value sectors (industrials merit a close watch).
Multiple sectors (XLB,XLP, XLRE, XLF, XLI, XLY, XLC) have migrated from lagging to improving quadrants, signalling broad-based momentum shifts favoring value-oriented sectors.
Technology and growth sectors show deteriorating relative strength, with XLK (Technology) positioned in the weakening quadrant - a significant headwind for cap-weighted indices.
source: Trading View
Sector Rotation - Tech is the Laggard
source: Stockcharts
Upcoming Macro Data Releases
Home prices showing deceleration (1.2% forecast vs 1.3% previous) suggests housing market cooling, though still positive YoY - critical for Fed's inflation assessment.
Consumer confidence deteriorating to 88.0 from 89.1 reflects growing economic uncertainty, potentially signalling softer consumption ahead.
Fed expected to hold rates steady at 3.75%, but Powell's press conference commentary will be crucial.
Jobless claims forecast uptick to 205K from 200K bears watching for labor market softening, though levels remain historically low.
Core PPI steady at 3%y/y (albeit rising moderately m/m). Inflation remains key metric to watch.
source: Trading Economics
Upcoming Earnings Releases
Microsoft's revenue beat expectation ($80.3B vs $69.6B prior) represents 15% growth - critical litmus test for AI monetization and cloud demand sustainability.
Meta's acceleration to$58.3B from $48.4B (20% growth) demonstrates advertising resilience and AI infrastructure investments paying off, though valuation expansion warrants caution.
Apple's projected $137.2B quarter (up from $124.3B) hinges on iPhone demand in China and Services growth - any miss could trigger sector-wide tech repricing given its index weight.
Tesla facing revenue headwinds with $25.0B forecast below $25.7B a year ago, while EPS expectations remain depressed at $0.44 - automotive demand weakness and margin compression continue.
Energy sector showing divergence - Exxon expects revenue decline to $81.3B from $83.4B while Chevron projects sharper drop to $47.6B from $52.2B, reflecting softer crude prices and refining margins.
Concentration risk evident with mega-cap tech (MSFT, META, AAPL) driving market direction - their combined performance will likely overwhelm broader earnings trends.
Boeing's return to positive revenue ($22.1B vs $15.2B) marks production recovery, though still loss-making with -$0.41 EPS.
Healthcare giants United Health and HCA showing solid 12-13% revenue growth, providing defensive earnings growth amid economic uncertainty.
Payment processors Visa and Mastercard projecting double - digit growth suggests consumer spending remains resilient despite confidence deterioration
source: Trading Economics








