LC Logo FA Red RGB 1
    • About Us
    • History
    • Purpose
    • Philosophy
    • Founder's Note
    • Team
    • Wealth Management
    • Advisory and Capital Solutions
    • Global Indian
    • Asset Management
    • Private Market Funds
    • Public Market Funds
    • Founders' Ecosystem
    • Technology & Innovation
  • Our Impact
  • Insights
  • Careers
  • Contact Us
Footer-logo

About

  • About Us
  • History
  • Purpose
  • Philosophy
  • Founder's Note
  • Team

Our Businesses

  • Wealth Management
  • Advisory and Capital Solutions
  • Global Indian
  • Asset Management
  • Private Market Funds
  • Public Market Funds
  • Founders' Ecosystem
  • Technology & Innovation

Careers

  • Life at Lighthouse Canton
  • Culture & Values
  • Employee speak

Our Impact

Insights

Contact Us

  • Contact
  • offices

  • Privacy Policy
  • Disclaimer

© 2026 LIGHTHOUSE CANTON PTE LTD

Lighthouse Canton Pte. Ltd., Singapore is regulated by Monetary Authority of Singapore ("MAS") and its affiliate Lighthouse Canton Capital (DIFC) Pte. Ltd.is regulated by Dubai Financial Services Authority ("DFSA")

  1. Home/
  2. Insights/
  3. Market Views/
  4. The Not So Magnificent Seven... | CIO Insights

Investment Insights

07 January 2026

The Not So Magnificent Seven... | CIO Insights

Sunil Garg Managing Director, Chief Investment Officer
The Not So

Subscribe to our Insights & Updates

Country of Residence

*By submitting the contact form, you consent to all data in the form being used in accordance with LCPL Group's data privacy policy

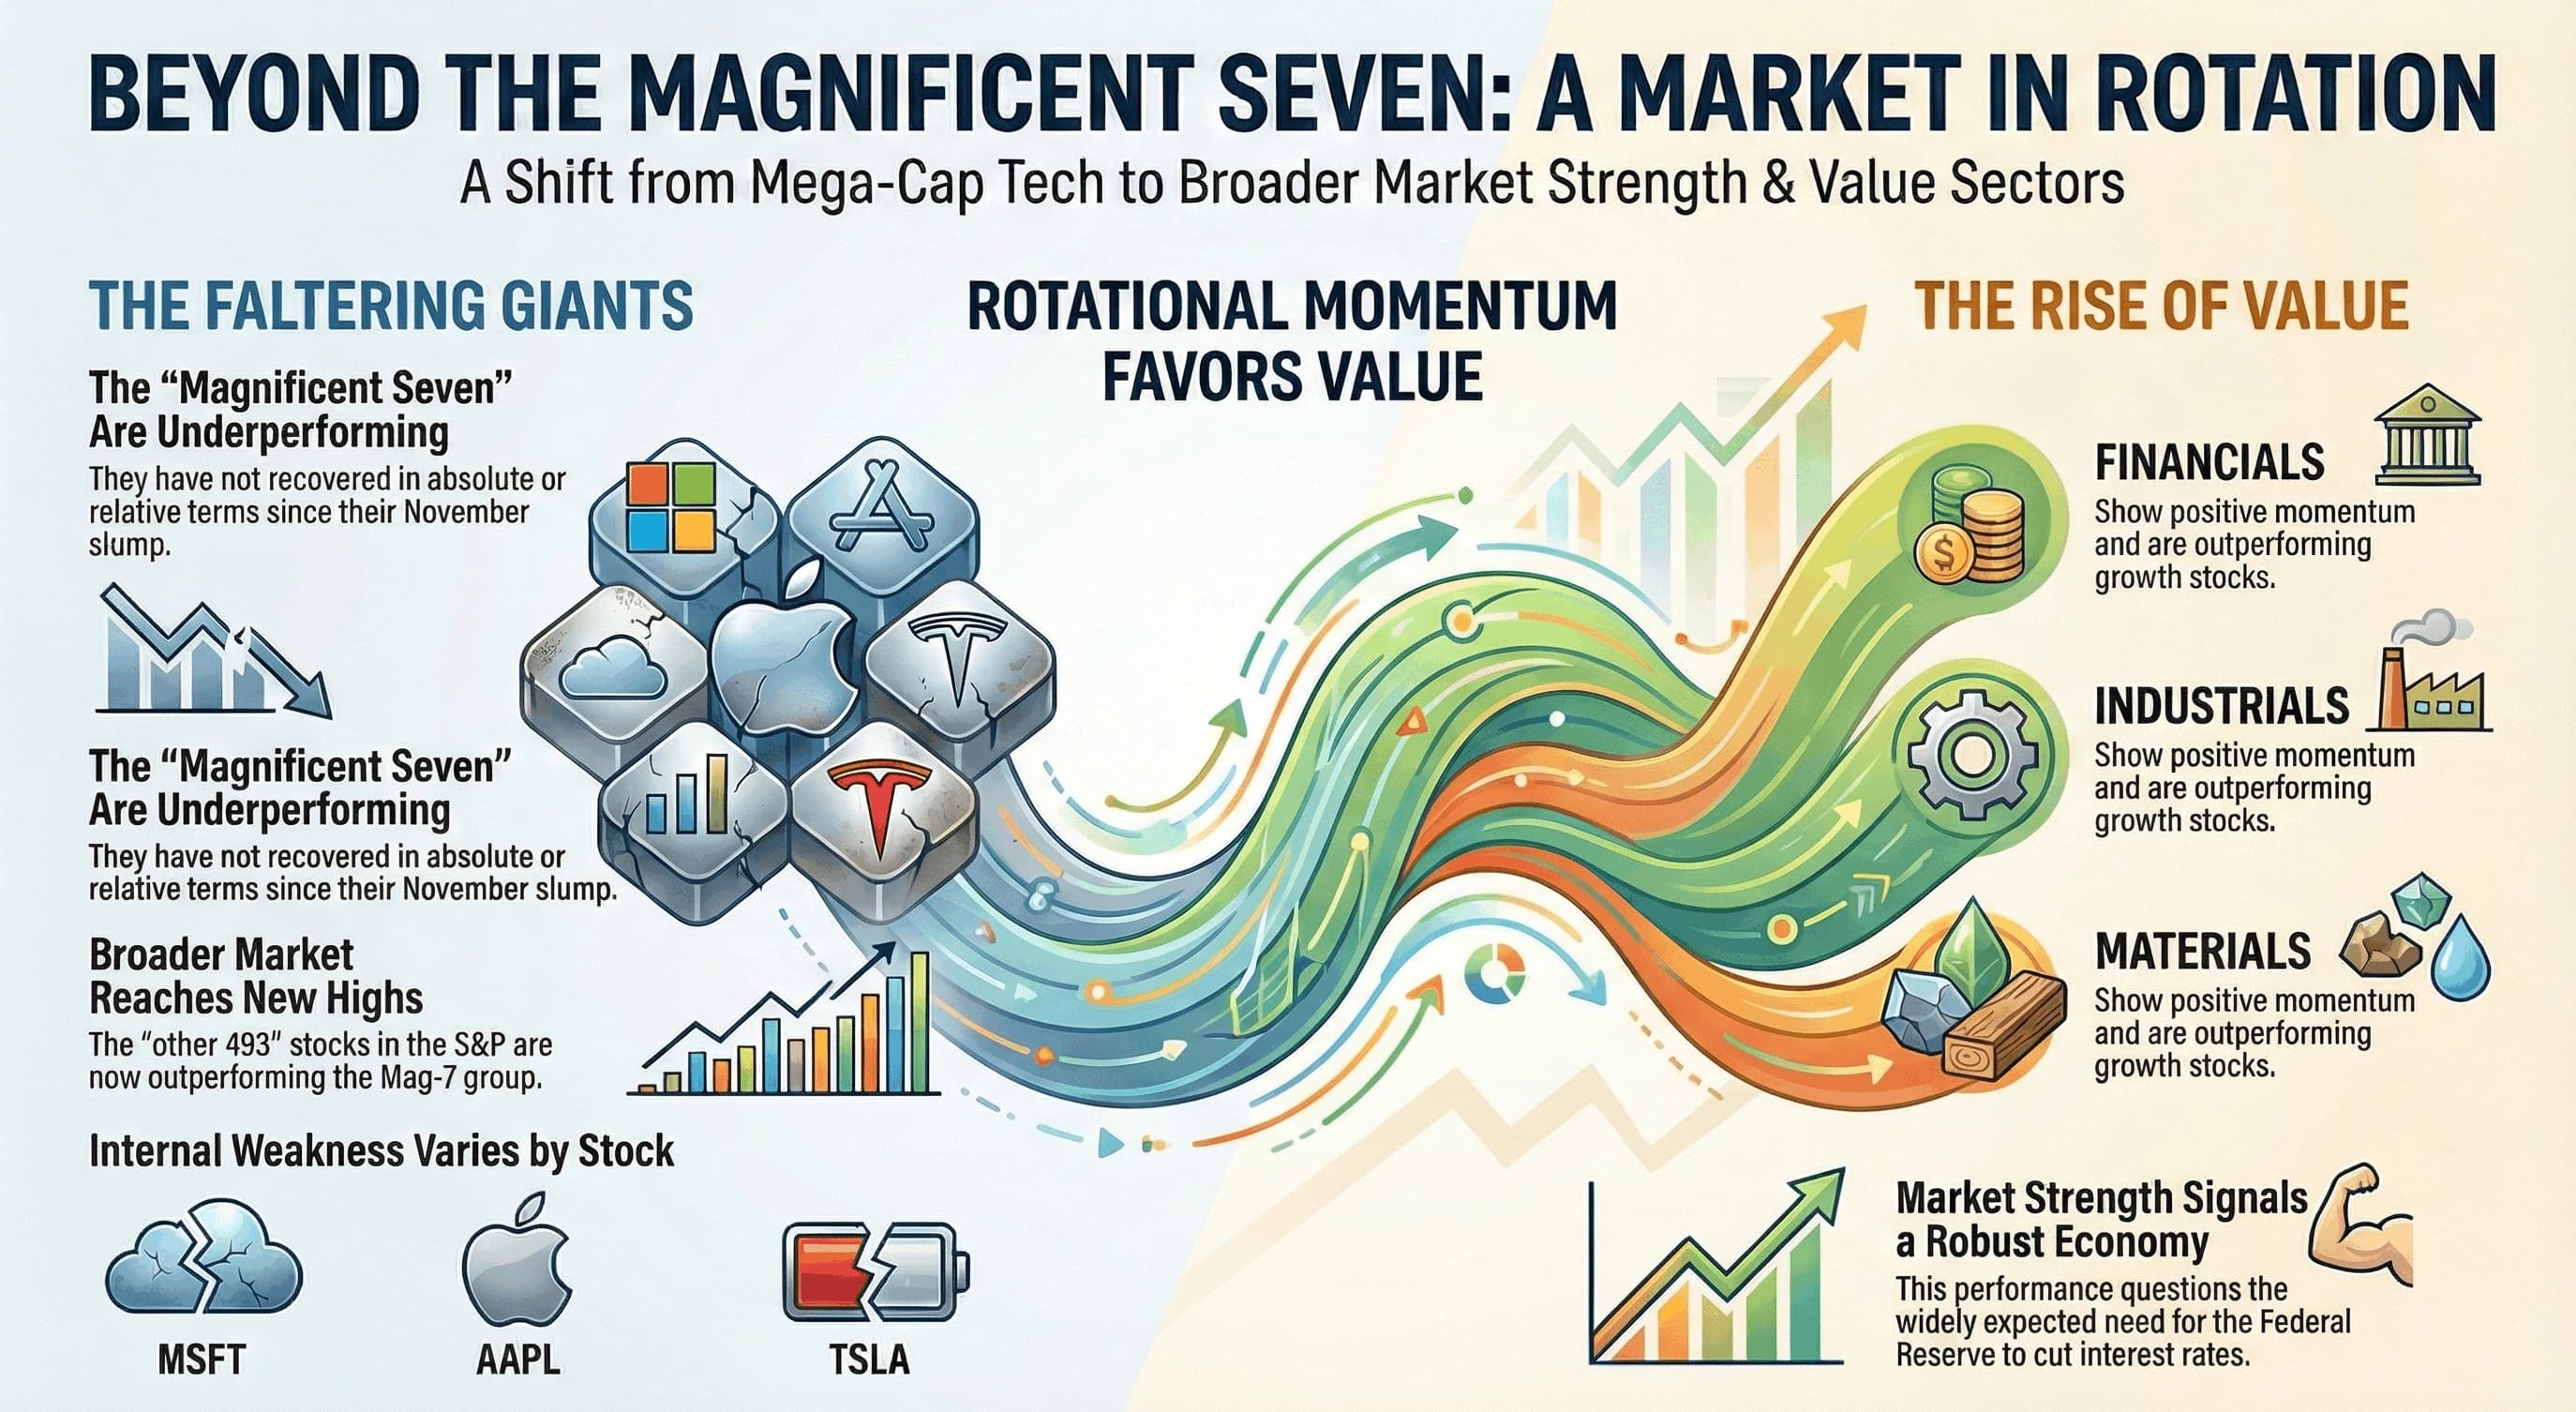
Mag-7 is clearly struggling, and doing that since end Oct'25. The malaise is reflected both in absolute performance and relative to the broader market. In an environment where tech and growth are struggling in general (see note from 5th Jan "as goes January, so goes the year") one would expect "defensive" sectors (staples, utilities, healthcare) to be outperforming - but that's not the case. So what is driving performance? It's "Value Sectors" (Financials, Industrials, Materials). Consensus is positioned for growth aided by rate cuts - but markets see cyclical growth rather than an impulse led by monetary policy.

Broadening participation is generally good news, especially into cyclical value sectors, suggesting a relatively robust economic environment. Our proprietary economic nowcaster corroborates the view of an economy humming along. But this does raise the question of why the FED needs to cut at all? There are other implications too - strength in commodities raises inflationary risks, further pressurizing treasury yields higher, which in turn benefits financials as the yield curve steepens.‍

As for the broad market, the biggest question is whether strength ex-tech can sustain?

‍

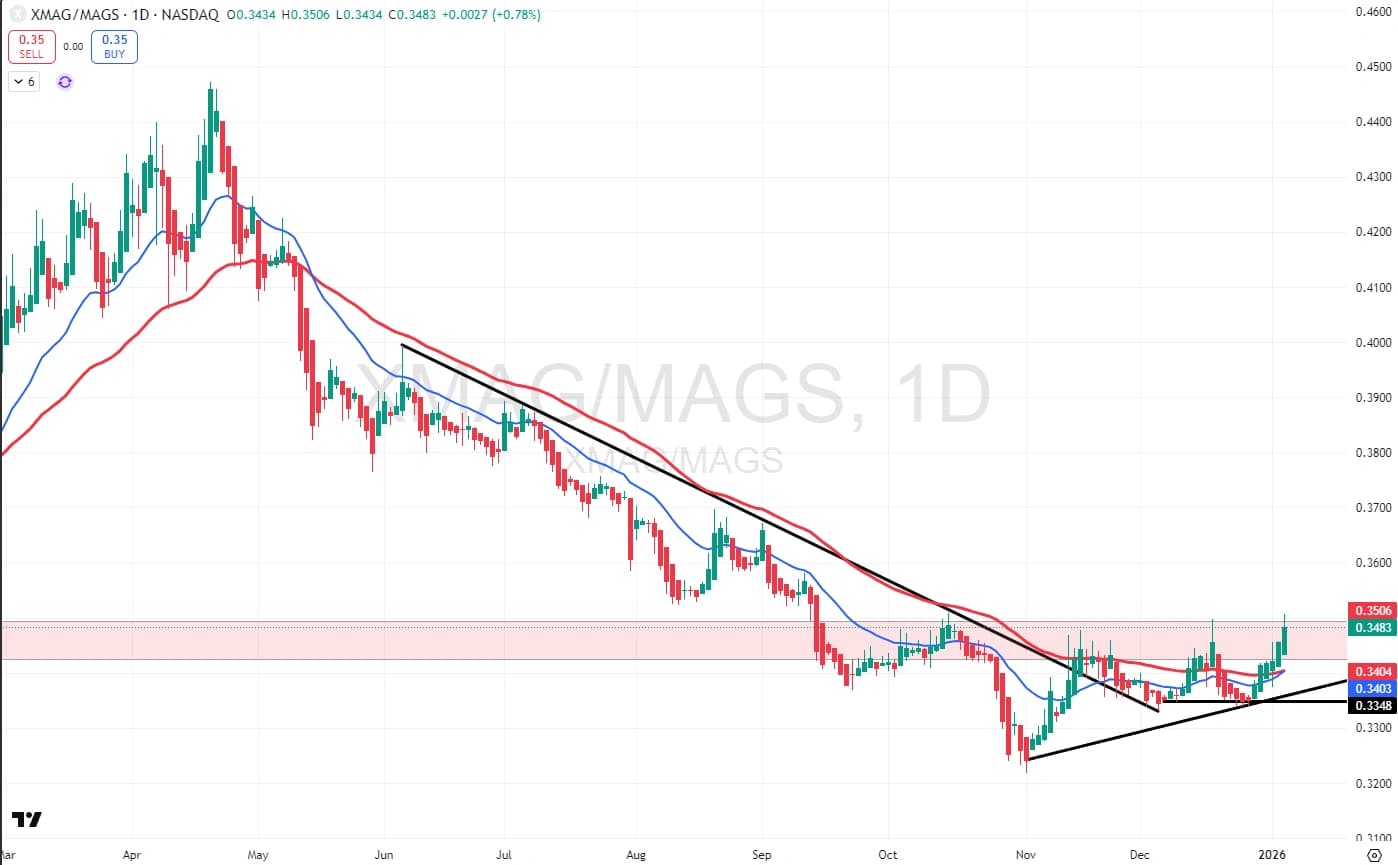
  • The Not So Magnificent Seven - MAG-7 have recovered neither in absolute, nor in relative terms since the Nov'25 swoon led by concerns on AI related capex and monetization risks. Meantime, the broader index (S&P) is back to new highs, led by the "other 493" stocks - fig 1 below shows the XMAG (other 493 stocks) building on recent outperformance vs. the MAG-7 after a 28% point underperformance between Apr'25 and Oct'25.‍

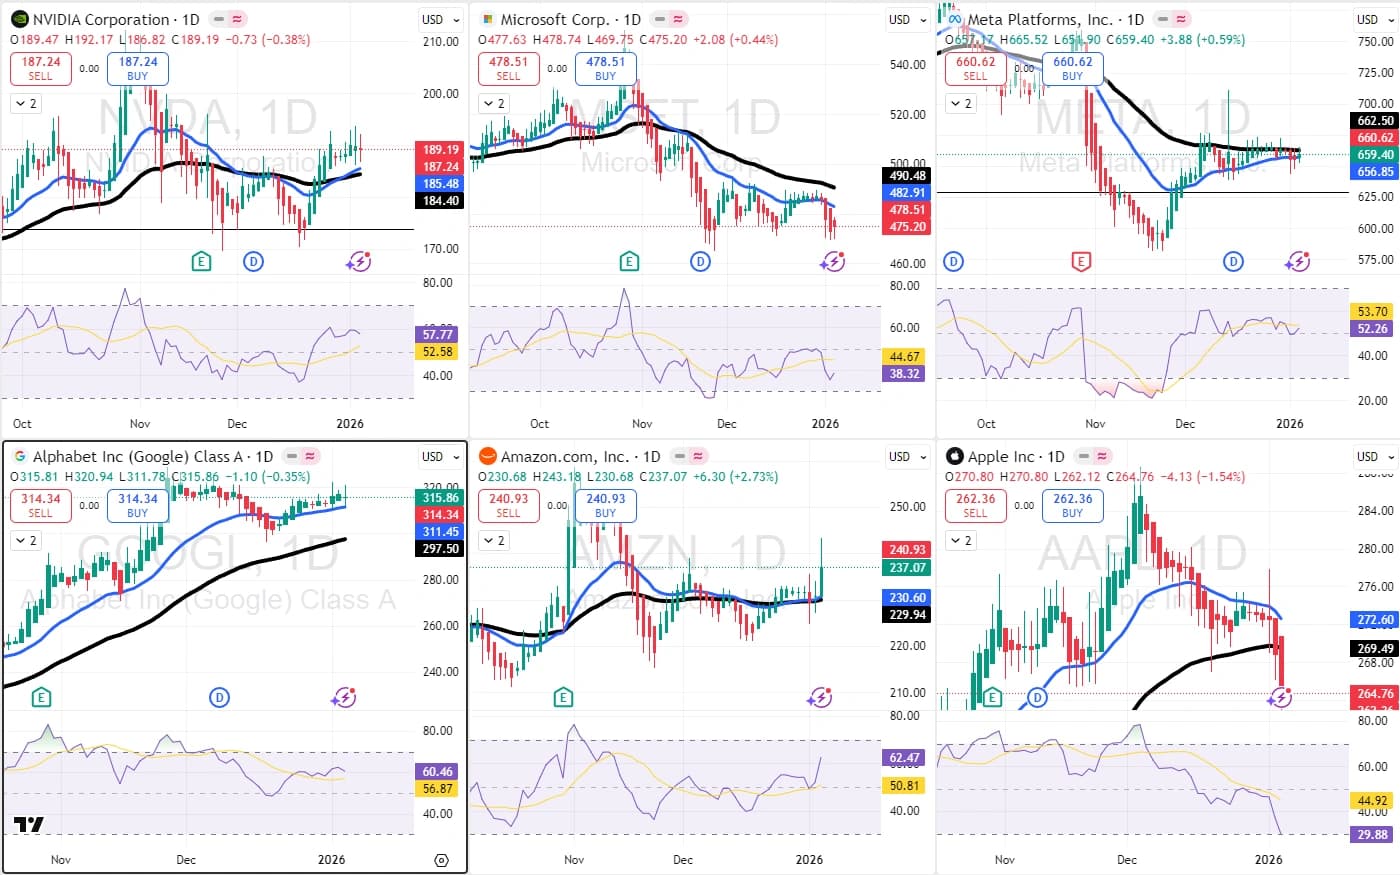
  • The Differentiation Within the MAG-7 (fig 2) - Even within the MAG-7, all aren't created equal. MSFT, AAPL and TSLA are clearly the worst positioned while AMZN and GOOGL have better momentum. NVDA and META are searching for direction.‍

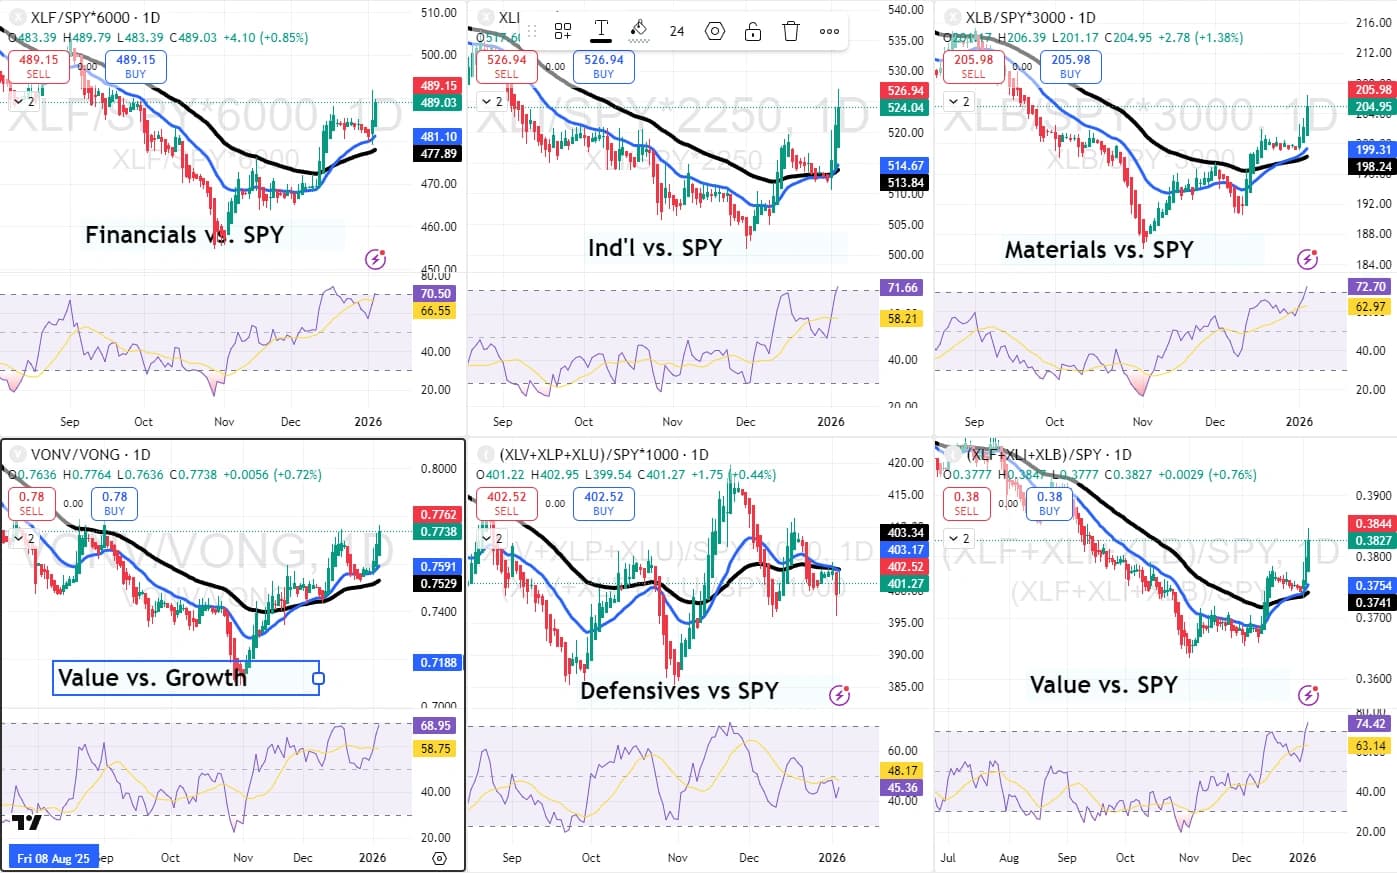
  • Style Bias Favors "Value" (fig 3) - Not only is value outperforming growth and the broad market, all the three value sectors, financials, industrials, materials have positive momentum.‍

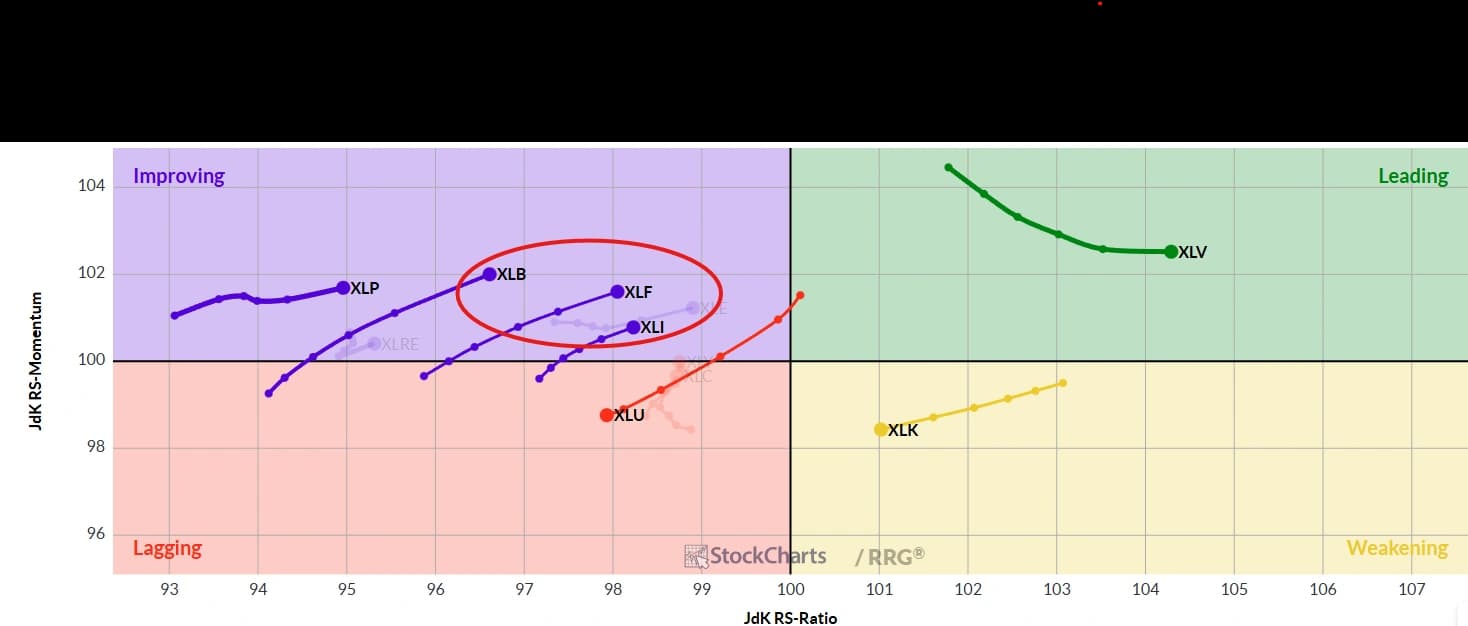
  • Rotational Trends at Play (fig 4) - Rotational trends clearly show momentum in favor of value sectors. Interestingly though, even amongst the defensives, it's really utilities that are a drag - somewhat understandable given that the sector has become somewhat of an "AI Play" rather than the classic defensive positioning.‍

Fig 1 - XMAG (493 stocks ex MAG-7) vs. MAG-7 - Magnificent Seven - Not so Magnificent
Magnificent 01

source: Trading View

Fig 2 - AAPL and MSFT - Worst Positioned
Magnificent 02

source: Trading View‍

Fig 3 - Value is Outperforming
Magnificent 03

source: Trading View‍

Fig 4 - Value Sectors Have Momentum...
Magnificent 04

source: Stockcharts

‍
Magnificent 05
‍
Read More
SOME SUGGESTION
View All
thumbnail.png
Market Views
INVESTMENT INSIGHTS

The world is competing for capital | The Beam: Weekly Market Narrative

16 October 2026
thumbnail.png
IDEAs: Views & Insights
LC IDEAS: VIEWS & INSIGHTS

The New Gateway to Wealth Planning

16 October 2026
thumbnail.png
Market Views
INVESTMENT INSIGHTS

Dark Clouds over Neo Clouds

15 October 2026
Artificial Intelligence Ecosystem
Market Views
INVESTMENT INSIGHTS

From Atoms to Intelligence

13 October 2026
thumbnail.png
Market Views
INVESTMENT INSIGHTS

The Other Energy...

07 October 2026
thumbnail.png
Market Views
INVESTMENT INSIGHTS

Breakout, Meet Breadth

06 October 2026
Threading The Needle
Outlooks
OUTLOOKS

Threading The Needle - Q4 2026 Outlook

06 October 2026
thumbnail.png
Market Views
INVESTMENT INSIGHTS

Leveraged Covered Calls

05 October 2026
thumbnail.png
Market Views
INVESTMENT INSIGHTS

Strong Economy, Weak Tape: Who Is Right? | The Beam: Weekly Market Narrative

05 October 2026
thumbnail.png
News & Updates
COMPANY UPDATES

Sanket Sinha on Bloomberg: Private Credit Market Remains Positive for Asia

01 October 2026