
Investment Insights
CIO Insights: There Are Lies, There Are Damned Lies and There Are Statistics...
Sunil Garg Managing Director, Chief Investment Officer
Table of Contents
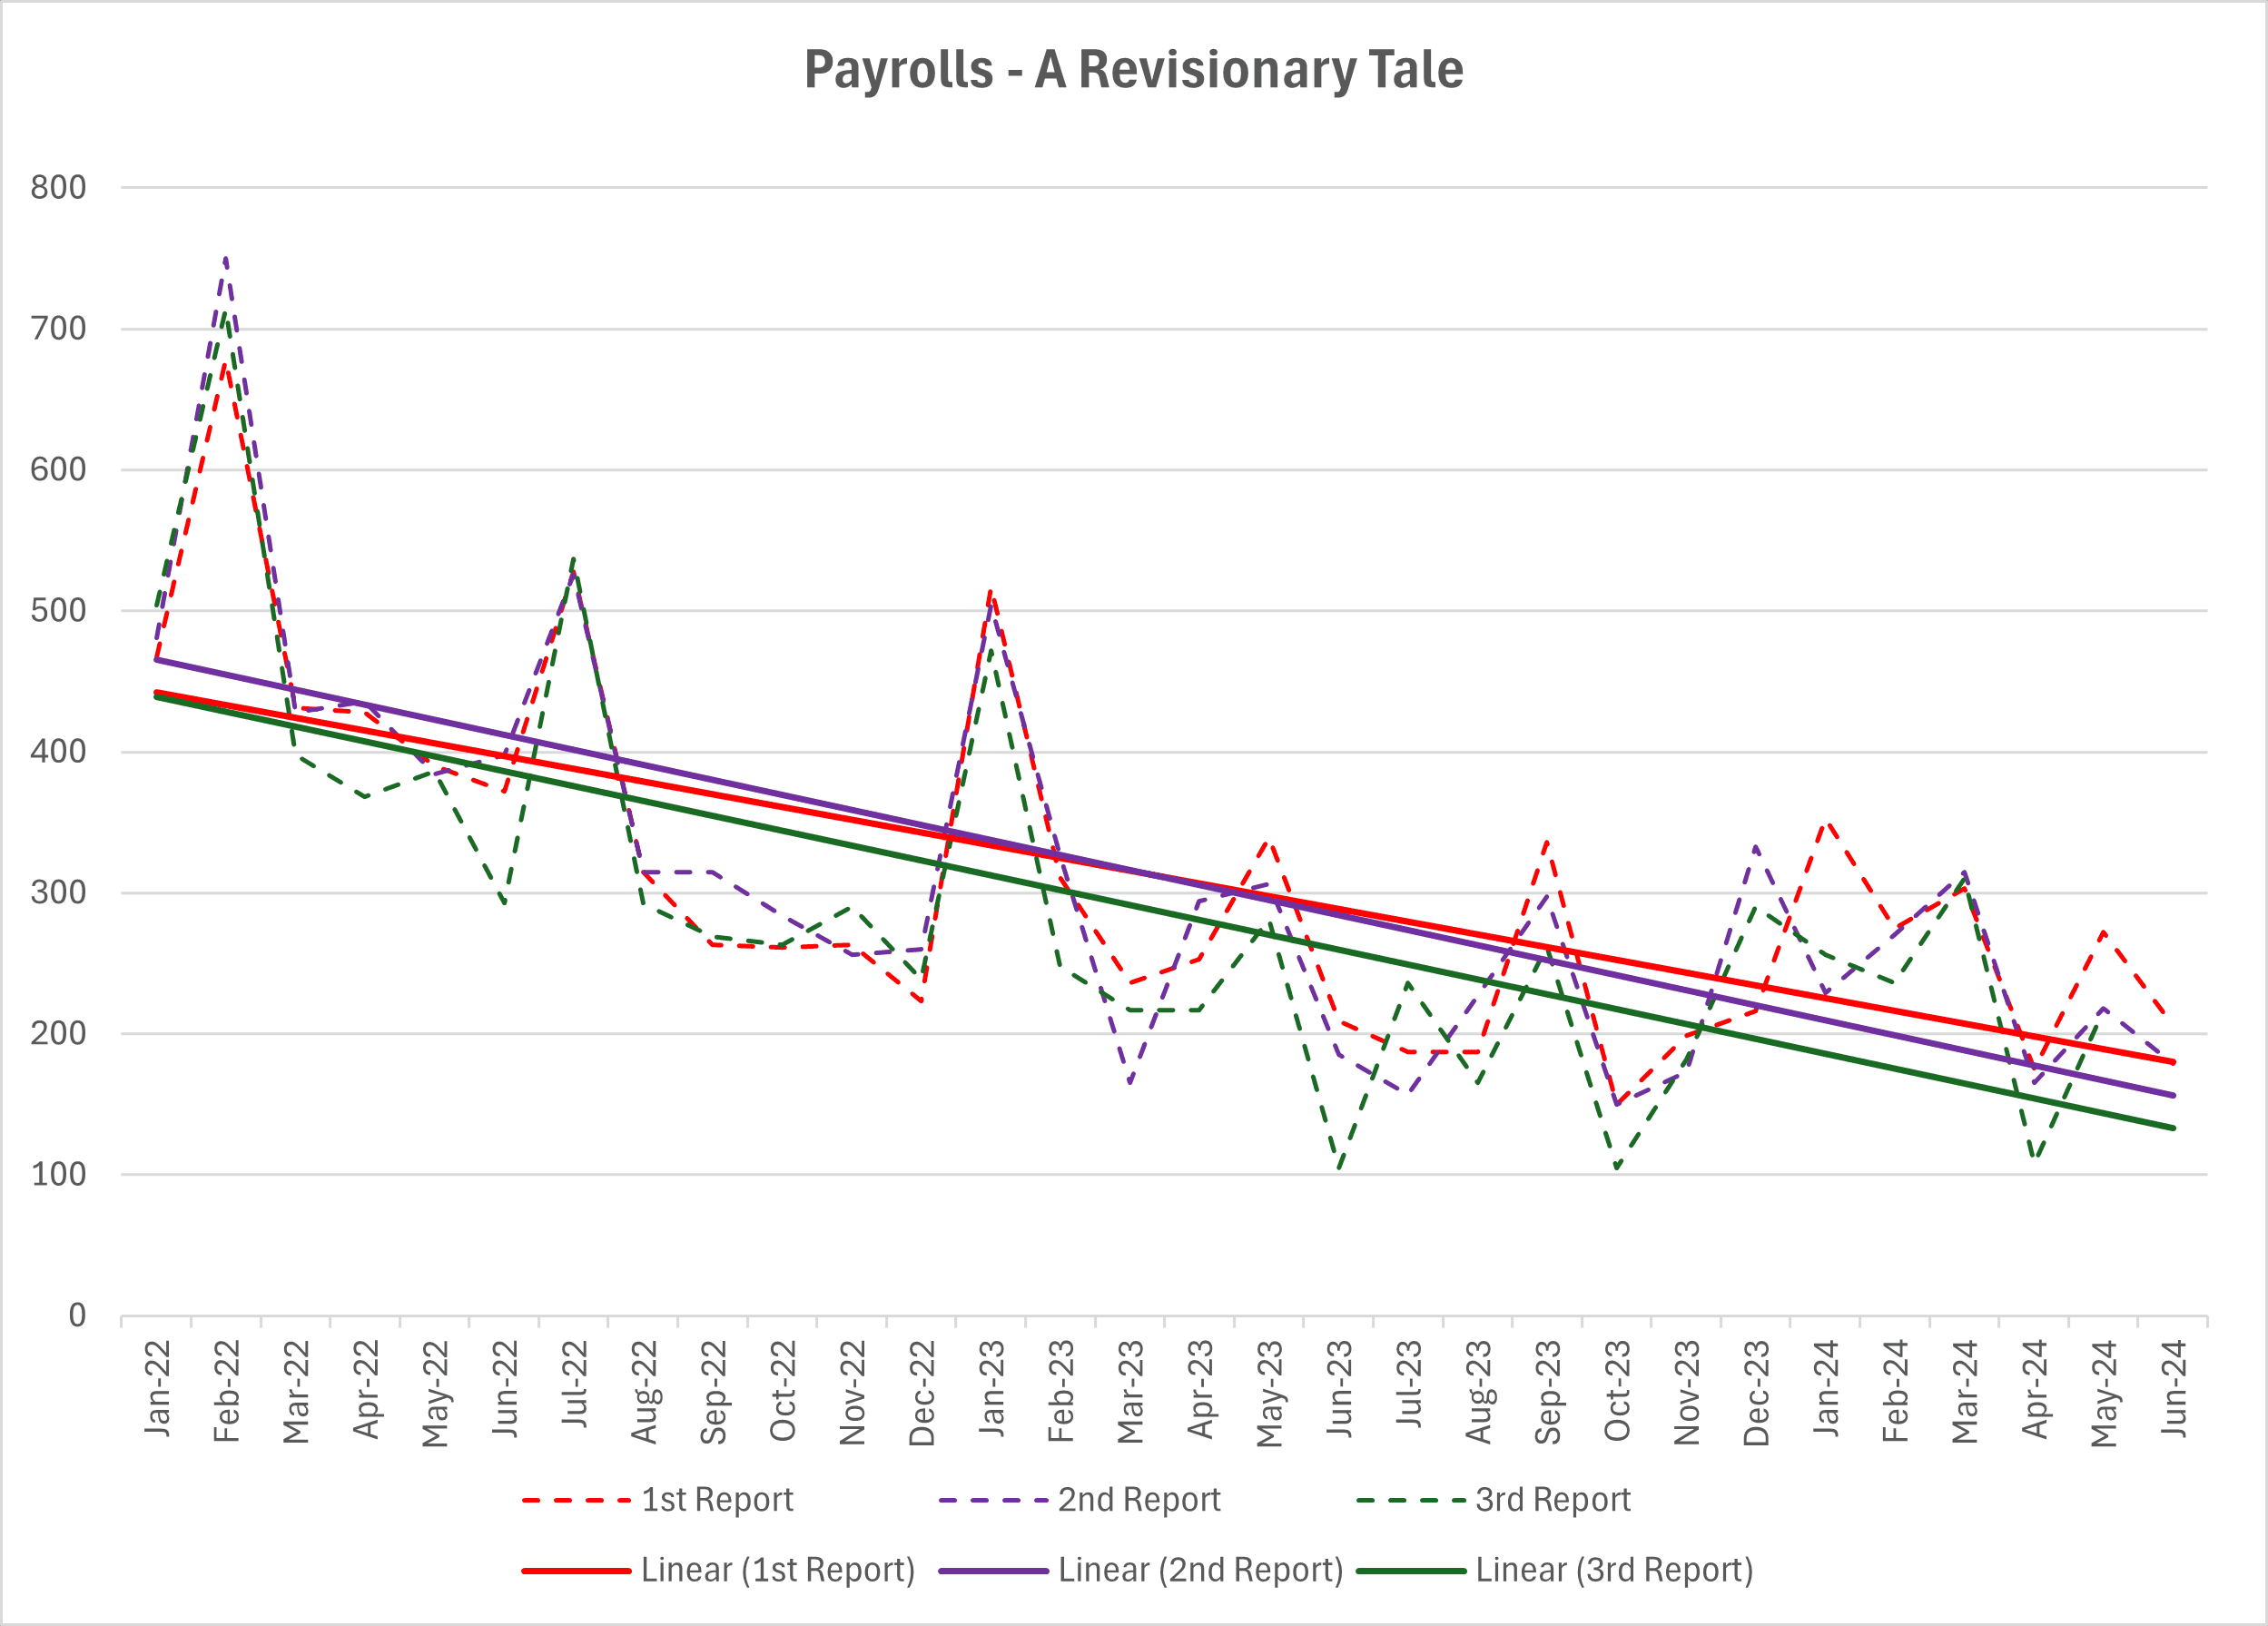
We debate the value of market's obsession with payrolls (1st Friday of the month) given how much (and often) of a revision this data series is subject to. Not only focusing on the c27% downward revision to the Apr'23-Mar'24 payrolls (which will be finalized only by Feb'25!), we note an average 12% downward revision in 2023 and 18% in 2024 (revisions upto May 2024) between the 1st report and the 2nd revision, which of course was further revised down in the annual report. Given the criticality of labor data in assessing the health of the economy, perhaps triangulating other labor statistics would provide a more comprehensive picture. Even as the payrolls show a downtrend (fig 1), other metrics such as job openings, job quits, wage growth, unemployment, jobless claims, give a more complete picture.
For investors, a softening labor market (even before the annual revision) has clear implications for further cementing expectations of monetary easing. While a 50bp cut in Sep now appears to be off the table (FED Funds Futures suggest a mere 35% probability of a 50bp rate cut), the path for rates is most certainly downwards.
Then there is of course the critical question of what this means for growth, led by consumption and held in place by the labor market. While anecdotally, multiple businesses are citing growth headwinds in their forward guidance, we also need to balance that with recent positive retail sales data. Can the tailwind from lower interest rates negate the headwind from a demand slowdown that likely accompanies weaker labor markets, in effect a "soft landing"? Our skepticism on this goldilocks outcome stems from focusing on trends, that suggest weaker consumption and weaker labor markets.
Notwithstanding our skepticism, for now, the market is clearly buying the positive narrative. A breakout past all time highs will further challenge our view.
How to Position - The clearest opportunity is in fixed income and gold. For fixed income, while spreads remain compressed near historical lows, duration extension remains the opportunity. Gold is a direct beneficiary of lower rates. For equities, we remain positive on names with growth visibility, especially in the GenAI hardware space. Given risks to growth, we continue to recommend dynamically hedging aggregate equity exposures.
Monthly Payrolls with 1st and 2nd Revisions
1st release on 1st Friday each month, subject to two revisions (fig 1 shows the three data series along with a linear trendline)
Average downward revision of 12% in 2023 and 18% in Jan-May'24, excluding the annual revision
Annual revision of c27% (previously reported jobs 3.01mn, revised down by 0.82mn)
Fig 1 - Monthly Payrolls with Revisions
source: Bureau of Labor Statistics (bls.gov)
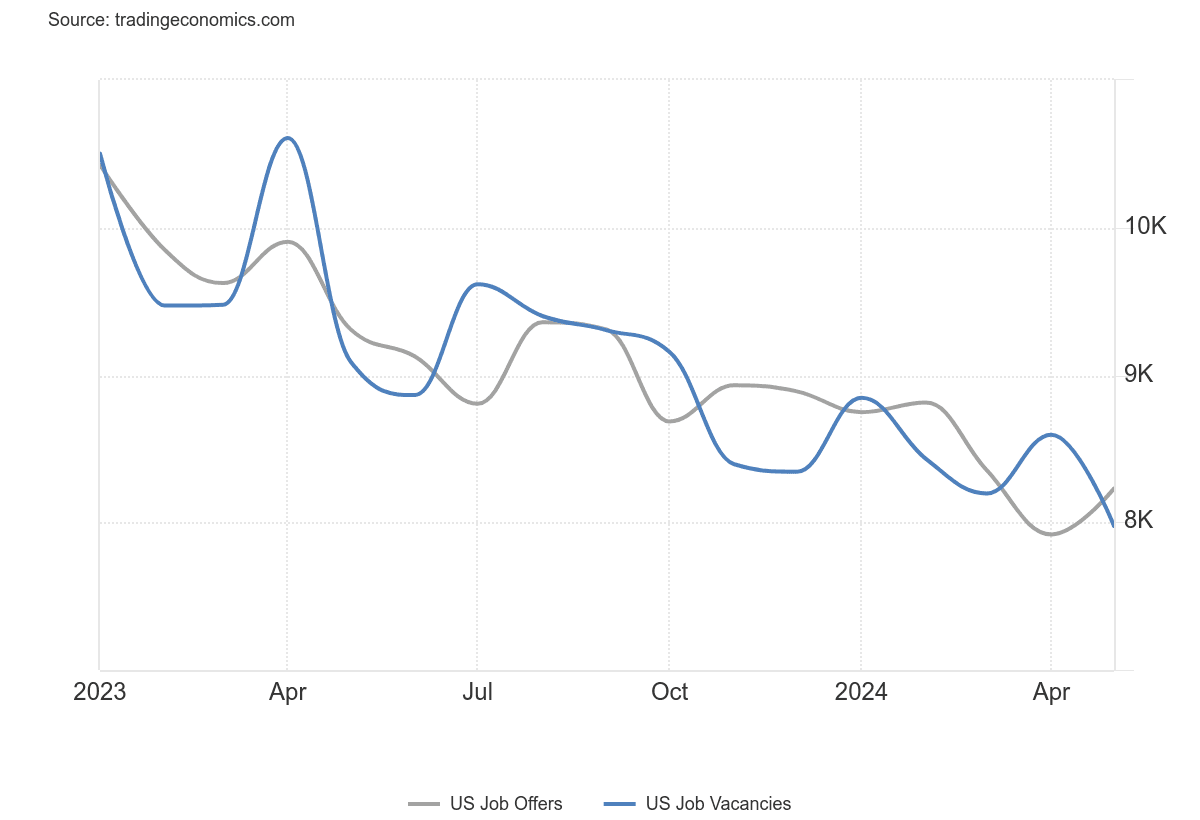
Job Openings & Offers
Job openings and offers continue to trend down (fig 2)
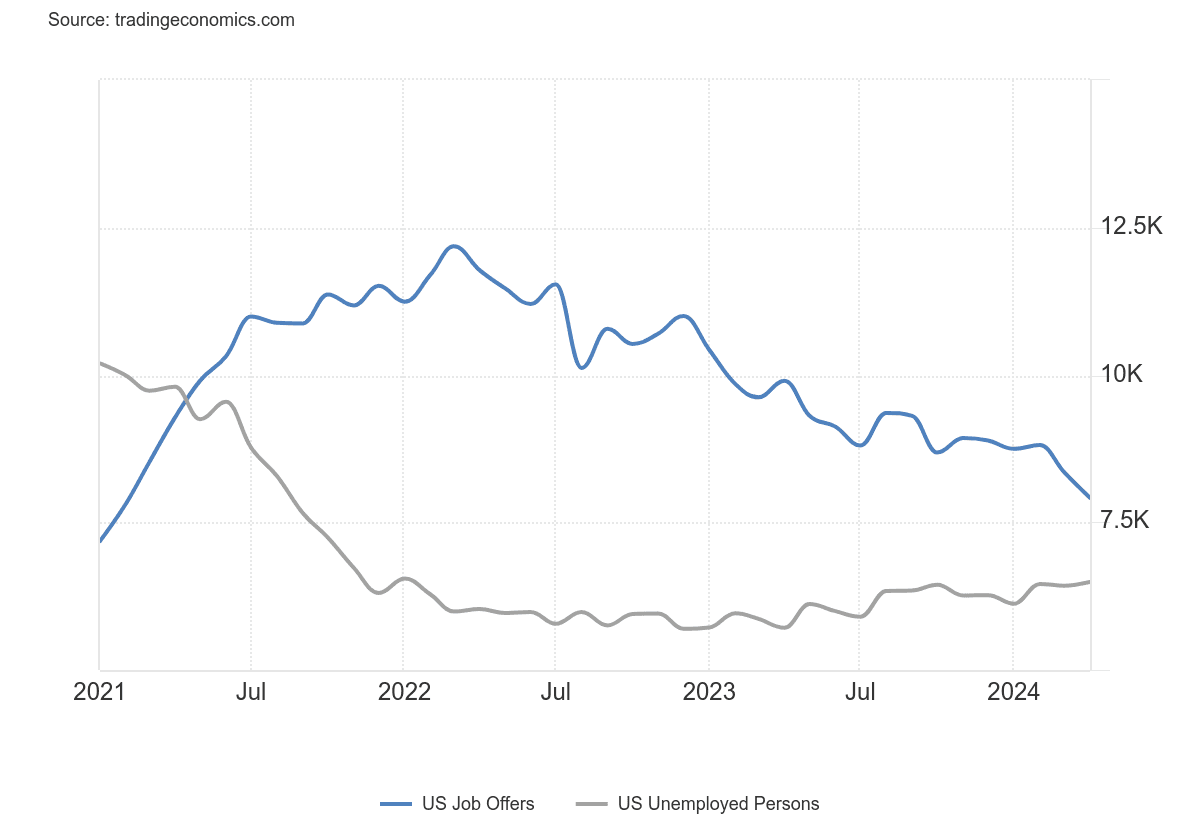
Job offers/unemployed person continues to trend down
Fig 2 - Job Offers and Job Vacancies
source: Tradingeconomics.com
Fig 3 - Job offers and Unemployed Persons
source: Tradingeconomics.com
Jobless Claims, Job Quits, Wage Growth
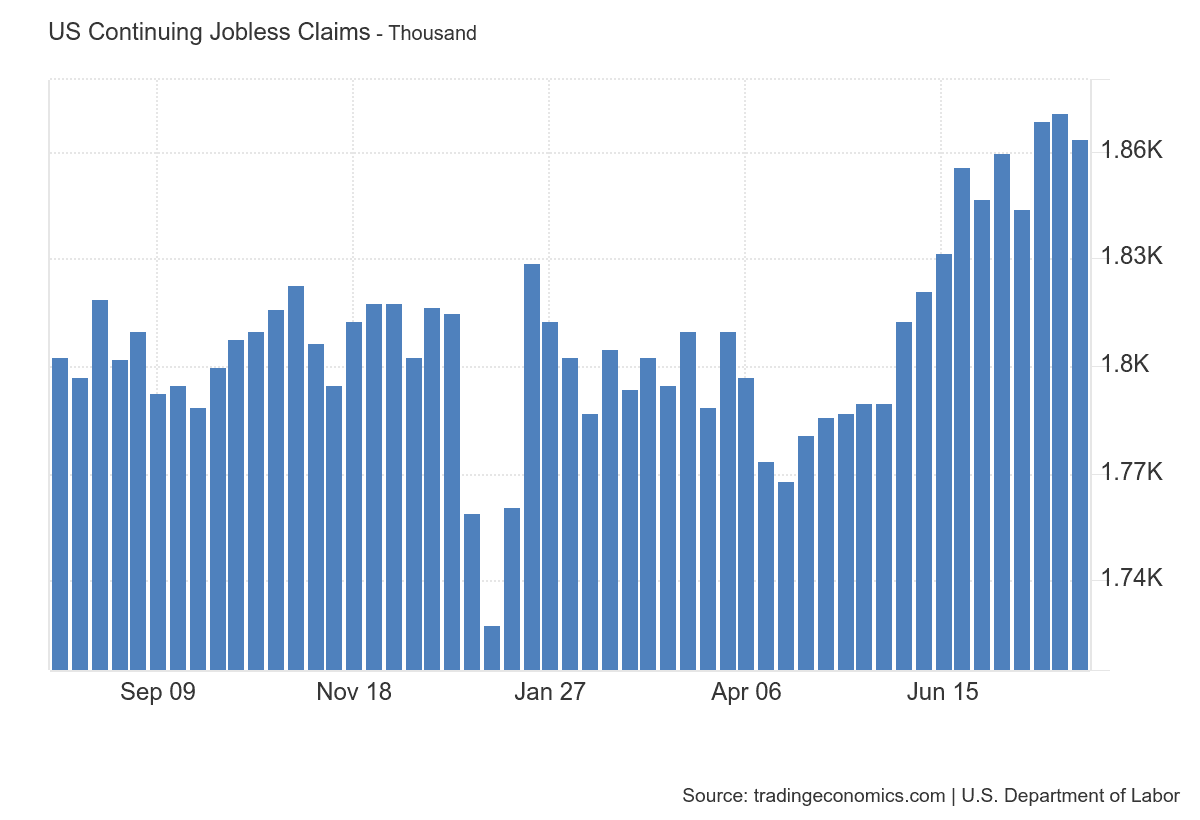
Jobless claims (fig 4) continue to track an upward trajectory
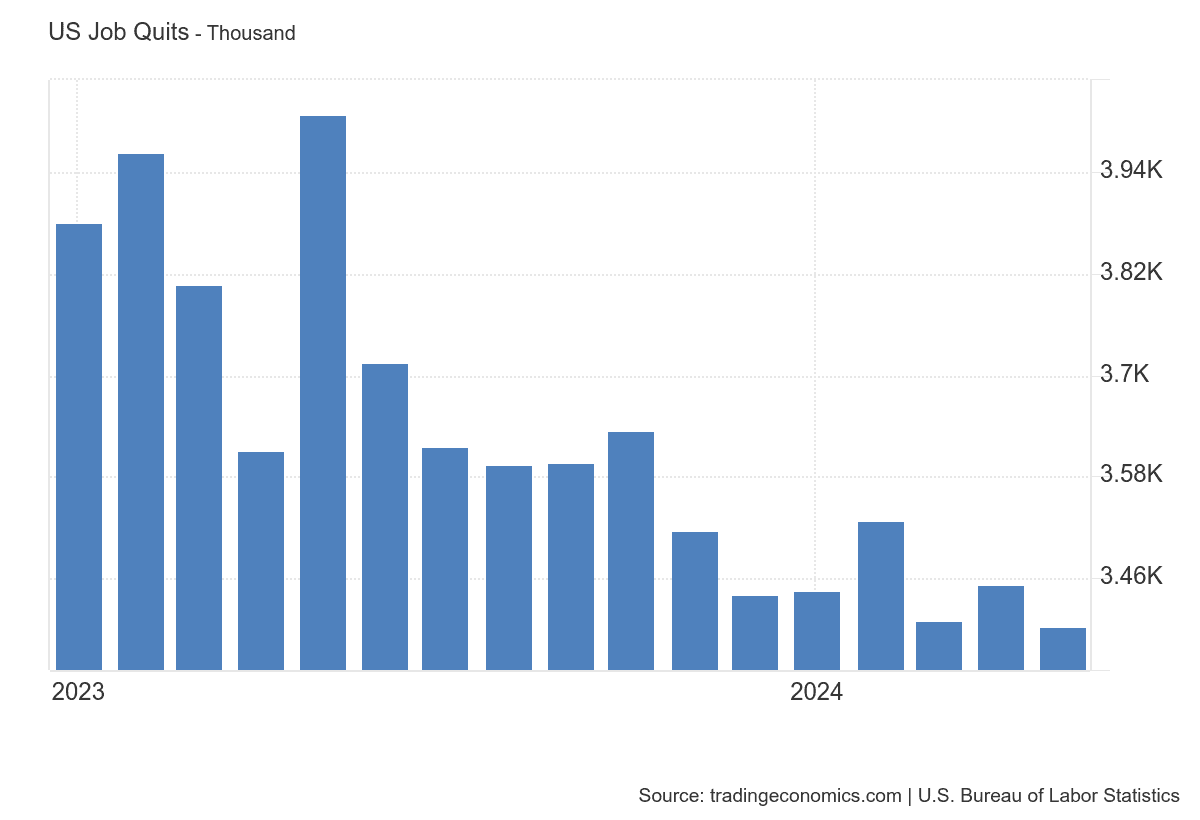
Job Quits - downward trajectory suggests workers reluctant to leave, possibly indicating weaker outlook for finding jobs
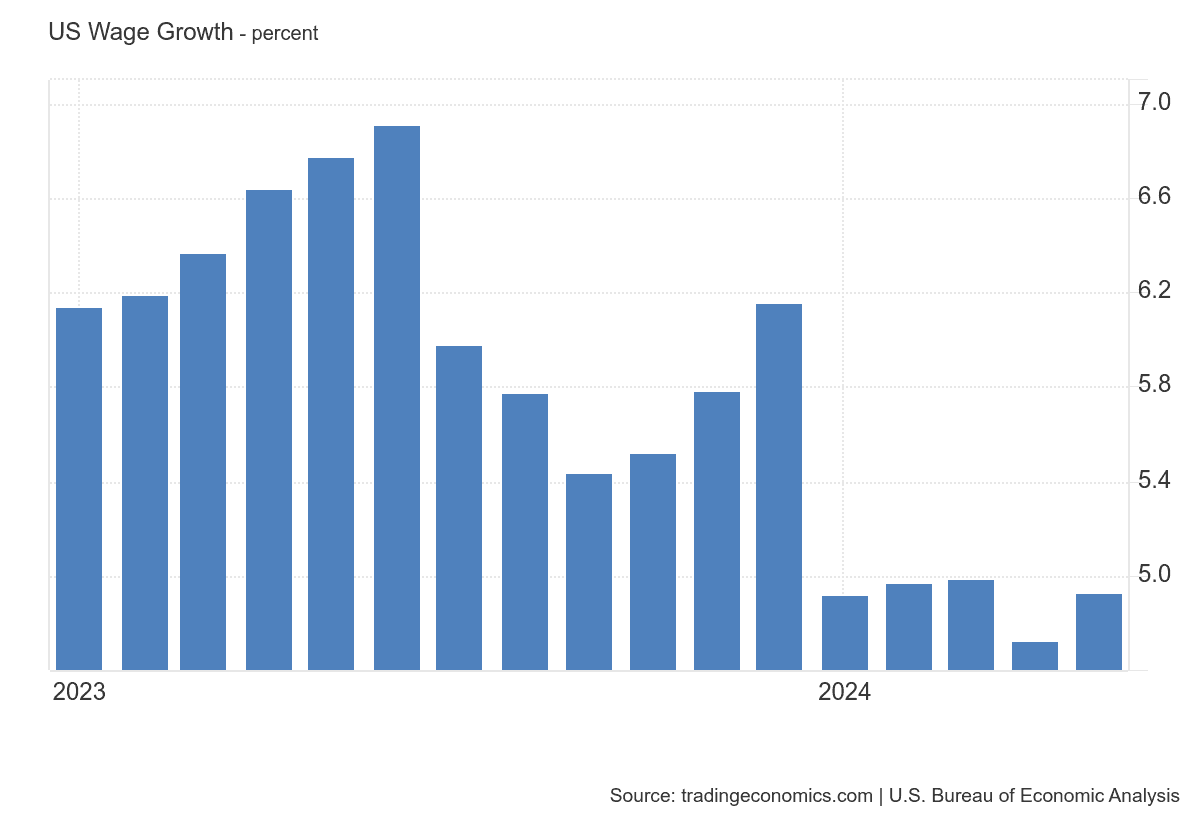
Wage Growth - trending down - potential implications for demand
Fig 4 - Continuing Jobless Claims - Upward Trajectory
source: Tradingeconomics.com
Fig 5 - Job Quits - Trending Down - Consistent with Weaker Outlook
source: Tradingeconomics.com
Fig 6 - Wage Growth - Also Trending Down
source: Tradingeconomics.com








