...and the High Came Off
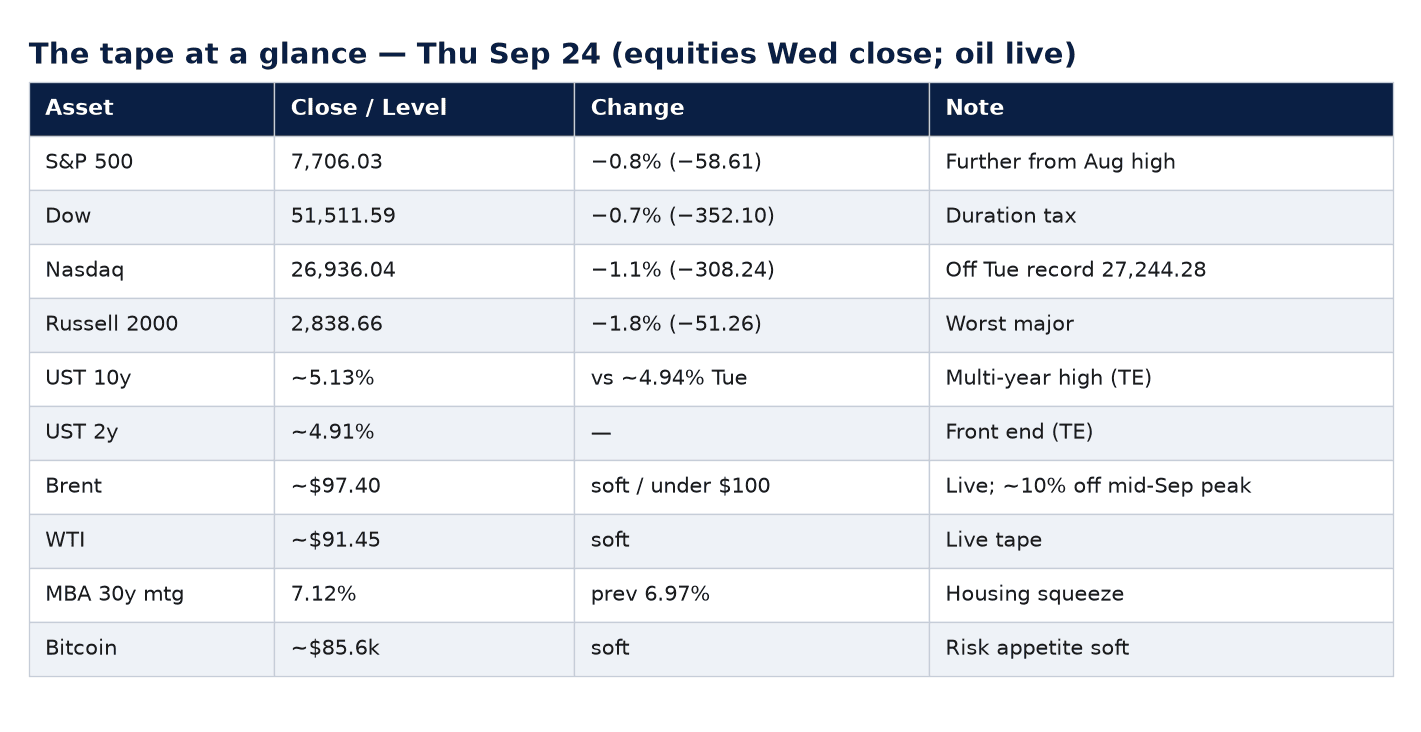
Hot flash PMIs and hawkish Fed speak shoved Treasury Yields to multi-year highs. Nasdaq’s Tuesday record came off. Soft oil, Brent ~$97.40, under $100 live (~10% off the mid-Sep peak near $108.75), is the other side of the split. Wednesday briefly reclaimed ~$103 on Iran hardline headlines; the live tape is back under $100. Diplomacy eased crude. Duration sold anyway. Equities paid the tax.
The rates shock
S&P Global flash Composite PMI 58.4 (prev 56.0; cons 55.2), five-year high territory. Manufacturing 57.0 (cons 53.6). Services 58.7 (cons 56). Price gauges sticky. Fed Governor Barr said further policy adjustments are “likely needed.”
The bond market did not wait. UST 10y ~5.13%. 2y ~4.91%. The 5-year note topped 5% for the first time since 2007; Wednesday’s 5-year auction stopped at 5.033% (prev 4.393%), a weak outlier. MBA 30-year mortgage 7.12% (prev 6.97%). CME FedWatch October hike odds jumped to ~73% from ~55% Tuesday.
That is the rates shock. Soft-landing calm is off the table until evidence suggests otherwise. Macro risk flag: hot flash PMIs + 10y above 5% + ~73% October hike odds - hot growth / sticky inflation has displaced the immaculate soft-landing tape. Pipeline PPI still elevated at 5.40% YoY.
Equities take the duration tax
Breadth broke. Utilities worst (~−1.7%). Nasdaq fell from Tuesday’s record 27,244.28 to 26,936.04 (−1.1%). S&P never confirmed the August high - still unfinished, and Wednesday pushed it further away. Energy was green Wednesday (~+0.9%) on a brief oil bounce - live crude is soft again; that sector print is not today’s oil story.
EIA crude stocks built +2.969M (cons −0.6M). Soft oil now tracks Saudi East-West pipeline restart plus Iran-talks / diplomacy hopes - multi-session slide after the mid-Sep peak. Bitcoin soft near ~$85.6k.
Scorecard: rates / PMI / highs hold
Duration sold. Growth multiples took the hit. Soft oil did not rescue the rates bid - diplomacy eased crude; duration still punched.
Charts
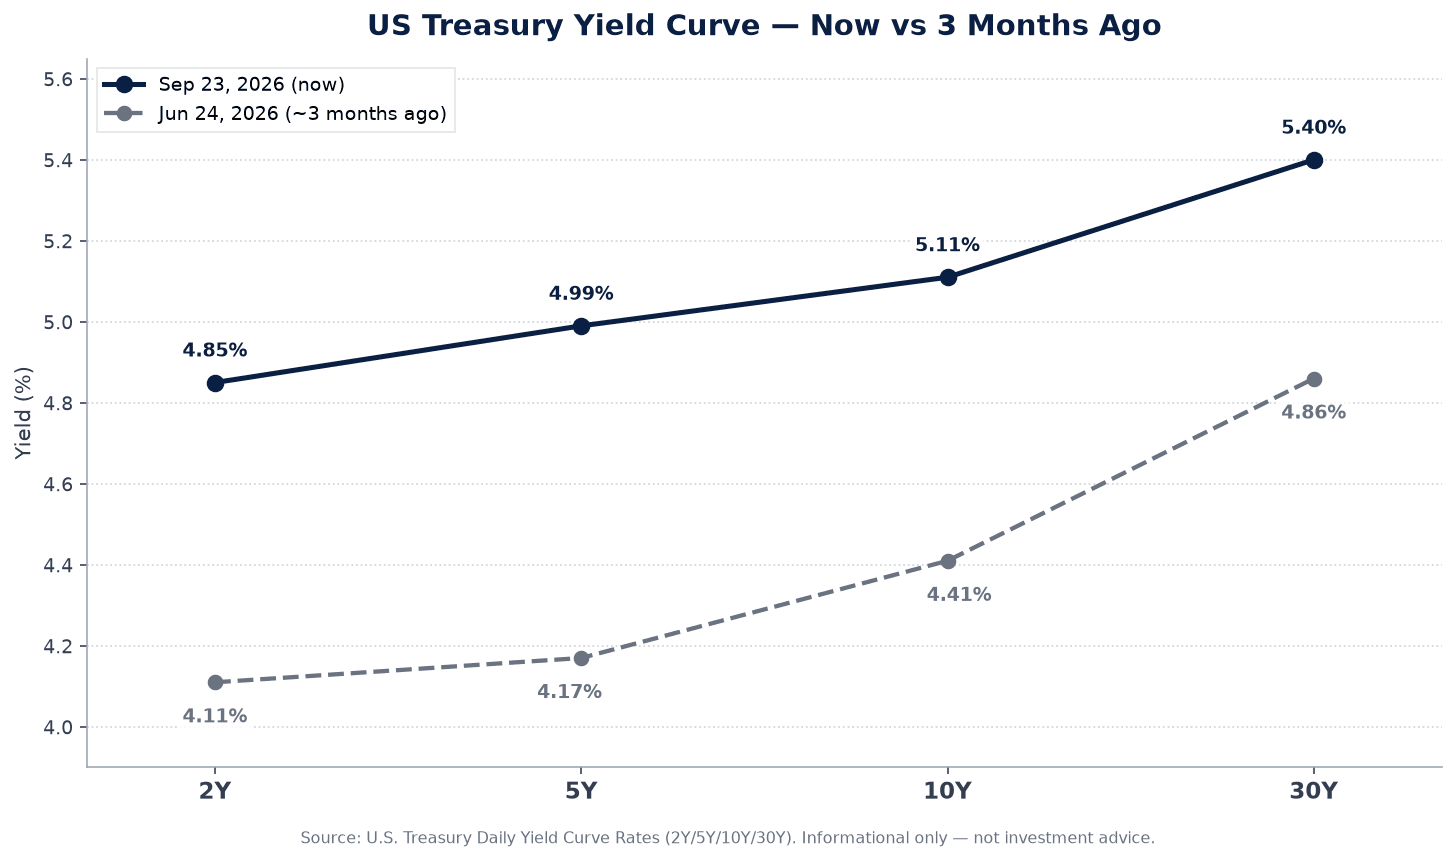
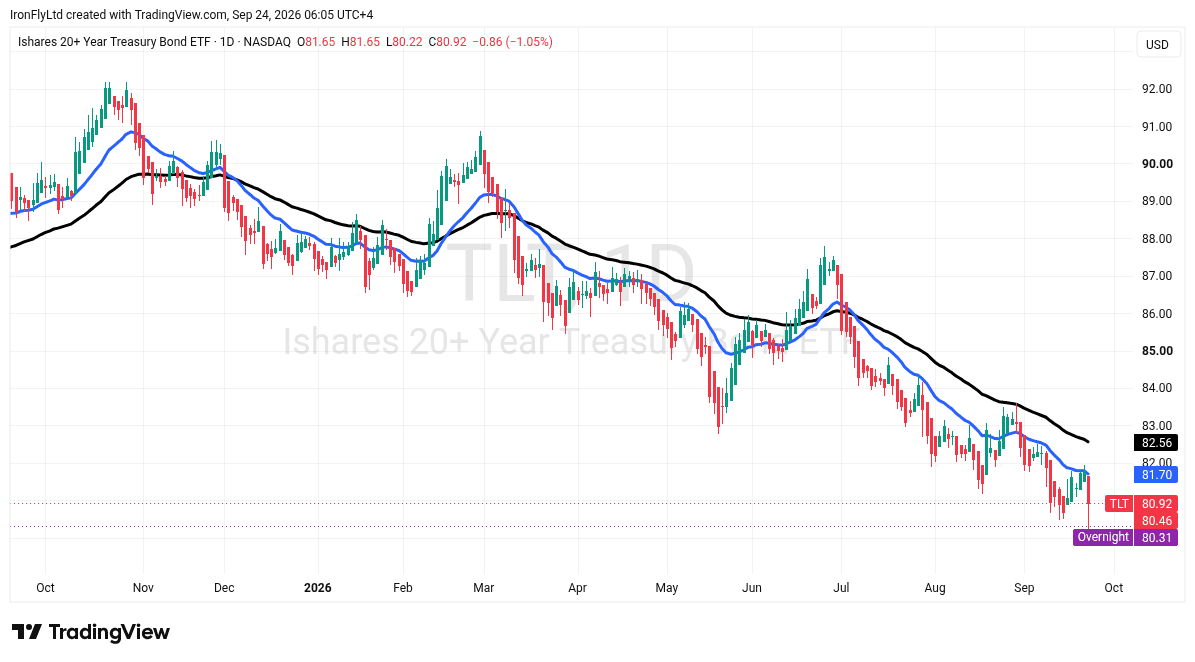
Yield curve - 2s/5s/10s/30s today vs three months ago. Flattening lift into 2007-era 10y territory. TLT Heikin Ashi with 20- and 50-day EMAs - the duration dump in candles.
TLT
What to watch
- Initial claims (cons 201K; prev 196K) and continuing claims (cons 1750K) - soft print cushions; hot print tightens further.
- New home sales (cons 0.62M) into a 10y above 5%.
- Fed speak: Williams, Barkin, Hammack, Paulson - hike-path / sticky-prices risk elevated after Barr.
- Whether the 10y holds above 5.10, that is the hinge for equity multiples today.
Bottom line
Diplomacy met duration. Soft oil (~$97 Brent, under $100 live) is the other side of the split. Wednesday’s brief reclaim near $103 faded. Hot PMIs plus hawkish speak put the 10y into ~2007 territory anyway. Nasdaq’s high came off; S&P’s unfinished August test is further away. Soft landing is on probation until Claims, homes, and the Fed speakers say otherwise - and until 5.10 on the 10y stops holding.
We don’t fight the tape. We also don’t confuse a one-day rates scare with a finished regime — but duration just took the first punch.